Companies and Subjects discussed in this morning's report include: Ulta's upside 2Q26, with acceleration in the two-year comp, Gap's mixed quarter, with slowing trends at Old Navy and an ON leadership change, Dollar General doubling down on the $1 price point, Burlington opened a record 50+ stores in 2Q26...

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Friday, August 28, 2026 | Published Daily by ~11:30 AM ET
Upside from Ulta Beauty and a Better-than-Feared Second Quarter from Gap in Focus...
NEXT WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/31)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
Tuesday (9/1)
- Haverty Furniture during a virtual investor meeting, hosted by KeyBanc
- Sportsman's Warehouse reports 2Q26, call 5:00 pm, Street at comps/EPS of flat/($0.12)
Wednesday (9/2)
- DoRCR publishes its monthly M&A + Capital Markets Analysis
- Somnigroup hosting a Business Update Call at 8:00 am, will be webcast
- Kontoor Brands hosts a Helly Hansen Investor Day, starts at 8:00 am, will be webcast
- ADP Employment for August at 8:15 am, Street at +46.5K vs. prior +44K
- Ollie's reports 2Q26, call 8:30 am, Street at comps down 0.7%, EPS of $1.12
- G-III Apparel reports 2Q27, call 8:30 am, Street at sales/EPS of $570.4M/$0.23
- PVH reports 2Q26 after the close, Street at sales/EPS of $2.09B/$3.08
- Costco reports August sales at 4:15 pm
- Petco reports 2Q26, call 4:15 pm, Street at comps up 0.7%, EPS of $0.07
- Five Below reports 2Q26, call 4:30 pm, Street at comps up 10.3%, EPS of $1.40
- Tilly's reports 2Q26, call 4:30 pm, Street at comps up 6.0%, EPS of $0.17
Thursday (9/3)
- Buckle reports August sales before the open
- Jobless Claims for the week ended 8/29/26 at 8:30 am, Street at 210K vs. prior 203K
- Victoria's Secret reports 2Q26, call 8:30 am, Street at comps up 8.8%, EPS of $0.77
- Genesco reports 2Q27, call 8:30 am, Street at flat comps, EPS of ($1.37)
- Lands' End reports 2Q26, call 8:30 am, Street at sales of $300.7M, EPS of $0.09
- PVH 2Q26 call at 9:00 am
- Duluth Trading reports 2Q26, call 9:30 am, Street at sales/EPS of $119.9M/($0.01)
- Lululemon reports 2Q26, call 4:30 pm, Street at comps down 4.6%, EPS of $1.79
- Oxford Industries reports 2Q26, call 4:30 pm, Street at sales/EPS of $394.6M/$1.31
- Torrid reports 2Q26, call 4:30 pm, Street at comps down 2.4%, EPS of ($0.03)
Friday (9/4)
- DoRCR publishes its proprietary Next Week's Calendar
- Nonfarm Payrolls for August at 8:30 am, Street at +62.5K vs. prior (23K), Unemployment is expected at 4.2% vs. prior 4.1%, Avg Hourly Earnings at +0.3% m/m vs. prior +0.1%
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is up 1.0% as of ~11:10 am vs. a 0.5% gain in the S&P 500. Retail stocks are outperforming after a better-than-expected second quarter from Ulta and a better-than-feared report from Gap, which is dealing with soft performance at Old Navy.
- Stronger retail stocks include GAP, up 14% after better-than-feared results, LVLU (up 9%), BBWI (up 6%), BBW (up 5%, recovering some of yesterday's losses) and TLYS (up 5%).
- Weaker retail stocks include volatile DBGI, which is down 10%, also MNSO (down 7%, mixed June quarter), BURL (down 4%), ULTA (down 4%, reported) and PRPL (down 3%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
- Comps increased 3.8% on top of +6.7% last year and were better than the Street's +2.3% estimate and were driven by a high-teens % increase in e-commerce comps and "modest comp growth" at the stores, while total sales grew 9% y/y to $3.04B.
- Fragrance was the strongest category with a high-teens % comp, then Haircare, up HSD%, Makeup, essentially flat, and Skincare & Wellness, with a modest comp decline.
- EPS were $6.55 vs. $5.78 last year and the Street's $6.20 estimate and incorporated a slight decline in gross margin on the mid-2025 acquisition of Space NK.
- Inventories look good and were flat y/y on improved inventory management.
- For the year, comps are now expected to increase 3.2%-3.7%, up from a prior +2.5%-3.5%, while total sales are expected to grow 6.7%-7.2% from FY25's $12.39B, and operating income is expected to increase 8.3%-9.3% from FY25's $1.53B and vs. a prior +6.5%-9.0%.
- Adjusted EPS are expected at $28.70-$29.00 vs. $25.80 in FY25 and a prior $28.36-$28.80 and assume $1.8B in stock buybacks for the year, up from a prior plan of $1.5B.
- On the Call, CEO Kecia Steelman said Ulta didn't see "any notable changes in consumer behavior" in the second quarter and noted continued strength in prestige beauty.
- DoRCR INSIGHT: A strong report overall, especially the acceleration in the two-year comp, suggests Ulta continues to gain market share in the beauty category even as competition with Walmart, Target, Amazon and DTC online pure-plays intensifies, and also suggests general category resilience despite cumulative inflation impacts on discretionary consumer spending.
- Comps decreased 1% vs. the Street's +0.2% estimate and incorporated a 4% decline at Old Navy, a 10% increase at Gap, a 3% increase at Banana Republic and a 12% decrease at Athleta on top of (9%) last year, while total sales decreased 2% to $3.65B.
- Store sales fell 3% y/y, while online sales decreased 1% and were 35% of the total.
- Excluding net IEEPA tariff recovery, adjusted EPS were $0.52 vs. $0.57 last year and the Street's $0.48 estimate and incorporated 80 bps of merch margin improvement on tariff mitigation, momentum at the Gap brand, and higher AUR across all brands.
- Higher promotions at Old Navy were a partial gross margin offset.
- Inventories look good and were essentially flat y/y at the end of the quarter.
- Full-year guidance now includes 1.0%-1.5% growth in sales from FY25's $15.37B and vs. a prior +1%-2%, an adjusted op margin of 7.4%-7.6% vs. 7.3% in FY25 and vs. a prior 7.3%-7.5%, and adjusted EPS of $2.35-$2.45 vs. $2.13 in FY25 and excluding net tariff recovery.
- FY26 guidance assumes third quarter sales are up 1.5%-2.5% y/y, implying an improved trend, and also assumes Old Navy comps are flat to down 1% for the year vs. a prior flat to up 1%, while Gap comps increase by a HSD%-LDD% vs. a prior up high-single digits.
- On the Call, CEO Richard Dixon said consumers are being "resilient but discerning."
- DoRCR INSIGHT: While this doesn't change Gap's positive story about rebuilding brand equity via better merchandising, better storytelling and better execution under CEO Richard Dixon, the uneven performance by brand is problematic, especially the slowdown at Old Navy, which generates 50%+ of total sales and is now expected to comp flat to down 1% for the year.
OTHER DEVELOPMENTS
Dollar General said during its second quarter conference call yesterday sales of items at or below $1, of which there are ~2K, including ~600 Value Valley SKUs, performed well, especially the rotating Value Valley offering, which comped up 16%+ vs. the chain average of +3.5%.
COMMERCIAL REAL ESTATE
Burlington opened a record 51 new stores in its second quarter and relocated six stores, finished with 1,287 total stores, and is still planning to open 115 net new stores for the year, mostly in the 27K gross square foot area and with a concentration in very productive strip centers.
Aritzia (Canada, 140+ stores in North America) opened its first store in Alabama yesterday, at The Summit in Birmingham, part of a plan to open 12-13 new stores this year, mostly in the US.
Tecovas, a digitally native Western boots/wear retailer with 60+ stores, is opening ~15 stores a year and plans to open seven more by the end of 2026 and ~15 in 2027 acc'd to Chief Retail Officer Kim Heidt, who says the brand is balancing store growth with e-comm and wholesale.
MANAGEMENT UPDATES
Gap President and CEO of Old Navy since mid-2022 and former 25+ year Walmart exec Haio Barbeito is transitioning into an advisory role and will be succeeded by Old Navy Chief Customer Officer since March 2026 and former 25+ year Target exec Michael Francis at the start of November.
Nike has hired 14-year Walmart exec -- in a variety of positions -- and former longtime Diageo (alcoholic beverages) exec Jane Ewing as Chief Commercial Officer, starts in early September, will join the Senior Leadership Team, and will report to CEO Elliott Hill.
- We note Nike had eliminated the Chief Commercial Officer position last December.
MACRO/CONSUMER INSIGHT
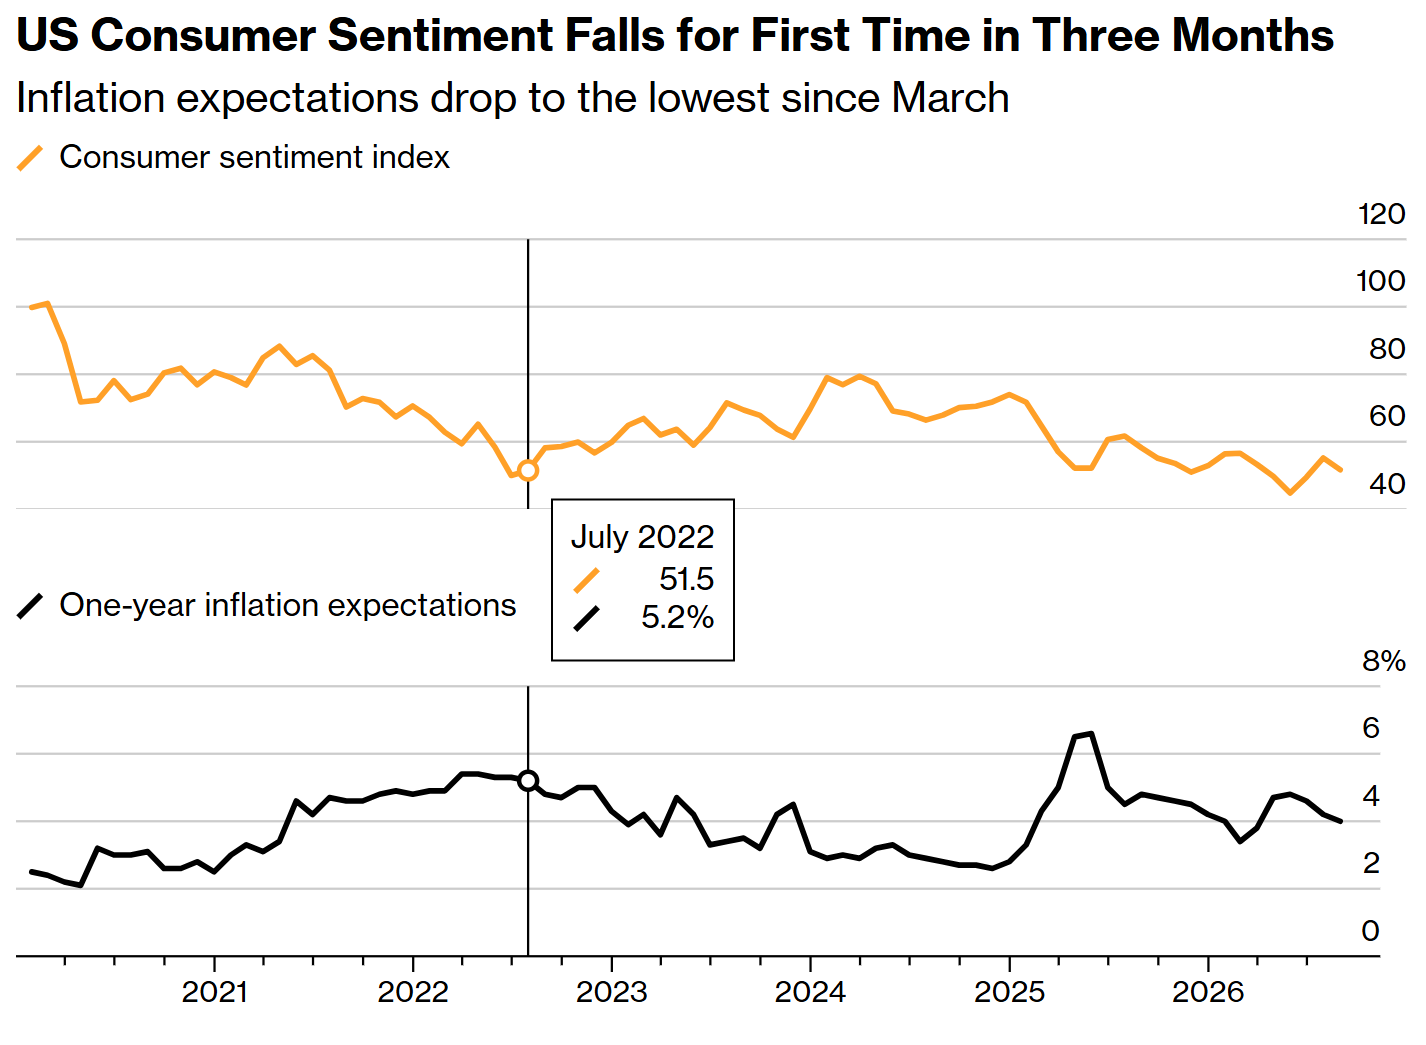
Out at 10:00 am, U. Mich. Sentiment for August (final) was a bit better than expected at 51.7 vs. the Street's 50.8 estimate, though it was down 6% from July and down 11% from August 2025 as consumer anxiety around gas prices and persistent inflation continues to be an overhang.
- Expectations for inflation over the next 12 months decreased slightly, to +4.0%.
- DoRCR INSIGHT: Sentiment and spending have not correlated at all in recent quarters, but fragile consumer psychology, along with a low savings rate, could make for a much tougher retail dynamic if we get another month or two of negative Nonfarm Payrolls.
Out yesterday, Jobless Claims for the week ended 8/22/26 were lower than expected at 203K vs. the Street's 210K estimate and down 4K from a revised 207K the prior week, while Continuing Claims, which are reported with a week's lag, decreased by 18K, to 1.78M.
- DoRCR INSIGHT: Reassuring to see yet another low Jobless Claims number after the weak Nonfarm Payrolls for July report -- down 23K -- supports the "low-hire, low-fire" narrative around the labor mkt, and with Unemployment at 4.1%, is positive for consumer spending.
Out Wednesday, Personal Income for July was stronger than expected and increased +0.4% m/m vs. the Street's +0.2% estimate, while Personal Spending was right in line at +0.2% and a slight deceleration from an upwardly revised +0.4% m/m increase in June.
- The core PCE price index, which is the Fed's preferred inflation metric, rose 3.3% y/y, while inflation-adjusted consumer spending was essentially flat in July.
- Also of note, disposable income rose 0.4% m/m, most since January, and the savings rate rose to a four-month high of 3% but remained low vs. historical averages.
- DoRCR INSIGHT: Wages and income are growing at a solid clip, supported by the "low-hire, low-fire" labor market, and consumers continue to spend, though with increasing caution/concern and some pockets of weakness, e.g. the mass athletic footwear and apparel space.
Source: University of Michigan and Bloomberg (for chart)
SELECT ANALYST ACTIONS
Amazon (AMZN, $256.26) Evercore ISI reiterates an Outperform rating and raises its target from $315 to $355 after completing its 14th Annual U.S. Online Retail survey, says it is seeing evidence Agentic AI is additive and notes 57% of Alexa AI users have purchased a product they previously didn't know about, also notes Amazon's general leadership in online retail, a re-acceleration in usage of same-day shipping, and signs delivery of perishables is proving to be a "real Grocery unlock."
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.