Special Note: DoRCR is launching a monthly webinar for our subscribers, will be the second Wednesday of each month at 2:00 pm ET and cover macro/consumer + topical issues. The first one is Wednesday, 8/12/26, and we will have the link to join in our calendar, starting with Monday morning's report.

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Friday, August 7, 2026 | Published Daily by ~11:30 AM ET
Under Armour's Trends Still Soft, Spencer Spirit Confirms Hot Topic Acquisition, Weak Jobs...
NEXT WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/10)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
- Purple Innovation reports 2Q26, call 4:30 pm, Street at sales/EPS of $104.4M/($2.18)
Tuesday (8/11)
- On Holding reports 2Q26, call 8:00 am, Street at sales/EPS of CHF880.3M/CHF0.34
- Existing Home Sales for July at 10:00 am, Street at 4.08M SAAR vs. prior 4.09M
- Sally Beauty at the Canaccord Genuity Growth Conference at 10:00 am
Wednesday (8/12)
- Warby Parker doing meetings in Minneapolis/Chicago today/tomorrow, hosted by BTIG
- Consumer Price Index for July at 8:30 am, Street at +3.4% y/y vs. prior +3.5%
- Kontoor Brands reports 2Q26, call 8:30 am, Street at sales/EPS of $587.0M/$1.06
- DoRCR hosts its monthly Retail & Consumer webinar at 2:00 pm, link to follow
- Grocery Outlet reports 2Q26, call 4:30 pm, Street at comps down 1.5%, EPS of $0.13
- Fossil reports 2Q26, call 5:00 pm, Street at sales/EPS of $199.3M/($0.36)
- Lulu's Fashion Lounge reports 2Q26, call 5:00 pm, no Street estimates
Thursday (8/13)
- Tapestry reports 4Q26, call 8:00 am, Street at sales/EPS of $1.87B/$1.28
- Birkenstock reports 3Q26, call 8:00 am, Street at sales/EPS of EUR715.0M/EUR0.76
- YETI reports 2Q26, call 8:00 am, Street at sales/EPS of $483.7M/$0.54
- Producer Price Index for July at 8:30 am, Street at +0.1% m/m vs. prior (0.3%)
- Jobless Claims for the week ended 8/8/26 at 8:30 am, Street at 204.5K vs. prior 199K
- Wolverine Worldwide reports 2Q26, call 8:30 am, Street at sales/EPS of $500.6M/$0.38
- Yesway reports 2Q26, call 8:30 am, Street at comps up 2.0%, EPS of $0.47
Friday (8/14)
- DoRCR publishes its proprietary Next Week's Calendar
- Retail Sales for July at 8:30 am, Street at +0.1% m/m vs. prior +0.2%
- U. Mich. Sentiment for August (preliminary) at 10:00 am, Street at 53.5 vs. prior 55.2
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is up 0.9% as of ~11:15 am vs. a 0.7% gain in the S&P 500, which is higher as a weak Nonfarm Payrolls for July report eases pressure on the Fed to raise interest rates.
- Strong retail stocks include FIGS, which is up 28% on a beat-and-raise 2Q26 + $100M stock buyback boost, also DXLG (up 11%), BARK (up 11%), ELF (up 6%) and DBGI (up 9%).
- Weaker retail stocks include NGVC, which is down 12% after downside results, also NEGG (down 7%), LANV (down 5%), REAL (down 4%, reported) and ARHS (down 4%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
Under Armour (UAA, $6.39) had a tough 1Q27 (June) with in-line revs down 4% y/y constant currency, same as the prior quarter and including a 9% decline in North America, while earnings were better than expected but got a big lift from IEEPA tariff recovery; mgmt lowered full-year revenue guidance to reflect softer demand, mostly in North America and Asia-Pacific, but kept the prior EPS range and noted expense disciplines and tariff refunds as offsets to the lower sales.
- Revs were $1.10B, down 4% y/y constant currency and incorporated a 9% decline in NA, to $610M, a 10% increase in EMEA, a 10% decrease in APAC, and a 1% increase in LATAM, also a 2% decline in reported wholesale revs, to $638M, and a 6% decrease in DTC, to $437M.
- The 6% decrease in DTC revs incorporated a 3% decrease at owned and operated stores and a 12% drop in eCommerce revs, which comprised 29% of total revs vs. 31% last year.
- Apparel revs decreased 2% to $734M, footwear (8%) to $245M, accessories (4%) to $96M.
- Adjusted EPS were $0.05 vs. $0.02 last year and the Street's $0.02 and incorporated 590 bps of gross margin improvement, mostly on tariff refund benefits, which were partially offset by unfavorable forex, unfavorable regional + channel mix, and "pricing headwinds."
- Inventories look fine and were down 3% y/y, essentially in line with the sales decline.
- New guidance includes a mid-single-digit % decline in revs from FY26's $4.97B vs. prior guidance for a slight decline, while adjusted EPS are still expected at $0.08-$0.02 vs. $0.12 in FY26 and now include $70M in tariff refunds and a $35M hit from war in the Middle East.
- DoRCR INSIGHT: There has been a clear erosion of Under Armour's brand equity b/c of discounting and an excess of product in the off-price channel in the US, so addressing the reliance on promotions to rebuild brand value and drive full-price sales makes sense; but there are other factors behind Under Armour's diminished relevance, including greater innovation elsewhere.
Analyst Actions that could move retail stocks today:
- eBay (EBAY, $110.14) Argus upgrades from Hold to Buy
- Etsy (ETSY, $82.26) JPM upgrades from Neutral to Overweight
- Gap (GAP, $20.52) Wells Fargo downgrades from Overweight to Equal Weight
OTHER DEVELOPMENTS
The RealReal (REAL, $12.77), which calls itself the "world's largest online marketplace for authenticated, resale luxury goods," had a better-than-expected 2Q26 (June) and grew GMV by 22% y/y, to $617M, an all-time high for any quarter, grew revs by 17%, to $193M, and doubled EBITDA y/y to $13.5M, and management raised full-year guidance, release here.
Natural Grocers (NGVC, $32.46) had a weaker-than-expected 3Q26 (June) and cited "a challenging consumer environment," though comps did show some sequential improvement, from +0.5% in the second quarter, to +1.2% in the third, while adjusted EBITDA fell 8% y/y to $22.5M and was pressured by an unfavorable mix of sales, higher shrink, and higher freight costs, and management trimmed the high-ends of guided ranges for new stores, comps and EPS for the fiscal year.
- Total sales grew 2% y/y to $334.7M vs. the Street's $347.2M estimate.
- The +1.2% comp incorporated a 3.1% increase in ticket and a 1.8% decrease in traffic.
e.l.f. Beauty CFO Mandy Fields said during the 1Q27 (June) call Wednesday afternoon it will launch rhode -- which did $160M of sales in the quarter -- across 19 European countries in September and will launch the e.l.f. brand in Brazil, and Fields also noted e.l.f. does only 20% of its sales outside the US vs. some competitors at 70% -- implies a "big white space" for international growth.
- The European and Brazil launches are both being done through Sephora.
Spencer Spirit Holdings is buying Hot Topic from Sycamore Partners for an undisclosed amount, though as we said yesterday, Bloomberg puts the price at $350M. Sycamore acquired Hot Topic in 2013 for $600M and took its plus-size fashion brand Torrid public in 2021. Spencer Spirit is based in NJ and owns Spencer's (650+ stores) and Spirit Halloween/Christmas. Hot Topic has 615+ namesake stores across the US and Canada and 280+ BoxLunch stores in the US.
COMMERCIAL REAL ESTATE
Hermes (France) opened a new store today in the Chicago market, at Plaza del Lago in Wilmette, IL, 8K sf over two levels and the second Hermes store in Chicago after East Oak Street.
MANAGEMENT UPDATES
Burlington Chief Human Resources Officer since 2023 and 13-year company HR exec Matt Pasch is leaving at the beginning of September and will be succeeded by Barnes & Noble CHRO and former Canadian Tire CHRO (2019-2023) and longtime Ascena and Best Buy HR exec John Pershing.
Destination XL has appointed Chairman of the Board since 2020 Lionel Conacher as Interim CEO, effective next Wednesday, will take over from Harvey Kanter, who previously announced his retirement from the company and plans to also step down from the board on 8/11/26.
Sur La Table has hired Allbirds Chief Technology Officer for the past nine years and former Intuit Director of Engineering from 2013-2017 Benny Joseph as Chief Technology Officer.
MACRO/CONSUMER INSIGHT
Out at 8:30 am, Nonfarm Payrolls for July were much weaker than expected and fell 23K vs. the Street's +95K estimate after a downwardly revised +20K in June, while Unemployment declined slightly, to 4.1%, and Avg Hourly Earnings grew 3.2% y/y vs. expectations of +3.5%.
- DoRCR INSIGHT: Probably best not to spin this -- it is worrisome -- but other labor market indicators including weekly Jobless Claims, JOLTS, even ADP to some extent, point to stability if not underlying strength, so it makes sense -- esp with all the revisions -- to give the Nonfarm data another month or two before drawing broad conclusions about a jobs + wage slowdown.
Out yesterday, Jobless Claims for the week ended 8/1/26 were lower than expected at 199K vs. the Street's 205K estimate and essentially unchanged from the prior week, while Continuing Claims, which are reported with a week's lag, increased 24K from the prior week, to 1.80M.
- DoRCR INSIGHT: The labor market slowed significantly last year but appears to be in recovery mode despite AI, geopolitical instability/uncertainty, the spike in fuel prices, etc., and this is good for consumer spending, though higher fuel prices do erode discretionary spending power.
Out Wednesday, ADP Employment for July was weaker than expected at +44K vs. the Street's +75K estimate and after a revised +95K in June, while pay for those staying with their jobs held steady at +4.4% y/y, and pay for job-changers increased 7.0%, biggest y/y increase since mid-2025.
- DoRCR INSIGHT: Not a terrible month, and this data series is more limited in scope than the government's Nonfarm Payrolls report, also Jobless Claims, which have been very low, and other indicators (e.g. JOLTS) showing a solid overall labor market.
Out Tuesday and acc'd to the U.S. Energy Information Administration, a gallon of regular Unleaded Gasoline cost $4.08 on average across the US for the week ended 8/3/26, down $0.02 from the prior week but up $0.94 per gallon from the same week last year.
- A gallon of diesel cost $5.35, up $0.04 on the week and up $1.55 from last year.
- DoRCR INSIGHT: Gas prices could come down quickly with a US/Iran peace deal and reopening of the Strait of Hormuz, but for now, the significant y/y increase is a meaningful headwind to discretionary spending, esp by lower-income consumers (e.g. core dollar store customer).
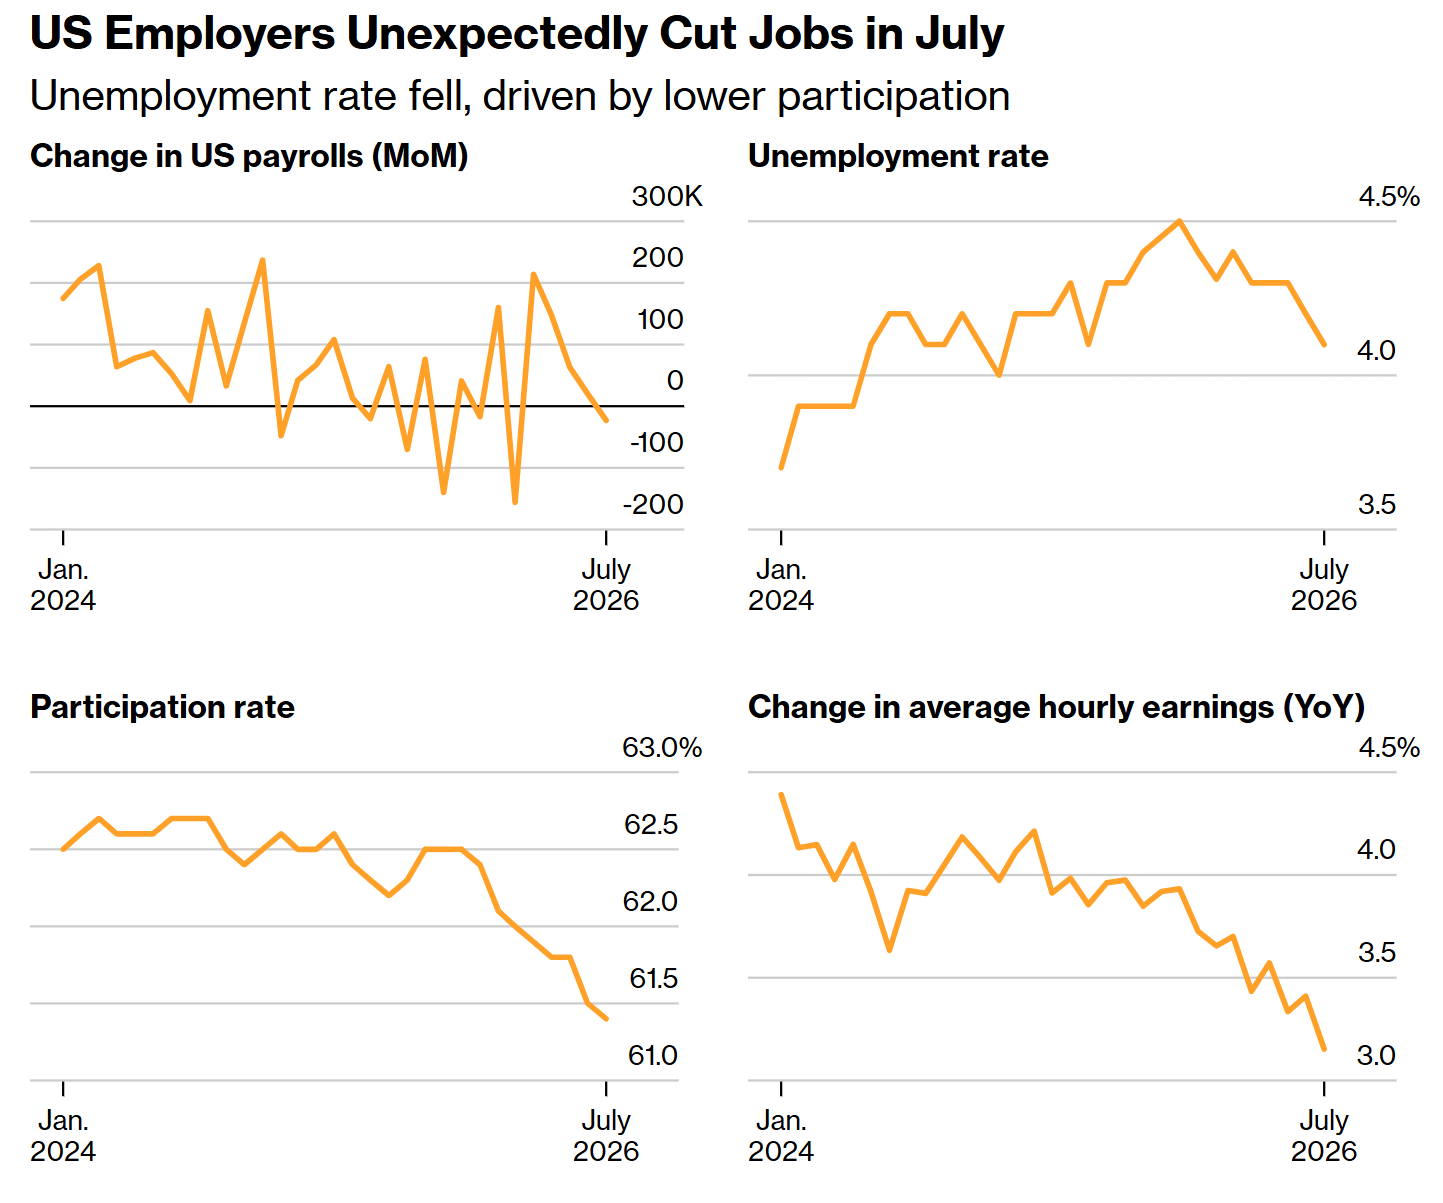
Source: BLS and Bloomberg (for chart)
SELECT ANALYST ACTIONS
Arhaus (ARHS, $9.68) Craig-Hallum upgraded from Hold to Buy and raised its target from $9 to $12 intra-day yesterday after the 2Q26 (June) results, said it was an impressive quarter and believes 2026 guidance is conservative and beatable given underlying momentum, also said Arhaus will use tariff refunds to offset higher fuel and shipping costs and reinvest in marketing and believes the company is "moving to the front of the pack" in the premium home furnishings category.
Gap (GAP, $20.52) Wells Fargo downgrades from Overweight to Equal Weight and lowers its target from $26 to $22 in front of 2Q26 (July) results near the end of the month, cites growing uncertainty around the Old Navy brand as the primary reason, says its channel checks suggest challenges with the current assortment, including with price/value, and says it does not see a quick fix.
eBay (EBAY, $110.14) Argus upgrades from Hold to Buy and establishes a $133 target after the 2Q26 (June) results, says the company is "executing masterfully in a tough environment" and raises its forecast, also says eBay continues to launch new and enhanced technology solutions meant to deliver a frictionless buying and selling experience for platform users.
Etsy (ETSY, $82.26) JPM upgrades from Neutral to Overweight and raises its target from $85 to $100 after the 2Q26 (June) results, thinks the company is well positioned to deliver sustainable growth, driven by improving marketplace fundamentals and social commerce initiatives, also says it is growing more confident in active buyer acquisition, engagement and retention.
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.