Companies and Subjects discussed in this morning's report include: CVS reports an upside 2Q26, but with flat Pharmacy & Consumer Wellness revs, Capri reports its June quarter, with down sales at Michael Kors, Revolve grows active customers by 11%, Bed Bath remains a confusing story, Canada Goose selling Baffin...

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Wednesday, August 5, 2026 | Published Daily by ~11:30 AM ET
Results from CVS, Capri, Revolve and BBBY, Retail & Consumer M&A + IPOs Picking Up...
THIS WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/3)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
- Sally Beauty reports 3Q26, call 8:30 am, Street at comps up 0.3%, EPS of $0.53
Tuesday (8/4)
- Wayfair reports 2Q26, call 8:00 am, Street at sales/EPS of $3.47B/$0.90
- Haverty Furniture reports 2Q26, call 10:00 am, no Street estimates
- Steven Madden meeting with investors in NYC at 10:00 am, hosted by BTIG
- Revolve reports 2Q26, call 4:30 pm, Street at sales/EPS of $341.9M/$0.21
- Bed Bath & Beyond reports 2Q26, call 4:30 pm, Street at sales/EPS of $362.4M/($0.36)
Wednesday (8/5)
- DoRCR publishes its proprietary monthly M&A + Capital Markets Analysis
- CVS reports 2Q26, call 8:00 am, Street at comps down 0.9%, EPS of $1.85
- ADP Employment for July at 8:15 am, Street at +75K vs. prior +98K
- Capri reports 1Q27, call 8:30 am, Street at sales/EPS of $756.3M/$0.40
- Costco reports July sales at 4:15 pm
- e.l.f. Beauty reports 1Q27, call 4:30 pm, Street at sales/EPS of $431.2M/$0.71
- thredUP reports 2Q26, call 4:30 pm, Street at sales/EPS of $90.3M/($0.03)
- a.k.a. Brands reports 2Q26, call 4:30 pm, Street at sales/EPS of $162.6M/($0.41)
- eBay reports 2Q26, call 5:30 pm, Street at sales/EPS of $3.02B/$1.50
Thursday (8/6)
- Buckle reports July sales before the open
- Somnigroup reports 2Q26, call 8:00 am, Street at sales/EPS of $1.88B/$0.58
- Warby Parker reports 2Q26, call 8:00 am, Street at sales/EPS of $238.0M/$0.10
- Bob's Discount Furniture reports 2Q26, call 8:00 am, St at comps/EPS of +1.7%/$0.20
- Jobless Claims for the week ended 8/1/26 at 8:30 am, Street at 206K vs. prior 197K
- Etsy reports 2Q26, call 8:30 am, Street at sales/EPS of $646.1M/$0.75
- Arhaus reports 2Q26, call 8:30 am, Street at comps down 1.6%, EPS of $0.16
- Brilliant Earth reports 2Q26, call 8:30 am, Street at sales/EPS of $111.4M/($0.00)
- Ralph Lauren reports 1Q27, call 9:00 am, Street at sales/EPS of $1.87B/$4.32
- Natural Grocers reports 3Q26, call 4:30 pm, Street at sales/EPS of $347.2M/$0.52
- FIGS reports 2Q26, call 5:00 pm, Street at sales/EPS of $186.2M/$0.07
- The RealReal reports 2Q26, call 5:00 pm, Street at sales/EPS of $188.1M/($0.02)
Friday (8/7)
- DoRCR publishes its proprietary Next Week's Calendar
- Nonfarm Payrolls for July at 8:30 am, Street at +100K vs. prior +57K, while Unemployment is expected to be unchanged at 4.2%, Avg Hourly Earnings at +3.5% y/y vs. prior +3.5%
- Under Armour reports 1Q27, call 8:30 am, Street at sales/EPS of $1.11B/$0.02
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is down 0.4% as of ~11:30 am vs. a slight gain in the S&P 500, which is higher on continued optimism for a US/Iran deal to open the Strait of Hormuz.
- Weaker retail stocks include BBBY, down 17% on results and other matters, DBGI (down 13%, investor skepticism about a buyout proposal), CVS (down 6% despite an upside 2Q26), W (down 5%, giving back some of yesterday's gains) and RVLV (down 5% on results).
- Stronger retail stocks include NEGG, AKA, LOVE, RH and ARHS, all up 4%-8%.
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
CVS (CVS, $104.42) had an overall strong and better-than-expected 2Q26 (June), though with another quarter of flat y/y revs in Pharmacy & Consumer Wellness, which continues to be impacted by regulatory-related price reductions on some drugs, new (lower-priced) generic drugs, and Rx reimbursement pressures; mgmt raised full-year earnings and cash flow from ops guidance.
- Total revs grew 7% y/y to $106.10B vs. the Street's $100.03B and after +6% in the first quarter and incorporated flattish Pharmacy & Consumer Wellness revs of $33.82B.
- Comps increased 2.6%, with Pharmacy up 2.9% and front-store up 1.0%, and P&CW sales continued to benefit from incremental Rx vol from the acquisition of Rite Aid script files
- Adjusted EPS were $2.58 vs. $1.81 last year and the Street's $1.85 estimate and were driven largely by improved profit performance in CVS's Health Care Benefits segment.
- New 2026 guidance includes revs of at least $414B vs. $402.07B in 2025 and a prior $405B+, adjusted EPS of $7.90-$8.10 vs. $6.75 in 2025 and a prior $7.30-$7.50, and cash flow from operations of at least $11.5B vs. prior guidance for at least $9.5B.
- DoRCR INSIGHT: There are always many moving pieces in CVS's reports, but it does seem clear the company is benefiting from industry-wide store closings over the last several years and the 2025 Ch 11 and shutdown of #3 drugstore chain Rite Aid, which completed the liquidation and closure of its last group of stores last fall -- there were 1,200+ in May 2025.
Capri (CPRI, $16.52) had an overall better-than-expected 1Q27 (June), though with continued weakness at the core Michael Kors banner, where constant-currency revs fell 8% y/y, similar to the fourth quarter, and management lowered full-year revenue guidance to reflect this dynamic but maintained earnings guidance and said it is taking actions to reduce operating expenses.
- Revs were $769M vs. the Street's $756.6M and incorporated Michael Kors revs of $590M, down 8% y/y in constant currency, and Jimmy Choo revs of $179M, up 9%.
- Adjusted EPS were $0.67 vs. $0.50 last year and the Street's $0.40 estimate and incorporated 200 bps of gross margin improvement on higher full-price sales and lower tariffs y/y.
- Inventories look good/lean and were down 20% y/y at the end of the quarter.
- Full-year guidance now includes revs of ~$3.4B vs. a prior ~$3.53B and reflects impacts from inventory delays at Michael Kors in 2Q27 ($50M), also soft trends in EMEA b/c of war in the Middle East ($50M) and greater forex pressures ($35M) than assumed previously.
- Full-year FY27 EPS are still expected to be ~$2.15, a 40%+ y/y increase from FY26.
- DoRCR INSIGHT: Not a terrible report overall, and good to see the improved +9% performance at Jimmy Choo after a flat fourth quarter, but Michael Kors is the core biz, and there is a trendline down high-single-digit % developing, with no good reasons to expect a big change.
Revolve (RVLV, $26.37) reported a good 2Q26 (June) with sequential acceleration in active customers, which grew 11% y/y, the fastest rate in nearly three years, while adjusted EBITDA was down slightly y/y when excluding $5.6M in IEEPA tariff refunds and was pressured by marketing investments around growth initiatives, including the spring launch of owned brand REVOLVE Los Angeles.
- Total sales grew 12% y/y to $347.4M vs. the Street's $341.9M and after +16% in the first quarter and incorporated REVOLVE sales of $302.5M, up 13%, FWRD sales of $44.9M, up 11%, domestic sales of $269.1M, up 11%, and international sales of $78.4M, up 16% y/y.
- Active customers grew 11% y/y to 3.04M after +8% in the first quarter, while total orders placed increased 11% y/y, and average order value was essentially flat at $299.
- Adjusted EBITDA was $26.8M vs. $22.9M last year and included a $5.6M gross margin benefit from tariff refunds; excluding this, gross margin increased 90 bps.
- Inventories look high and were up 25% at the end of the quarter, though the increase reflects growth initiatives, including the spring launch of the REVOLVE Los Angeles brand.
- Full-year guidance for gross margin, fulfillment, selling and distribution expenses is unchanged, while ranges for marketing and G&A expenses were tweaked higher.
- Mgmt called out the recent launch of Grow-Good beauty products -- created with Cardi B -- as another key revenue driver, esp as it relates to connecting with next-gen consumers.
- From the Call: Sales accelerated in July, first month of 3Q26, and increased 18%.
- DoRCR INSIGHT: The growth in active customers -- up 11% y/y after +8% in the first quarter +6% in the fourth quarter and +5% in the third -- speaks to Revolve's on-trend product and strong marketing program, while the bottom line is seeing some NT pressure from growth spending.
Bed Bath & Beyond (BBBY, $5.56) reported largely in-line 2Q26 (June) sales of $361.2M, up 28% y/y and incorporating the acquisition -- during the quarter -- of the former Kirkland's Home business, while the adjusted EBITDA loss grew from ($8M) last year to ($12M) in 2Q26 but was better than the Street's ($21.1M) estimate; mgmt announced a few things, including a corporate name change.
- Active customers increased 47% y/y to 6.4M, orders delivered increased 117% to 2.8M.
- Mgmt said growth in revs was a function of "strength" in the base online marketplace business, an improved assortment, benefits from investments in customer experience, and revs from the acquisition of The Brand House Collective (Kirkland's).
- Mgmt also noted better engagement and conversion and increased order frequency.
- Bed Bath & Beyond will change its name to Neighborhood Intelligence and begin trading on the Nasdaq under the ticker NXH on Monday, 8/17/26, and the company is also planning to relocate its corporate HQ from Salt Lake City to Nashville.
- Neighborhood Intelligence will be organized around three pillars: Omni-Channel Retail, which includes the stores and retail e-commerce, Home Services, and Home Ownership.
- Mgmt sees potential for $50M+ of annualized cost savings over the next 12 months as all the acquired businesses are brought onto one shared corporate platform.
- As a point of reference, the company's current and soon-to-be-acquired brands include Bed Bath & Beyond, The Container Store, Kirkland's, Lumber Liquidators, Cabinets to Go, Overstock, buybuy BABY, and some home services and home ownership businesses.
- DoRCR INSIGHT: There are a lot of moving pieces here with all the acquisitions and directional changes, and it's tough to benchmark progress and figure out what is working and what is not; the corporate name change adds another layer of confusion and makes it hard to assess what the core business is ultimately going to be and how the push with physical stores really fits in.
Analyst Actions that could move retail stocks today:
- Burlington (BURL, $367.82) Citi downgrades from Buy to Neutral
- Best Buy (BBY, $86.35) Jefferies downgrades from Buy to Hold
- e.l.f. Beauty (ELF, $87.84) Bernstein upgrades from Market Perform to Outperform
OTHER DEVELOPMENTS
Digital Brands Group (DBGI, $21.63), which announced a strategic review earlier this week, has rec'd a proposal from an unnamed existing shareholder with a net worth of $1B+ to acquire all outstanding shares of the company for $77.58 per share, or an implied $46.5M.
- The $77.58 is a nearly 260% premium over yesterday's closing price of $21.63.
- Going into this, DBGI shares were down 95%+ YTD on a split-adjusted basis.
Ethan Allen (ETD, $23.89) 5.0% shareholder Doug Bergeron has launched a proxy fight and nominated six director candidates for election at the 2026 AGM, letter here, says the firm wants Ethan Allen to restore profitable growth, improve execution in digital and omnichannel, and plan for the succession of Chairman, President and CEO since the mid-late 1980s Farooq Kathwari.
- Ethan Allen's board includes six members, so Bergeron wants a full replacement.
- ETD shares are down 18% over the last 12 months, and market cap is ~$620M.
Walmart (WMT, $111.55) has completed its previously announced acquisition of French streaming TV advertising platform Vibe.co; the WSJ previously reported a $1.4B transaction value.
Bed Bath & Beyond (BBBY, $5.56) filed -- through a "shelf" registration -- to sell up to $200M of stock, debt, warrants, purchase contracts and units and said it has entered into a capital on demand sales agreement with Jones Trading for up to $200M of its common stock.
- And in a separate 8-K, the company said CEO Marcus Lemonis had voluntarily elected to forfeit options to buy 1.8M shares so that these options may be used for other employees.
Abercrombie & Fitch (ANF, $110.20) is exploring options for its China operations acc'd to Bloomberg, which says the company is working with an adviser and may sell a stake in the business valued at several hundred millions, while another option includes bringing in local partners to help grow the business amid "significant headwinds" in China that have held the business back.
Publix (employee owned) reported an uncharacteristic decline -- down 0.5% -- in comp store sales for its second quarter, the fourth quarter in a row of slowing sales as industry unit volumes continue to trend down and as prices also trend lower amid stepped-up competition with Amazon's new perishables delivery initiative and as Walmart and Kroger investor in price.
- Like others, Publix's Rx comps are being pressured by the Inflation Reduction Act.
Gap is partnering with Chalhoub Group to expand its Gap, Banana Republic and Athleta businesses across the Gulf Region in the Middle East and plans a phased omnichannel rollout, starting with e-commerce through the balance of this year in the UAE, Saudi Arabia and Kuwait, and then the opening of physical stores across the region beginning in 2027.
Chanel's (France, private) comparable revs grew 16% y/y in the first half of 2026 acc'd to Bloomberg, which says the strong performance was driven by new collections from designer Matthieu Blazy that launched in March and by the US, where sales grew 25%+ y/y, while revs grew across all regions, including China and the Middle East; Bloomberg also said strong trends continue in July.
 Canada Goose is selling its Baffin performance footwear brand to L.P. Royer for an undisclosed amount and expects the transaction to close this month. Canada Goose acquired Baffin in 2018 for C$33M and says it has gained expertise and infrastructure that helped it launch its own footwear collection in 2021. The company plans to put even more focus on and increase its investment in the Canada Goose brands across merch categories, seasons and markets.
COMMERCIAL REAL ESTATE
Publix (employee owned) opened 16 new stores, closed eight stores and remodeled 56 stores during the first half of the year, currently has ~1,440 supermarkets across FL and the Southeast.
MANAGEMENT UPDATES
We're not seeing anything too significant/noteworthy this morning...
M&A + CAPITAL MARKETS ANALYSIS
Significant YTD Developments
In July, DoRCR highlighted 28 significant M&A + (non-debt) Capital Markets developments across retail and closely associated areas of the broader consumer space, both in the US and in larger global economies, e.g. China, the UK, EU, Canada, etc. The 28 compare to 21 in July 2025.
Through the first seven months of this year, we've highlighted 180 significant developments, up from 169 through the first seven months of 2025 and reflecting a mix of positives and negatives, including the strong stock market, which is contributing to a pick-up in stock-based M&A and IPO activity, and still-high interest rates, which are holding back debt-financed M&A and making it more difficult for startups to raise new capital from investors.
FOR ALL OF 2025, DoRCR highlighted 298 significant M&A + Capital Markets developments vs. 400 for all of 2024, or a year-over-year decline of 26%.
The most notable M&A developments in July included Kroger's announced $1.65B acquisition of Pittsburgh-based and family-owned Giant Eagle, expected to close in 2027, to be accretive to Kroger's adjusted EPS in the second full year, and involve "limited Giant Eagle store divestitures," and Bed Bath & Beyond's completion of its previously announced acquisition of The Container Store for ~$150M in BBBY stock and convertible notes.
Sleep Number's $700M sale (total value) to stalking-horse bidder Sleep Country Canada was approved by a bankruptcy court following a court-supervised sale process, and NY-based Mavis Tire Express Services said it would buy Pep Boys from Icahn Enterprises for $700M in cash.
Also in July, Gildan announced the sale of its HanesBrands Australian Business to BBFIT Investments for an EV of ~US$490M, said the deal will close in 2H26, and noted proceeds will be used to pay down a portion of its debt and accelerate a return to its target leverage, and eBay completed its previously announced acquisition of Depop from Etsy in a deal with a final consideration of $1.4B.
The most notable capital-raise developments in July included a Business Insider report saying live-shopping company Whatnot is looking to raise new capital at a $20B valuation, nearly double Whatnot's $11.5B valuation after a $225B Series F funding round co-led by DST Global and CapitalG in late-2025.
The most notable IPO/secondary developments included SHEIN's approval (by Chinese regulators) for a Hong Kong IPO, which could happen in the middle August and value the company at $30B-$40B acc'd to recent reports, a Bloomberg report saying Michaels is approaching the time for a possible IPO under private equity firm Apollo, which bought the company five years ago in a deal valued at $5B, and a filing by Tailored Brands to go public again, on the Nasdaq, ticker MENW.
At the end of the month, Reformation priced 14.1M shares at the low-end of a $15-$17 range in its IPO and raised gross proceeds of just over $210M at an initial equity valuation of $886M.
- Kroger said it will acquire family-owned Giant Eagle for $1.65B, including $1.25B in cash
- DUSK, a UK-based online homewares/furniture retailer, will go public on the LSE later this year and has selected Panmure Liberum and Zeus to manage the IPO acc'd to Sky News
- Timex has taken full ownership of Swedish watch and jewelry brand Danielle Wellington
- Michaels, which is owned by Apollo, is approaching the time for a possible IPO (Bloomberg)
- Destination XL recommends holders reject an $0.84/sh tender offer from Zodiac Partners
- Style Capital (Milan) made an investment in Paris-based fragrance house Essential Parfums
- Versed (skincare/makeup) has been acquired by Windsong Global's Belle Brands platform
- Bed Bath & Beyond completed its $150M stock + notes acquisition of The Container Store
- Hugo Boss (Germany) tells holders to reject a EUR38/share offer from Frasers Group (UK)
- SHEIN (Singapore) has rec'd approval from Chinese regulators for a Hong Kong IPO
- Tailored Brands (controlled by Silver Point Cap) filed to IPO on the Nasdaq, ticker MENW
- GameStop has upped its active stake in eBay from 5.0% in May to 9.8% as of mid-July
- Destination XL recommends shareholders vote against a proposed merger with FullBeauty
- Sleep Number's Ch 11 sale to Sleep Country Canada was approved, $700M in total value
- H.I.G. Capital acquired majority ownership of Outward Hound (CO), amount undisclosed
- Stantt (NYC, menswear) has acquired Vastrm (CA), a custom + ready-made menswear brand
- Refined Cap (London) acquired a stake in women's fashion brand Never Fully Dressed (UK)
- Mavis Tire Express (NY) is acquiring Pep Boys from Icahn Enterprises for $700M in cash
- Frasers Group (UK) has acquired family-run, Scottish sportswear retailer Greaves Sports
- Crown Brands Group acquired Cosabella (Miami, lingerie) from Calida Group (Switzerland)
- Vida Shoes (NYC) acquired Donald Pliner (NYC, footwear) for an undisclosed amount
- Gildan (Canada) said it is selling HanesBrands Australia to BBFIT for an EV of ~US$490M
- Reformation (REF) priced 14.1M shares at $15 per and raised $210M in its IPO on the NYSE
- eBay completed its acquisition of Depop from Etsy, final consideration was $1.4B in cash
- Mammut, a Swiss outdoor brand, is being sold by Jacobs Capital to CPE (China)
- TSG Consumer is buying a majority stake in L.A.-based body care brand Saltair per WWD
- Whatnot (live shopping) is looking to raise new capital at a $20B valuation (Business Insider)
- King Kullen (28 grocery stores) is being acquired by Giunta's Meat Farms, both Long Island
M&A + Capital Markets developments of the past 12 months here, on our website
MACRO/CONSUMER INSIGHT
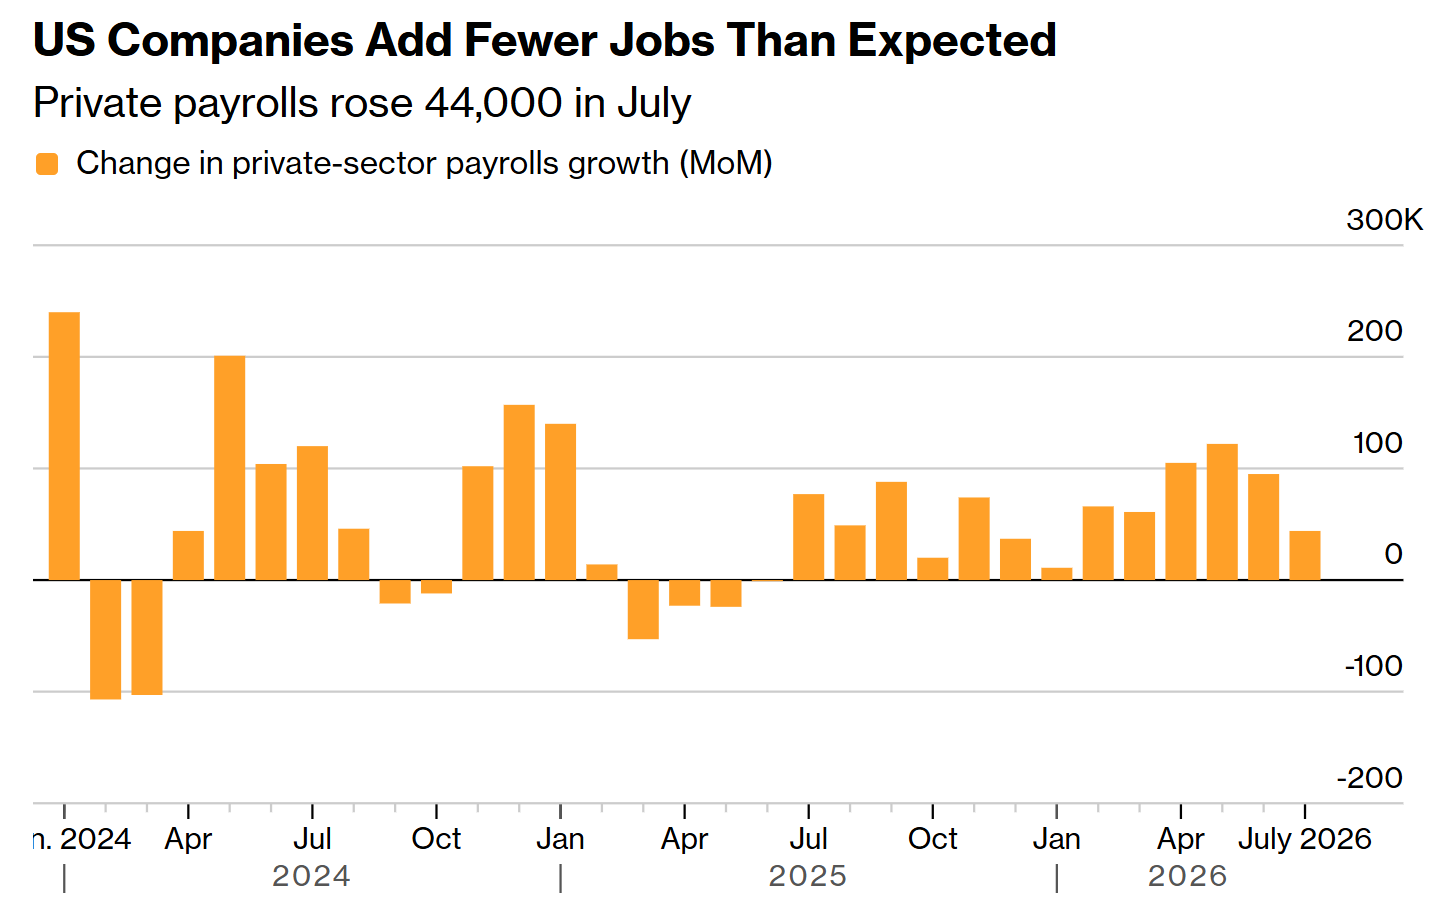
Out at 8:15 am, ADP Employment for July was weaker than expected at +44K vs. the Street's +75K estimate and after a revised +95K in June, while pay for those staying with their jobs held steady at +4.4% y/y, and pay for job-changers increased 7.0%, biggest y/y increase since mid-2025.
- DoRCR INSIGHT: Not a terrible month, and this data series is more limited in scope than the government's Nonfarm Payrolls report, which comes out Friday, also Jobless Claims, which have been very low, and other indicators showing a solid overall labor market.
Out yesterday and acc'd to the U.S. Energy Information Administration, a gallon of regular Unleaded Gasoline cost $4.08 on average across the US for the week ended 8/3/26, down $0.02 from the prior week but up $0.94 per gallon from the same week last year.
- A gallon of diesel cost $5.35, up $0.04 on the week and up $1.55 from last year.
- DoRCR INSIGHT: Gas prices could come down quickly with a US/Iran peace deal and reopening of the Strait of Hormuz, but for now, the significant y/y increase is a meaningful headwind to discretionary spending, esp by lower-income consumers (e.g. core dollar store customer).
Out Friday, U. Mich. Sentiment (final) for July was 55.2, a slight improvement from the preliminary read of 54.4 and up nearly 12% from June, driven by broad-based improvements across income, education, wealth, age and political affiliation cohorts, though sentiment is down 10% from this time a year ago on concerns about the economy and persistent/cumulative inflation.
- Year-ahead inflation expectations eased from +4.6% in June to +4.2% in July.
- DoRCR INSIGHT: Weak sentiment hasn't kept consumers from spending and hasn't been correlated to Retail Sales, which increased 6.7% y/y in June on a headline basis and 10%+ on a core basis, supported by the strong labor market, wage growth, and stock/housing wealth.
SELECT ANALYST ACTIONS
Best Buy (BBY, $86.35) Jefferies downgrades from Buy to Hold and lowers its target from $89 to $85 in front of upcoming second quarter results near the end of the month, says consumer purchase intentions for Best Buy saw a clear downshift during the month of July and sees this as making the setup for the third quarter particularly tricky, given the tough comparison, also thinks there is risk to earnings growth from rising laptop prices from the shortage in memory chips.
Burlington (BURL, $367.82) Citi downgrades from Buy to Neutral and maintains its $380 target in front of upcoming 2Q26 (July) results, says the stock is up 25%+ YTD and approaching its price target and now believes risk/reward is no longer skewed to the upside.
e.l.f. Beauty (ELF, $87.84) Bernstein upgrades from Market Perform to Outperform and raises its target from $60 to $113 in front of 1Q27 (June) results after the close today, notes the recent launch of haircare products and says this is the biggest category expansion since Elf Skin in 2022, thinks e.l.f. could reach 0.9% share in haircare by 2029, which implies $200M of incremental annual sales, also says e.l.f. has a highly relevant operating model vis-a-vis today's consumer with fluency in social media, rapid innovation cycles, and a "viral-prone approach to new product development."
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.