Companies and Subjects discussed in this morning's report include: Williams-Sonoma's comps accelerate in the second quarter, Abercrombie beats expectations, though with mixed geographic and brand performance, Bath & Body Works also beats, but trends remain soft, Kohl's reports a mixed quarter...

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Wednesday, August 26, 2026 | Published Daily by ~11:30 AM ET
Upside from Williams-Sonoma, Abercrombie and BBWI and a Mixed Second Quarter from Kohl's...
THIS WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/24)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
Tuesday (8/25)
- Dick's Sporting Goods reports 2Q26, call 8:00 am, Street at comps/EPS of +4.0%/$3.76
- Citi Trends reports 2Q26, call 9:00 am, Street at comps up 10.5%, EPS of ($0.32)
- Consumer Confidence for August at 10:00 am, Street at 90.2 vs. prior 90.8
- New Home Sales for July at 10:00 am, Street at 612K SAAR vs. prior 628K
Wednesday (8/26)
- Personal Income/Spend for July at 8:30 am, St at +0.2%/+0.2% m/m, prior +0.3%/+0.2%
- Abercrombie & Fitch reports 2Q26, call 8:30 am, Street at comps up 0.8%, EPS of $1.99
- Bath & Body Works reports 2Q26, call 8:30 am, Street at comps/EPS of (3.9%)/$0.24
- Kohl's reports 2Q26, call 9:00 am, Street at comps down 0.6%, EPS of $0.58
- Williams-Sonoma reports 2Q26, call 10:00 am, Street at comps up 4.5%, EPS of $2.08
- Urban Outfitters reports 2Q27, call 5:00 pm, Street at comps up 5.8%, EPS of $1.72
Thursday (8/27)
- Dollar Tree reports 2Q26, call 8:00 am, Street at comps up 3.2%, EPS of $1.15
- Best Buy reports 2Q27 call 8:00 am, Street at comps up 1.3%, EPS of $1.39
- Jobless Claims for the week ended 8/22/26 at 8:30 am, Street at 210K vs. prior 206K
- Burlington reports 2Q26, call 8:30 am, Street at comps up 3.0%, EPS of $2.19
- Dollar General reports 2Q26, call 9:00 am, Street at comps up 2.6%, EPS of $2.01
- Build-A-Bear reports 2Q26, call 9:00 am, Street at sales/EPS of $120.8M/$0.65
- Ulta Beauty reports 2Q26, call 4:30 pm, Street at comps up 2.3%, EPS of $6.20
- Gap reports 2Q26, call 5:00 pm, Street at comps up 0.2%, EPS of $0.48
Friday (8/28)
- DoRCR publishes its proprietary Next Week's Calendar
- U. Mich. Sentiment for August (final) at 10:00 am, Street at 50.8 vs. prior 51.0
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is up 0.9% as of ~11:05 am vs. a slight decline in the S&P 500. Retail stocks are outperforming after better-than-expected second quarter results from Williams-Sonoma, Abercrombie & Fitch and Bath & Body Works.
- Stronger retail stocks include ANF, which is up 35% despite mixed regional and brand performance, also VNCE (up 6%, ANF sympathy), URBN (up 5% on ANF sympathy and in front of results this afternoon), DBGI (up 5%) and AEO (up 5%, ANF sympathy).
- Weaker retail stocks include DXLG, which is down 5%, also CHWY (down 4%), NXH (down 3%), NKE (down 2%, analyst downgrade) and AS (down 2%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
- Performance was strong across brands as comps increased 5.1% at Pottery Barn, +6.4% at West Elm, +7.6% at Williams Sonoma, and +3.5% at Pottery Barn Kids and Teen, while total revs grew 7% y/y to $1.96B vs. the Street's $1.93B estimate.
- Non-GAAP EPS ex tariff refunds grew 5% y/y to $2.10 vs. the Street's $2.08 and incorporated 160 bps of gross margin pressure on lower merch margins (230 bps), mostly from tariffs, partially offset by supply chain efficiencies (30 bps) and occupancy leverage (40 bps).
- Non-GAAP operating margin decreased 60 bps y/y to 17.3%.
- Inventories look good and were up only 1% y/y at the end of the quarter.
- Raised FY26 guidance now includes revs up 4.7%-7.2% from FY25's $7.81B and vs. a prior up 2.7%-6.7%, comps of +4.0%-6.5% vs. a prior +2%-6%, and an op margin of 17.8%-18.2% vs. 18.1% in FY25 and a prior 17.5%-18.1% and assumes no benefit from tariff refunds.
- DoRCR INSIGHT: Another solid report overall, speaks to many positives to the story, from compelling and differentiated merch to the model's strong earnings power and cash generation, and while tariffs remain a pressure point, WSM is effectively mitigating much of the impact.
- Comps were flat vs. the Street's +0.8% and incorporated a 1% increase in the Americas, a 4% decrease in EMEA, and a 13% increase in APAC, also a 4% increase at Abercrombie and a 3% decrease at Hollister, while total revs grew 5% y/y to $1.27B vs. the Street's $1.25B.
- Mgmt noted accelerating momentum in the Americas and improving trends in EMEA, where comps fell 11% in 1Q26, and credited "compelling product, marketing, and experiences."
- Excluding a $1.75 per share benefit from tariff refunds, EPS were $2.42 vs. an adjusted $2.32 in last year's second quarter and above the Street's $1.99 estimate and incorporated an operating margin of 12.0%, down from 13.9% in last year's second quarter.
- Inventories look good and were essentially flat y/y at the end of the quarter.
- For the year, EPS are now expected at $13.10-$13.60 vs. an adjusted $9.86 in FY25 and a prior $10.20-$11.00 and including an estimated $2.10 per share in tariff refund benefits.
- Also of note, 3Q26 guidance calls for 5%-6% growth in sales, implying slight acceleration, and full-year EPS guidance now assumes at least $500M of share repurchase.
- Guidance also assumes ongoing negative tariff impacts, tho a bit smaller than before.
- DoRCR INSIGHT: Not a terrible update, but not much to get excited about either with the overall business comping essentially flat, potential for continued weakness in EMEA, and ongoing operating margin pressures with the 190 bps decline following (130) bps in the first quarter.
- Total sales fell 2% y/y to $1.51B vs. the Street's $1.50B estimate and incorporated a 5% decline at US and Canada stores, to $1.13B, a 3% increase in Direct sales, to $275M, the first y/y growth in Direct since 2021, and 25% growth in International sales, to $108M.
- North American category performance included a mid-single-digit % decline in Body Care, a low-single-digit % decline in Home Fragrance, and flat Soaps & Sanitizers sales.
- Ex $0.31 of tariff refunds, adjusted EPS were $0.31 vs. $0.37 LY and the Street's $0.24 estimate and incorporate a 90 bps decline in gross margin rate.
- Inventories are lean and were down 10% y/y at the end of the second quarter.
- FY26 guidance now includes a 2.5%-4% decline in sales, which implies $7.05B at the mid-point, and now includes adjusted EPS of $2.60-$2.80 vs. $3.21 in FY25 and a prior $2.40-$2.65 and assumes a 2.5%-5% decline in sales in the third quarter.
- DoRCR INSIGHT: Another soft quarter with no major change in the sales trend -- the 2% decline follows a 3% decrease in the first quarter and (2%) in 4Q25 -- and continued margin pressures as management focuses on Implementing the new "Consumer First Formula," which is expected to "drive improved performance over time," including more meaningful benefits next year.
- Kohl's also said it is restarting its share repurchase program after a pause and plans to buy back $100M of stock this year under its existing $3B authorization.
- Total sales decreased 1% y/y to $3.32B vs. the Street's $3.32B estimate.
- EPS were $1.28 vs. an adjusted $0.56 last year and the Street's $0.58 estimate and included a $100M benefit to gross margin from tariff refunds -- likely not in the Street estimate.
- Inventories look fine/good and were down 3% y/y at the end of the quarter.
- For the year, guidance now calls for total sales and comparable sales to be down 1.5% to flat vs. a prior down 2% to flat and for adjusted EPS of $1.80-$2.40 vs. $1.62 last year and a prior $1.00-$1.60 range and including the benefit from tariff refunds in the second quarter.
- Adjusted operating margin, also including the tariff refunds, is now expected at 3.5%-4.0%.
- On the Call, mgmt said Kohl's Sephora biz "continued to face headwinds," sales down 4%.
- DoRCR INSIGHT: While the (0.9%) comp is the best quarterly comp in 4+ years, and Kohl's does appear to be making some overall progress improving the business, it's important to note the extreme degradation of Kohl's earnings power over the last several years and to consider the FY26 operating margin guidance in the context of the 9.1% level of five years ago.
Analyst Actions that could move retail stocks today:
- The TJX Companies (TJX, $139.48) Jefferies downgrades from Buy to Hold
- Nike (NKE, $39.48) Truist downgrades from Buy to Hold
- Dick's Sporting Goods (DKS, $124.31) is downgraded by several firms
OTHER DEVELOPMENTS
Somnigroup (SGI, $64.09) has rec'd all regulatory approvals for its previously announced $2.5B all-stock acquisition of Leggett & Platt (LEG, $9.32) and expects to close the deal as early as today.
Target will launch its new Target Beauty Studio concept -- which replaces Ulta Beauty at Target -- in 600+ of its ~2K stores and on Target.com on Thursday, 9/10/26, will carry an assortment of 1,600+ products from 90 prestige, emerging and global brands, more than 2/3 of which are new to Target, and will also have dedicated Beauty Advisors and exclusive Target Circle offers.
Old Navy is expanding its grab-and-go beauty concept, which includes items under its Old Navy Beauty Co. line and third-party brands like e.l.f., Neutrogena, Touchland and others, to ~1K stores by the end of September, up from an initial ~150 stores, while the company will continue testing a dedicated beauty shop-in-shop in 45 of the initial ~150 pilot stores.
UK-based PE firm Modella Capital could bid for Poundland as its owner, US-based Gordon Brothers, prepares to launch a sale process. That's acc'd to Sky News, which says Modella hasn't committed to making an offer but is viewed as a logical bidder following its purchase of Dealz, which is Poundland's "former sister chain" in Poland. Poundland has ~600 stores across the UK.
COMMERCIAL REAL ESTATE
Dick's Sporting Goods opened five new experiential House of Sport stores and eight new Field House stores in the second quarter and plans to open 14 House of Sport stores and 20 Field House stores this year, many of which will be conversions of legacy Dick's Sporting Goods stores.
Primark, which is part of the UK's AB Foods, will open its 47th US store on Tuesday, 9/8/26, 26K+ square feet, at Sugarloaf Mills in Lawrenceville, GA, part of the Atlanta market, will be the first Primark store in Georgia, and another GA store is planned for Augusta.
Wayfair (digital native) announced plans for a 10th store, 85K square feet on one level, at Marketplace at Altamonte in the Orlando market, expected to open in 2028, and said in its release it is seeing a strong halo effect to its online business when stores open, including in the Chicago market, where 50%+ of those visiting its Wilmette store were new to the Wayfair brand.
MANAGEMENT UPDATES
Kohl's Chief Marketing Officer since 2022 and company exec since 2017 Christie Raymond is leaving in September, and Kohl's has appointed Chief Digital Officer since 2025 and former JD Sports exec Arianne Parisi to the newly created Chief Customer Officer position, which includes oversight of marketing, brand and creative, loyalty, personalization, media and digital commerce.
Correction: When discussing the retirement of Vitamin Shoppe President Muriel Gonzalez here yesterday, we said she had been succeeded by VP, GMM since 2024, 7-year company exec, and former longtime Toys"R"Us buyer Jack Gayton, but Gayton was promoted to SVP, Merchandising, and has assumed Vitamin Shoppe's lead merchandising role, which had been held by Gonzalez.
MACRO/CONSUMER INSIGHT
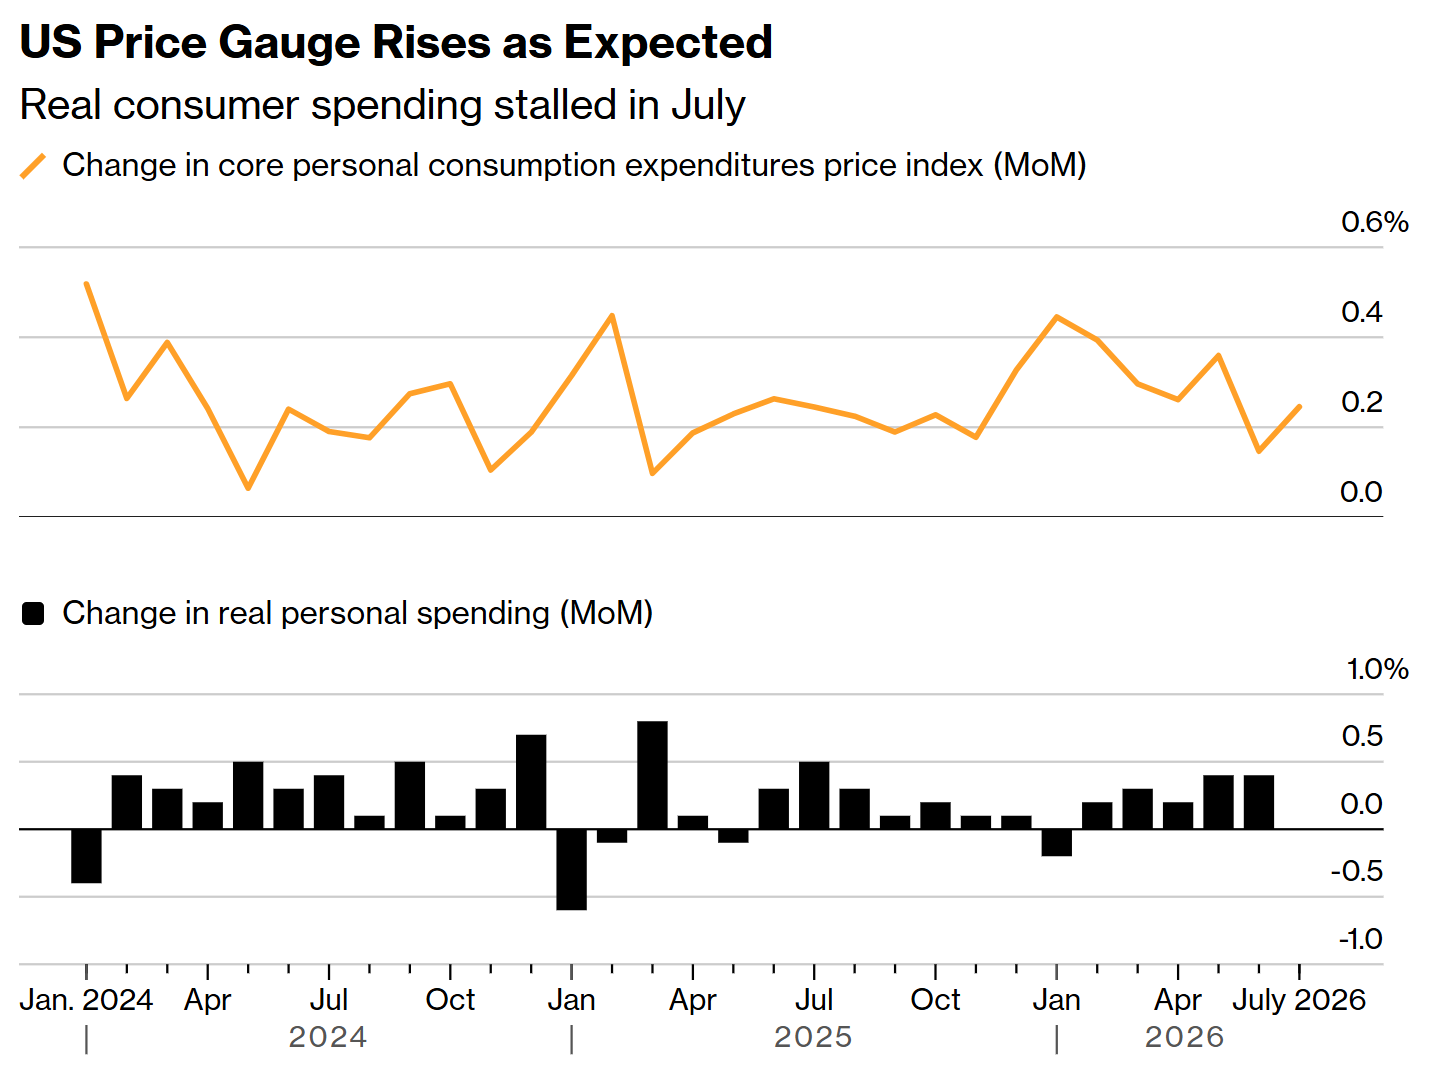
Out at 8:30 am, Personal Income for July was stronger than expected and increased +0.4% m/m vs. the Street's +0.2% estimate, while Personal Spending was right in line at +0.2% and a slight deceleration from an upwardly revised +0.4% m/m increase in June.
- The core PCE price index, which is the Fed's preferred inflation metric, rose 3.3% y/y, while inflation-adjusted consumer spending was essentially flat in July.
- Also of note, disposable income rose 0.4% m/m, most since January, and the savings rate rose to a four-month high of 3% but remained low vs. historical averages.
- DoRCR INSIGHT: Wages and income are growing at a solid clip, supported by the "low-hire, low-fire" labor market, and consumers continue to spend, though with increasing caution/concern and some pockets of weakness, e.g. the mass athletic footwear and apparel space.
Out yesterday, Consumer Confidence for August was slightly below expectations at 89.4 vs. the Street's 90.2 and a slight decline from a revised 90.2 in July as growing concerns about the price of gasoline more than offset an improvement in current views about the job market.
- DoRCR INSIGHT: Consumer anxiety has been elevated for some time now and doesn't seem to be having a big impact on spending decisions, but if we get another disappointing Nonfarm Payrolls report, fragile psychology could come more into play as it relates to Retail Sales.
Also out yesterday and acc'd to the U.S. Energy Information Administration, a gallon of regular Unleaded Gasoline cost $4.09 on average across the US for the week ended 8/24/26, up $0.04 from the prior week and up $0.94 per gallon from the same week last year.
- A gallon of diesel cost $5.65, up $0.20 on the week and up $1.94 from last year.
- DoRCR INSIGHT: Gas prices could come down quickly with a US/Iran peace deal and reopening of the Strait of Hormuz, but for now, the significant y/y increase is a meaningful headwind to discretionary spending, esp by lower-income consumers (e.g. core dollar store customer).
Source: BEA and Bloomberg (for chart)
SELECT ANALYST ACTIONS
Lululemon (LULU, $118.33) Goldman maintains a Neutral rating and lowers its target from $122 to $111 in front of 2Q26 (July) results next Thursday afternoon, says its proprietary trackers suggest ongoing pressure on demand, with slowing card spending and slipping brand sentiment and traffic, also says overall consumer metrics are deteriorating, promotions are elevated, and growth in China is moderating and making stabilization in the business more uncertain.
Nike (NKE, $39.48) Truist downgrades from Buy to Hold and lowers its target from $47 to $42, says the disappointing results and guidance from Dick's Sporting Goods are negative signals for Nike's turnaround progress and notes incremental softness in footwear, also says it needs more clarity around Nike's inventory clean-up process and innovation pipeline for 2027.
The TJX Companies (TJX, $139.48) Jefferies downgrades from Buy to Hold and lowers its target from $180 to $145 after last week's second quarter results, thinks the slowdown at Marmaxx, which comped up only 1%, goes beyond a merchandising miss and is more material, and believes it could take time for management to address and fix the root issues.
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.