Special Note: DoRCR is launching a monthly webinar for our subscribers, second Wednesday of each month at 2:00 pm ET, will cover macro/consumer + topical issues and include a chat-based Q&A. The first one is this Wednesday, 8/12/26, link to join here. You do not need to register in advance, and your participation will not be shown to other participants.

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Monday, August 10, 2026 | Published Daily by ~11:30 AM ET
GameStop May Retract eBay Offer, CTRN's Upside 2Q26, Our Latest Store Opening/Closing Analysis...
THIS WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/10)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
- Citi Trends at the virtual D.A. Davidson 2026 Small Cap Conference, time not specified
- Purple Innovation reports 2Q26, call 4:30 pm, Street at sales/EPS of $104.4M/($2.18)
Tuesday (8/11)
- On Holding reports 2Q26, call 8:00 am, Street at sales/EPS of CHF878.40M/CHF0.34
- Existing Home Sales for July at 10:00 am, Street at 4.05M SAAR vs. prior 4.09M
- Sally Beauty at the Canaccord Genuity Growth Conference at 10:00 am
Wednesday (8/12)
- Warby Parker doing meetings in Minneapolis/Chicago today/tomorrow, hosted by BTIG
- Consumer Price Index for July at 8:30 am, Street at +3.4% y/y vs. prior +3.5%
- Kontoor Brands reports 2Q26, call 8:30 am, Street at sales/EPS of $587.0M/$1.05
- DoRCR hosts its monthly Retail & Consumer webinar at 2:00 pm, link to join here, will cover macro/consumer + topical issues, including thoughts on the 2026 back-to-school season
- Grocery Outlet reports 2Q26, call 4:30 pm, Street at comps down 1.5%, EPS of $0.13
- Fossil reports 2Q26, call 5:00 pm, Street at sales/EPS of $199.3M/($0.36)
- Lulu's Fashion Lounge reports 2Q26, call 5:00 pm, no Street estimates
Thursday (8/13)
- Tapestry reports 4Q26, call 8:00 am, Street at sales/EPS of $1.87B/$1.28
- Birkenstock reports 3Q26, call 8:00 am, Street at sales/EPS of EUR715.0M/EUR0.76
- YETI reports 2Q26, call 8:00 am, Street at sales/EPS of $483.8M/$0.54
- Producer Price Index for July at 8:30 am, Street at +5.0% y/y vs. prior +5.5%
- Jobless Claims for the week ended 8/8/26 at 8:30 am, Street at 205K vs. prior 199K
- Wolverine Worldwide reports 2Q26, call 8:30 am, Street at sales/EPS of $500.7M/$0.38
- Yesway reports 2Q26, call 8:30 am, Street at comps up 2.0%, EPS of $0.47
Friday (8/14)
- DoRCR publishes its proprietary Next Week's Calendar
- Retail Sales for July at 8:30 am, Street at +0.1% m/m vs. prior +0.2%
- U. Mich. Sentiment for August (preliminary) at 10:00 am, Street at 53.5 vs. prior 55.2
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
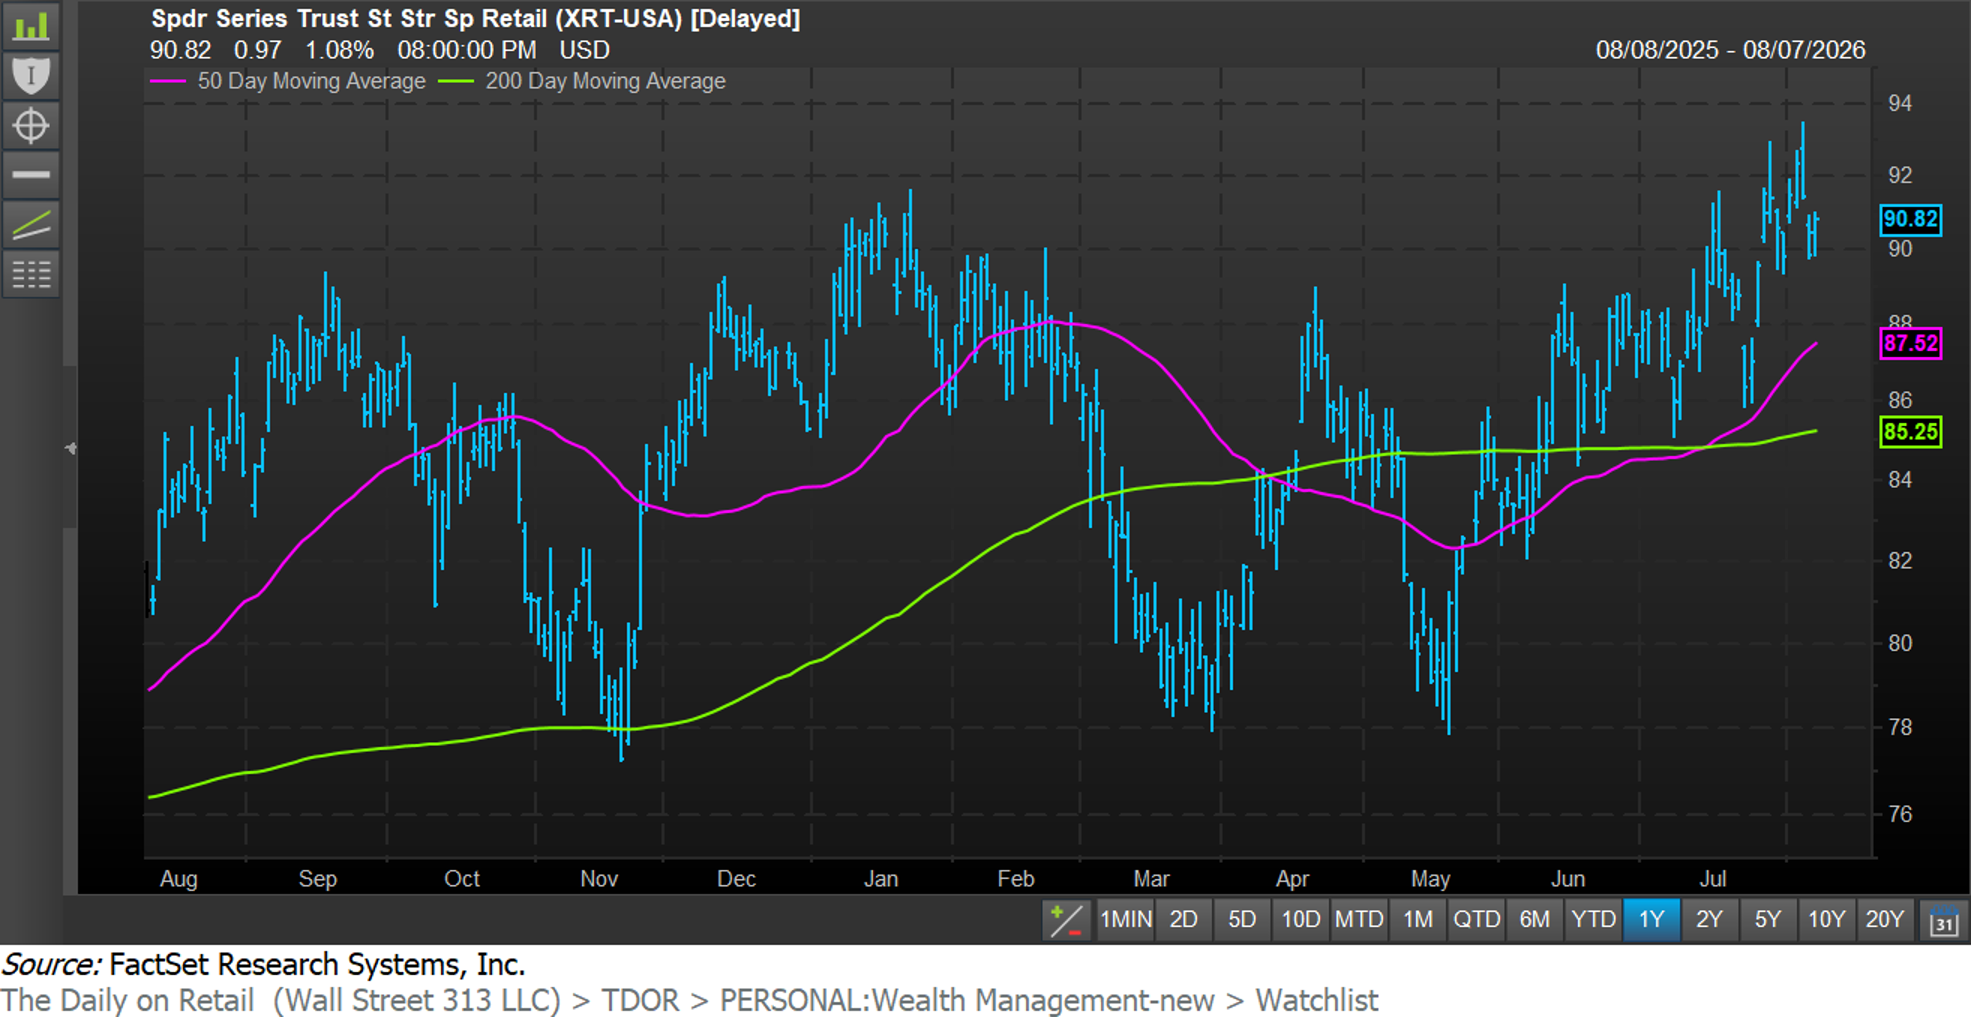
The S&P Retail ETF (XRT) is down 0.2% as of ~10:40 am vs. a slight gain in the S&P 500.
- Weaker retail stocks include ODD, UAA, DBGI, ETSY and FND, all down 5%+.
- Stronger retail stocks include CTRN, which is up 6% on upside 2Q26 sales, also ANF (up 4%), BOOT (up 4%), SPWH (up 3%) and GAP (up 3%).
Last Week: The XRT rose 1.2% vs. a 3.6% gain in the S&P 500, which hit fresh all-time highs during the week on optimism for a deal that would reopen the Strait of Hormuz and as a drop in Nonfarm Payrolls eased pressure on the Fed to raise interest rates. Retail stocks underperformed as a mixed 2Q26 earnings season continued with strong results from Wayfair, Ralph Lauren and e.l.f. Beauty, and weaker numbers from Capri, Bed Bath & Beyond and Under Armour. Other retail developments included GameStop's $1.4B debt-for-equity swap, the launch of a proxy fight at Ethan Allen by 5.0% shareholder Doug Bergeron, and Canada Goose's announced sale of its Baffin performance footwear brand to L.P. Royer. Also, Costco reported strong July sales, and Sycamore announced the sale -- for $350M per Bloomberg -- of Hot Topic to Spencer Spirit Holdings.
- Stronger retail stocks included FIGS, which reported a beat-and-raise 2Q and rose 33% on the week, ARHS (up 30%, upside results), NEGG (up 29%), W (up 26%) and BARK (up 24%).
- Weaker retail stocks included TDUP, which reported an in-line 2Q26 but cut guidance and fell 44% on the week, also GME (down 12%), NGVC (down 11%, downside results), CVS (down 8%, upside results, cautious commentary) and UAA (down 8%).
2026 Year-to-Date: The XRT is up 6.5% vs. a 13.3% gain in the S&P 500.
- Stronger retail stocks include LVLU, which is up 250%, also CURV (up 167%), TLYS (up 111%), DLTH (up 101%) and VSXY (up 82%).
- Weaker retail stocks include DBGI, which is down 97%, also NEGG (down 66%), ODD (down 65%), RENT (down 53%) and TDUP (down 50%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
GameStop (GME, $19.16) is considering retracting its $125 per share, or $55B+, offer to acquire eBay (EBAY, $111.98) and instead focusing on a potential partnership or JV between the two companies that would center around GameStop's ~1,600 US retail stores facilitating the buying and selling of high-margin categories like trading cards and collectibles acc'd to Bloomberg.
- GameStop, which has been building a stake in eBay and now holds a nearly 10% economic position, would look for representation on eBay's board as part of any deal.
- Game-Stop first made the $125 per share -- half cash and half stock -- in May and has seen its stock fall nearly 30% since then, while shares of EBAY have gained 8%.
- As of Friday's close, eBay's market value was $50B, and its value with debt was ~$54B, while GameStop's market value has fallen to $8.6B, though it also has $8.4B in cash.
- DoRCR INSIGHT: eBay firmly rejected GameStop's unsolicited offer shortly after it was made in May, and most investors agree that it is "neither credible nor attractive," but a tie-up of some sort does make some sense, including one that would leverage GameStop's store base to drive incremental sales in areas where both companies are growing and establishing leadership.
Citi Trends (CTRN, $72.69) reported upside preliminary 2Q26 (July) sales in front of a virtual appearance at D.A. Davidson's Small Cap Conference and said comps increased 10.5% vs. the Street's +7.5% estimate and increased 19.7% on a two-year basis after +23.8% on a two-year basis in the first quarter and were driven by factors including an improved assortment + value proposition.
- Total sales grew 11% to $211.6M and incorporated y/y increases in every merchandise category and steady growth in transaction and basket each month of the quarter.
- The two-year comp trend of +20% or so has continued into early back-to-school.
- Citi Trends will report full 2Q26 results on Tuesday, 8/25/26 before the open.
- DoRCR INSIGHT: The modest slowdown in the two-year comp is not surprising given the benefit of higher tax refunds in the first quarter -- Citi Trends' business has always been highly sensitive to tax refunds, bigger and smaller -- but the overall trend is very healthy and impressive and does appear to reflect better merchandising via better brands and an improved value proposition.
Analyst Actions that could move retail stocks today:
- Dick's Sporting Goods (DKS, $208.84) Wells Fargo upgrades from EW to Overweight
INDUSTRY INSIGHT
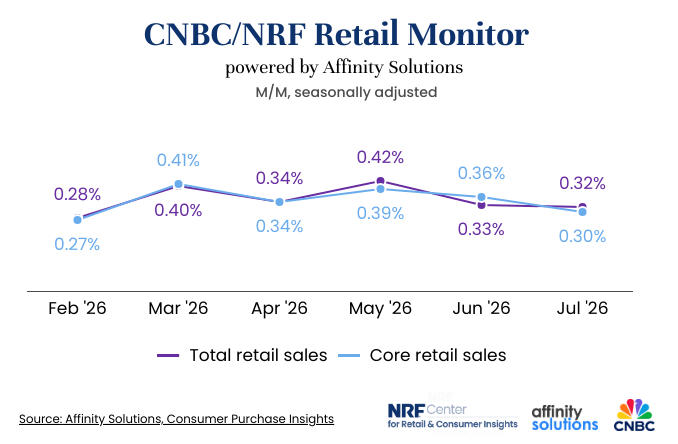
Core retail sales ex autos/gas/restaurants increased a solid 4.7% y/y in July and were negatively impacted by the shift -- into June -- of Amazon's four-day Prime Day and competing promotional events at Walmart, Target and others that contributed to a 10.1% y/y increase in core retail sales in June, while core retail sales increased 0.3% on a m/m basis in July after +0.4% in June.
- That's all per the latest CNBC/NRF Retail Monitor here, powered by Affinity Solutions.
- Sales were strongest in electronics/appliance, up 12.0% y/y, digital products (+12.0%), health and personal care (+10.1%), general merch (+8.3%) and clothing/accessories (+6.6%).
- Sales were weaker in sporting goods/hobby/music/books (down 3.0% y/y), building and garden supply (down 1.2%), furniture/furnishings (up 2.7%) and grocery/beverage (up 4.5%).
- Sales growth is being supported by low unemployment and "steady wage gains."
- July sales also got a boost from mid-summer sales and back-to-school promotions.
- On a YTD basis through the first seven months of 2026, core retail sales are up 6.5% y/y.
US online grocery sales grew by a very strong 22% y/y in July acc'd to Brick Meets Click, which notes monthly growth rates have been hovering in the 20%+ area for nearly two years and says the +22% in July was driven by a 2% increase in monthly users, a 15% increase in average order frequency, and a 4% increase in average order value during the month.
- Orders for delivery drove 60% of the y/y growth in online grocery sales in July and continue to get a lift from growth in membership programs like Walmart+ and Amazon Prime.
- Brick Meets Click also said in-store sales fell 2.6% y/y in July on top of (1.1%) last year.
OTHER DEVELOPMENTS
QVC Group has emerged from Ch 11 in less than four months, has reduced its total debt by $5B+, has access to a new $600M ABL facility backed by funds managed by Strategic Value Partners and Oaktree Capital, and has been approved for trading on the Nasdaq, ticker QVCG.
- With the exit, President and CEO since 2021 David Rawlinson has stepped down and been succeeded on an interim basis by former longtime QVC President and CEO Mike George.
- QVC's brands include QVC, HSN, Ballard Designs, Frontgate, Garnet Hill and Grandin Road.
Haverty Furniture's (HVT, $29.09) board has authorized an add'l up to $15M, or 3%+ of Friday's closing market cap of $460M, for stock buybacks and said purchases can be made from time to time in the open market or via privately negotiated transactions.
Academy Sports + Outdoors (320+ stores in 21 states) has launched same-day delivery in as fast as an hour with no markups via Instacart across 300+ stores in 21 states and says the initial focus is on back-to-school shopping, also fall sports, the hunting season and tailgating.
Partners Group (Switzerland, private equity) is in exclusive talks to acquire natural beauty and wellness brand Aroma-Zone (France) from Eurazeo (Paris, private equity), which will retain a significant minority stake following the transaction acc'd to Fashion Network.
 Livestream shopping/auction company Whatnot raised $545M at a $20B valuation -- nearly double its valuation from last fall --- in a Series G round led by Iconiq, Lightspeed and Avra, and plans to invest the new capital in platform innovation. The company also said it has already done more in GMV 2026 YTD than last year's $8B, that buyers have more than doubled over the past year, and that is has ~60% of the $22B+ US live-shopping market.
COMMERCIAL REAL ESTATE
We're not seeing anything too significant/noteworthy this morning...
MANAGEMENT UPDATES
QVC Group President and CEO since mid-2021 and former Nielsen IQ CEO and longtime Grainger exec David Rawlinson has stepped down and been succeeded on an interim basis by former longtime QVC President and CEO Mike George, who is also serving as Chair of the Board.
STORE OPENING/CLOSING ANALYSIS
Significant YTD Announcements
So far this year, US retailers have announced plans to open/close ~3,930/~3,480 stores by our analysis, which covers all sectors except auto retail and excludes opening/closing announcements that were made in 2025 and prior but will carry over into 2026 and beyond.
The numbers this time last week were ~3,920/~3,480, and this time last year we tracked ~3,495/~4,100 YTD announced openings/closings.
For all of 2025, we tracked ~5,525 announced store openings, down 20% from 2024, and ~4,820 announced store closings, down 45% from 2024.
Note that openings/closings are specific numbers that have been announced, not completed, and could extend over several years.
Also note we include select non-US retailers (e.g. ALDI, POP MART, Lululemon) in our totals and small numbers of openings/closings if it's a significant development (e.g. digitally-native brands opening their first stores, highlighted below with an asterisk*), that we don't count concessions, pop-ups, seasonal stores, pilots, JV/partner-operated stores, acquired stores, or conversions, and that our closing tally excludes closings that are part of an ongoing business plan.
Latest Store Opening Announcements: Digitally native Warby Parker reported 2Q26 results last week and reaffirmed plans to open 50 net new stores this year on a base of 323 stores, or 15% y/y growth in units, Bob's Discount Furniture reported 2Q26 results and reaffirmed plans to open 10 new stores this year, or ~10% unit growth, and a.k.a. Brands reported second quarter results and said it plans to open four more Princess Polly (digital native) stores this year and as many as 10 new Princess Polly stores in 2027 and noted leases have already been executed in Charlotte, NC, Boca Raton, FL, Nashville, Burlington, VT and Jacksonville, FL.
We previously had eight new Princess Polly stores and are adding six to our totals.
a.k.a. also said it sees potential for at least 100 Princess Polly stores in the US, up from 13 now.
Digitally native Wayfair announced plans to open a 95K sf store in the Pittsburgh market next year, at North Hills Village, 95K sf, will be the first store in PA and takes total announced Wayfair stores to nine, Arhaus reported a better-than-expected 2Q26 and reaffirmed plans to open 4-6 new showrooms this year, and digitally native FIGS reported an upside 2Q26 and reaffirmed plans to open four new "Community Hubs" this year, at Fashion Square in Scottsdale, AZ, Tysons Corner in VA, Valley Fair near San Jose, CA and Aventura Mall in Miami.
Johnnie-O (men's, women's and boys' apparel+) recently opened its 23rd store, at Plaza del Lago in suburban Chicago, has now opened seven stores so far this year, and plans to open three more before year-end, in Naples and Delray, FL, and in Austin, TX, digitally native The RealReal reported 2Q26 results last week and said it plans to open two more stores this year, in Boston and Los Angeles, and digitally native Revolve reported 2Q26 results and reaffirmed plans to open a third retail store, at Aventura Mall in Miami, will open in 4Q26.
And a few mentions:
- Spirit Halloween plans to open a record 1,575 seasonal stores in the US and Canada this year, starting in mid-August, but we do not include temporary stores in our totals.
- Sally Beauty reported results last week and said it plans to open 10 more Happy Beauty stores ahead of the holidays as part of an ongoing test -- also not included in our totals.
- Ralph Lauren reported a strong 1Q27 (June) last week and said it opened 22 owned and partner stores globally in the quarter, but since we don't know the breakdown and don't include partner stores, we will wait to get clarity before including any openings.
- Natural Grocers reported 3Q26 (June) results last week and said it now plans to open 6-7 new stores in its FY26 vs. a prior 6-8 new stores, but these stores were announced last year and included in our 2025 totals.
Latest Store Closing Announcements: There were no significant announcements last week.
- Dollar Gen (~450 on ~20,900 note)
- Casey's (400+ on 2,900+ note)
- Dollar Tree (~400 on 9,282)
- O'Reilly (225-235 net on 6,585 note)
- 7-Eleven NA (200+ on 13K+)
- ALDI USA (180+ on 2,600+ note)
- Five Below (~150 net on 1,921)
- TJX (146 net on 5,200+ globally)
- Yesway (130 on ~450)
- Academy Sports (~125 on 322 note)
- Burlington (115 net on 1,212)
- Ross Stores (110 on 1,900+)
- Kroger (105-120 on ~2,800)
- Goodwill (100+ on ~3,400)
- Whole Foods (100 on 550+)
- Sheetz (100 on 830+)
- Paymore (90+ on 100+)
- Tractor Supply (85-90 on 2,395 note)
- Ollie's Bargain Outlet (75 on 645)
- SKIMS* (73 on 27)
- Boot Barn (70 on 539)
- Citi Trends (~65 on 590+)
- Bath & Body Wks (60+ net on 2,500)
- CVS (~60 on ~9K note)
- Barnes & Noble (60 on 670)
- Tailored Brands (55+ on 1K+ note)
- Urban Outfitters (54 on 784 owned)
- Levi Strauss (50-60 net on 3,400+)
- Ulta Beauty (50-60 net on 1,591)
- Build-A-Bear (50+ net on 660+ note)
- Abercrombie (50 on 829 owned)
- Warby Parker* (50 net on 323)
- Perfumania (43 on 280+)
- Advance Auto (40-45 on 4,300+)
- Lululemon (40-45 net owned on 811)
- Crocs (40 on ~400 owned/operated)
- Aerie and OFFLINE (~40 on 330+)
- Fabletics* (40 on 120)
- Dick's House of Sport (32 on 35 note)
- Grocery Outlet (30-33 net on 570)
- Target (30+ on ~2K note)
- Trader Joe's (30+ on 600+)
- Vuori* (30 on ~150)
- Birkenstock Amer (30 net on ~15)
- Ernesta* (26 on 4)
- Nordstrom Rack (25+ on ~300)
- Fleet Feet + Marathon (~25 on 310+)
- Genesco (23 on 1,236)
- Dick's Field House (22 on 42 note)
- POP MART US (20+ on 60+)
- Walmart U.S. (~20 on 4,600+ note)
- Love's Travel Stops (20 on ~670)
- Williams-Sonoma (~20 on 512)
- Floor & Decor (20 on 270)
- Bob's Discount Furn (~20 on 209)
- Kendra Scott (20 on ~170 note)
- Consumer Cellular (20 on 100)
- HEYDUDE (~20 mostly outlets on 75)
- Cotopaxi* (20 on 20)
- Bu-cee's (17 announced on ~55)
- Home Depot (~15 on 2,359)
- Windsor (15 on ~350)
- Golf Galaxy (~15 on 113)
- IKEA US (~15 on 54)
- UNIQLO USA (14 on 78)
- a.k.a.'s Princess Polly* (14 on 13 US)
- Aritzia (12-13 mostly US on 144 total)
- Caleres (12 on ~820)
- Shoe Carnival/Station (11-15 on 426)
- The Buckle (11-13 net on 440)
- Advance Mega Hub (10-15 on 33)
- Garage (10-12 net on 300)
- Signet Jewelers (up to 10 on 2,582)
- Publix (~10 on 1,400+)
- La-Z-Boy (10 on 380 total N America)
- Cato (up to 10 on 1,070)
- Vivaia* (10 on 1)
- Lovesac (8 net on 278)
- Sukoshi (8 on 9 US)
- Salomon (7-10 on 2 US)
- Purple (7 on 55)
- BYLT* (7 on 15)
- Wayfair* (7 on 2 note)
- Haverty Furniture (6 net on 129)
- Big Y (6 on 77)
- RH (6 on 75)
- Zumiez (5 US on 716 total worldwide)
- Meijer (~5 on 500+)
- Boll & Branch* (5 on 15)
- Kurt Geiger London (5 on 5 US)
- Arhaus (4-6 on 107)
- U.S. Polo Assn. (4 on 1,200+)
- Food Lion (4 on 1,100+)
- Best Buy (4 net US on 1K+ in NA)
- Tilly's (4 on 224)
- Ocean State Job Lot (4 on 175)
- Vera Bradley Outlet (4 on 87)
- True Religion (4 on 57)
- Chair King (4 on 52)
- FIGS* (4 on 5)
- Ana Luisa* (4 on 2)
- Joybird* (3-4 on 16)
- Madewell (3 on ~150)
- Albertsons' Tom Thumb (3 on ~70)
- Brilliant Earth* (3 on 42)
- Suitsupply (3 US on ~40 US)
- Johnnie-O (3 on 23)
- COS US (3 on 12)
- Whole Foods Mkt Daily Shop (3 on 8)
- Brochu Walker (3 on 5)
- BRUNT Workwear (3 on 0)
- Bass Pro Shops (2 on 180+)
- Bassett Furniture (2 on 86)
- YETI (2 on 25+)
- FRAME (2 on 20+)
- The RealReal* (2 on 18)
- CardVault by Tom Brady (2 on 10)
- Yellow Rose Kendra Scott* (2 on 3)
- Amazon* Big Box (2 on 0)
- Cider* (2 on 0)
- J.Jill (1-5 net on 256)
- 7th Avenue* (1 on 20+)
- Thursday Boot Company* (1 on 4)
- Revolve* (1 on 2)
- Povision* (1 on 0)
- Addison Bay* (1 on 3)
- GameStop (700+ US of 2,300+ note)
- 7-Eleven NA (645 of 13K+)
- Francesca's (450+ of 450+)
- Family Dollar (350+ of 7,450+)
- Hibbett (~175 of ~980)
- Eddie Bauer US + Can (~175 of ~175)
- Signet Jewelers (~100 of 2,582)
- Value City Furniture (79 of 79)
- Dollar Tree (~75 of 9,282)
- Genesco (75 of 1,236)
- Tractor Supply's Petsense (75 of 207)
- West Marine (59 of 200+)
- Saks OFF 5TH (57 of 69)
- Amazon Fresh (57 of 57)
- Cato (up to 40 of 1,070)
- Grocery Outlet (36 of 570)
- CVS (~35 of ~9K note)
- Zumiez (26 of 716 total worldwide)
- American Eagle (20-25 AE of 805 AE)
- Abercrombie (20 of 829 owned)
- Williams-Sonoma (~20 of 512)
- Allbirds* US full-price (~20 of ~20)
- Urban Outfitters (19 of 784 owned)
- Shoe Carnival/Station (18-24 of 426)
- Saks Fifth Avenue full-line (18 of 33)
- Petco (15-20 net of 1,382)
- Caleres (15 of ~820)
- Fossil (15 of 199)
- Amazon Go (15 of 15)
- Albertsons (14 net of 2,200+)
- Ross Stores (10-15 of 1,900+)
- Amer. Signature Furniture (10 of 10)
- Tilly's (6 of 224)
- Sportsman's Warehouse (5 of ~150)
- Johnny Was (5 of 78)
- Neiman Marcus Last Call (5 of 5)
- Neiman Marcus full-line (4 of 36)
- Apple US retail (3 of ~270)
- Vince (3 net of 60)
- Nordstrom (2 of ~90 full-line)
MACRO/CONSUMER INSIGHT
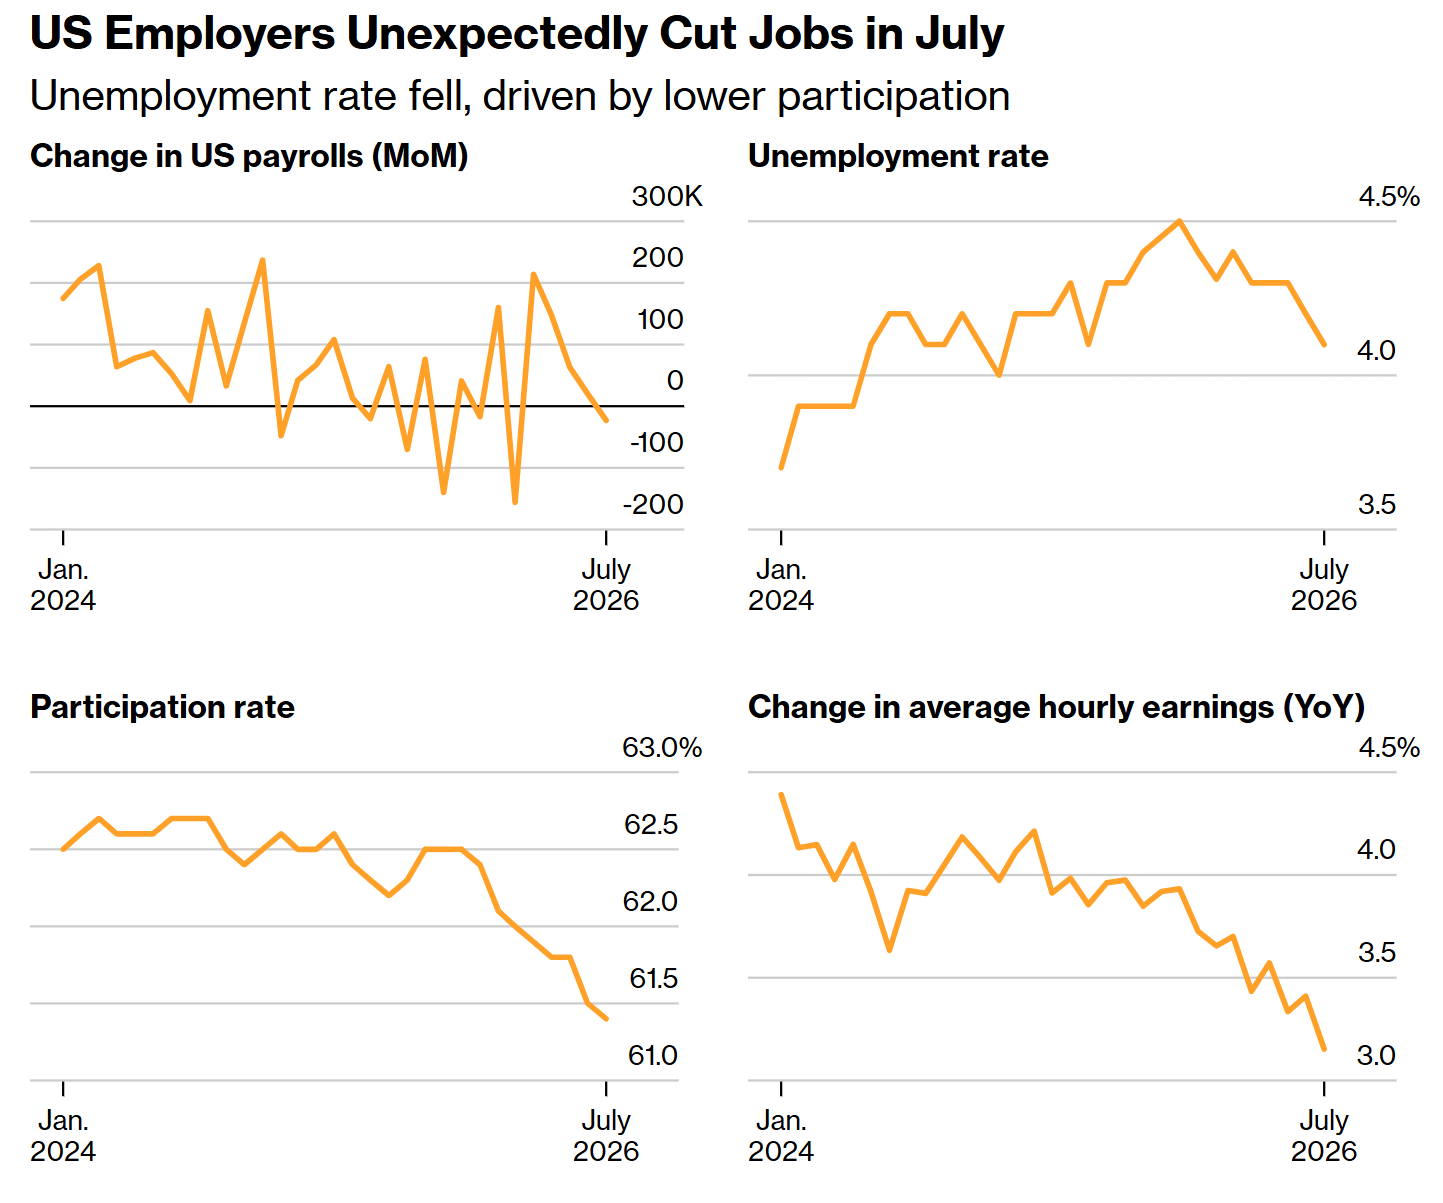
Out Friday, Nonfarm Payrolls for July were much weaker than expected and fell 23K vs. the Street's +95K estimate after a downwardly revised +20K in June, while Unemployment declined slightly, to 4.1%, and Avg Hourly Earnings grew 3.2% y/y vs. expectations of +3.5%.
- DoRCR INSIGHT: Probably best not to spin this -- it is worrisome -- but other labor market indicators including weekly Jobless Claims, JOLTS, even ADP to some extent, point to stability if not underlying strength, so it makes sense -- esp with all the revisions -- to give the Nonfarm data another month or two before drawing broad conclusions about a jobs + wage slowdown.
Out Thursday, Jobless Claims for the week ended 8/1/26 were lower than expected at 199K vs. the Street's 205K estimate and essentially unchanged from the prior week, while Continuing Claims, which are reported with a week's lag, increased 24K from the prior week, to 1.80M.
- DoRCR INSIGHT: The labor market slowed significantly last year but appears to be in recovery mode despite AI, geopolitical instability/uncertainty, the spike in fuel prices, etc., and this is good for consumer spending, though higher fuel prices do erode discretionary spending power.
Out Wednesday, ADP Employment for July was weaker than expected at +44K vs. the Street's +75K estimate and after a revised +95K in June, while pay for those staying with their jobs held steady at +4.4% y/y, and pay for job-changers increased 7.0%, biggest y/y increase since mid-2025.
- DoRCR INSIGHT: Not a terrible month, and this data series is more limited in scope than the government's Nonfarm Payrolls report, also Jobless Claims, which have been very low, and other indicators (e.g. JOLTS) showing a solid overall labor market.
Source: BLS and Bloomberg (for chart)
SELECT ANALYST ACTIONS
Dick's Sporting Goods (DKS, $208.84) Wells Fargo upgrades from Equal Weight to Overweight and raises its target from $220 to $240 in front of 2Q26 (July) results in two week, thinks Foot Locker is a multi-year margin upside opportunity, driven by better allocation and merchandising, and views the core Dick's business as the best way in the space to play an eventual Nike product turnaround.
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.