Companies and Subjects discussed in this morning's report include: Upside and share gains from the dollar stores, Best Buy reports its best quarterly comp since the pandemic, Burlington delivers a respectable but underwhelming 2Q26, Somnigroup closes acquisition of Leggett & Platt, ABG and Vince acquire OVO...

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Thursday, August 27, 2026 | Published Daily by ~11:30 AM ET
Dollar Store and Best Buy Upside, Burlington's Okay Quarter, ABG and Vince Acquire OVO...
THIS WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/24)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
Tuesday (8/25)
- Dick's Sporting Goods reports 2Q26, call 8:00 am, Street at comps/EPS of +4.0%/$3.76
- Citi Trends reports 2Q26, call 9:00 am, Street at comps up 10.5%, EPS of ($0.32)
- Consumer Confidence for August at 10:00 am, Street at 90.2 vs. prior 90.8
- New Home Sales for July at 10:00 am, Street at 612K SAAR vs. prior 628K
Wednesday (8/26)
- Personal Income/Spend for July at 8:30 am, St at +0.2%/+0.2% m/m, prior +0.3%/+0.2%
- Abercrombie & Fitch reports 2Q26, call 8:30 am, Street at comps up 0.8%, EPS of $1.99
- Bath & Body Works reports 2Q26, call 8:30 am, Street at comps/EPS of (3.9%)/$0.24
- Kohl's reports 2Q26, call 9:00 am, Street at comps down 0.6%, EPS of $0.58
- Williams-Sonoma reports 2Q26, call 10:00 am, Street at comps up 4.5%, EPS of $2.08
- Urban Outfitters reports 2Q27, call 5:00 pm, Street at comps up 5.8%, EPS of $1.72
Thursday (8/27)
- Dollar Tree reports 2Q26, call 8:00 am, Street at comps up 3.2%, EPS of $1.15
- Best Buy reports 2Q27 call 8:00 am, Street at comps up 1.3%, EPS of $1.39
- Jobless Claims for the week ended 8/22/26 at 8:30 am, Street at 210K vs. prior 206K
- Burlington reports 2Q26, call 8:30 am, Street at comps up 3.0%, EPS of $2.19
- Dollar General reports 2Q26, call 9:00 am, Street at comps up 2.6%, EPS of $2.01
- Build-A-Bear reports 2Q26, call 9:00 am, Street at sales/EPS of $120.8M/$0.65
- Ulta Beauty reports 2Q26, call 4:30 pm, Street at comps up 2.3%, EPS of $6.20
- Gap reports 2Q26, call 5:00 pm, Street at comps up 0.2%, EPS of $0.48
Friday (8/28)
- DoRCR publishes its proprietary Next Week's Calendar
- U. Mich. Sentiment for August (final) at 10:00 am, Street at 50.8 vs. prior 51.0
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is down 1.4% as of ~11:00 am vs. a 0.7% gain in the S&P 500.
- Weaker retail stocks: BBW, down 23% after a mixed 2Q26 and guidance cut, DXLG (down 6%), MNSO (down 5%), BBY (down 5% despite a beat-and-raise quarter) and GO (down 5%).
- Stronger retail stocks include VNCE, which is acquiring streetwear brand OVO's operating biz and is up 17%, also DG (up 5%), REF (up 3%), WSM (up 3%) and LUXE (up 2%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
- Comps increased 3.5% vs. the Street's +2.6% and were driven by a 2.0% increase in traffic and a 1.5% increase in ticket, also growth in consumables, seasonal, home products and apparel, while total sales grew 5% y/y to $11.29B on the comp and net new store growth.
- Ex $0.25 in net tariff refunds, EPS were $2.23 vs. $1.86 LY and the Street's $2.01, driven by the upside comps and ~45 bps of gross margin expansion on a lower LIFO provision and lower distribution costs, partially offset by increased markdowns and higher transport costs.
- Inventories look very good and were down 3% y/y on an average store basis.
- DG opened 125 new stores in the US and one in Mexico in the quarter, has 21K+, and also remodeled ~2K stores through Project Renovate and ~2,250 through Project Elevate.
- Full-year guidance now includes comps of +2.5%-2.9% and total sales growth of +4.0%-4.3% from FY25's $42.72B, with both ranges slightly higher than before, and EPS of $7.80-$8.20 vs. $6.85 last year and a prior $7.20-$7.45 and including $0.25 in net tariff refunds.
- Full-year guidance also assumes $700M in stock repurchase.
- DoRCR INSIGHT: The +3.5% comp is a modest acceleration from the first quarter's +2.0% despite a slightly tougher comparison and suggests DG is holding onto its core customer despite the recent spike in gas prices while also gaining new "trade-down" customers as the company executes well, leverages its powerful value proposition, and gains market share.
- The +3.7% is on top of +6.5% last year and above the Street's +3.2% estimate and was driven by a 3.3% increase in average ticket as Dollar Tree continues to expand its multi-price store base, while traffic increased 0.4%, and total sales grew 7% y/y to $4.89B.
- Dollar Tree converted or added ~710 stores to the multi-price format, now has ~6,600.
- Excluding a $1.31 per share net tariff refund benefit, EPS were $1.39 vs. an adjusted $0.77 last year and the Street's $1.15 and incorporated 170 bps of gross margin improvement on lower tariff rates vs. last year, favorable inventory shrink, and occupancy leverage.
- Inventories look very good and were down 9% y/y at the end of the quarter.
- FY26 guidance includes comps of +3%-4%, total sales from continuing ops of $20.5B-$20.7B vs. $19.41B in FY25, both unchanged from before, and adjusted EPS of $7.70-$8.05 vs. $5.75 in FY25 and a prior $6.70-$7.10 and including $0.60 from net tariff refund impacts.
- Guidance assumes +3%-4% comps in the third quarter, implies continued momentum.
- Dollar Tree is still planning ~400 new store openings and ~75 closings for the year, netting out to ~325 stores, or 3.5% y/y growth on a base of ~9,300 to start the year.
- DoRCR INSIGHT: The continued soft traffic trend is getting some attention and is likely the primary reason DLTR shares are down this morning, but the overall business is strong and growing as Dollar Tree continues to evolve the model toward multiple price points while still offering extreme value amid heightened value-consciousness by consumers.
- Comps increased 2% on top of +5% last year and after +6% on flat in the first quarter, or a slight acceleration on a two-year basis, while total sales grew 11% to $3.00B.
- Ex tariff refunds and certain expenses related to bankruptcy acquired store leases, adjusted EPS grew nearly 40% y/y to $2.37 vs. the Street's $2.19 estimate and incorporated merchandise margin expansion and 100 bps of adjusted op margin improvement.
- Inventories look high relative to sales and were up 11% on a comp store basis.
- For the year, comps are expected to increase 3%-4%, including a 1%-3% increase in the third quarter, while total sales are expected to grow 10%-11% from FY25's $11.55B, and adjusted EPS are now expected at $11.77-$11.97 vs. $10.17 last year and a prior $11.45-$11.80.
- Earnings guidance assumes $55M of tariff refunds are fully reinvested in price reductions to further reinforce Burlington's value proposition and make its "deals even better."
- Burlington still plans to open 115 net new stores this year, implies 9%-10% y/y growth.
- DoRCR INSIGHT: Again, the +2% comp is a little underwhelming, but comps did show slight acceleration on a two-year basis, and reinvesting tariff refunds in price to reinforce value to the consumer makes a lot of sense and should contribute to solid traffic trends through 2H26.
- The +4.1% was on top of +1.4% last year and well above the Street's +1.3% estimate and included a 4.5% increase in domestic comps, a 5.1% in domestic online comps, and a 1.8% decrease in international comps, while total revs grew 4% y/y to $9.78B.
- Sales grew in nearly all major product categories, especially computing, home theater and emerging categories like AI glasses and trading cards, partially offset by a decline in traditional gaming, while Best Buy Ads and Marketplace also saw good growth.
- Also of note, Best Buy was cycling the very successful launch of the Switch 2 in 2Q27.
- Adjusted EPS were $1.47 vs. $1.28 last year and the Street's $1.39 estimate and incorporated $34M of domestic gross margin rate benefit from IEEPA tariff refunds.
- Inventories look fine relative to sales and were up 8% y/y at the end of the quarter.
- FY27 guidance includes comps of +1.9%-3.0% vs. a prior (1%)-1%, revs of $42.3B-$42.8B vs. $41.69B in FY26, an adjusted op margin of 4.4%-4.5% vs. 4.3% in FY26, and adjusted EPS of $6.70-$6.90 vs. $6.43 last year and a prior $6.30-$6.60.
- Full-year guidance also assumes a 1%-3% increase in comps in the third quarter.
- On the Call, mgmt said new consumer technology products including AI glasses, trading cards, collectibles and health rings drove ~1 ppt of the +4.1% comp in the quarter.
- DoRCR INSIGHT: In the release, incoming CEO Jason Bonfig noted "a healthy demand environment for our category" and also attributed some of the trend acceleration to strategic actions; the more positive "body language" and confidence in initiatives is very encouraging, especially with the ongoing drag of high interest rates on bigger-ticket purchases.
- Total sales grew 10% to $1.66B, a record for any second quarter, and incorporated 8% growth in Retail segment sales, to $1.39B, and 19% growth in Wholesale sales, to $90.8M, also continued strong performance at Nuuly, where revs grew 29% to $178.6M.
- Retail comps increased 6.2%, driven by HSD% digital growth and +MSD% store comps, and comps increased 10.0% at FP, 8.4% at Urban Outfitters, and 3.0% at Anthropologie.
- Adjusted EPS excluding tariff refunds were $1.72 vs. $1.58 LY and the Street's $1.72.
- Earnings growth incorporated the strong sales and a slight improvement in underlying gross margin on leverage of store occupancy and delivery expense, partially offset by increased Retail markdowns at Anthropologie, tariffs, and inbound freight fuel surcharges.
- Retail comp inventory was up 8% and reflected the higher sales and receipt timing.
- Other Callouts: Nuuly's average active subs grew 30% y/y after +33% in the first quarter.
- DoRCR INSIGHT: Another strong quarter as the legacy Urban Outfitters business continues its strong turnaround, as other banners generate good growth on top of tough comparisons, and as Nuuly continues to look like one of the best businesses in the apparel rental space.
Analyst Actions that could move retail stocks today:
- Abercrombie & Fitch (ANF, $147.75) Citi downgrades from Buy to Neutral
OTHER DEVELOPMENTS
Somnigroup (SGI, $62.83) closed its previously announced acquisition of Leggett & Plan in a deal valued at ~$2.3B, including debt, and LEG holders rec'd 0.1455 SGI shares for each of their LEG shares and now own ~9% of the newly-combined company on a fully-diluted basis.
- Somnigroup also raised its annual run-rate synergy target for the acquisition from $50M to $75M and said its net leverage ratio at deal closing was ~2.8x adjusted EBITDA.
- The combined company now has 170+ manufacturing facilities in 37 countries.
- Somnigroup also announced plans to host a business update call on 9/2/26.
Casey's (CASY, $807.12) stock will be added to the Bloomberg 500 Index prior to the open on Thursday, 9/10/26 as part of the index's September reconstitution.
Build-A-Bear (BBW, $39.10) had a mixed 2Q26 (July) with light revs down 7% y/y to $115.3M and down y/y but better-than-expected adjusted EBITDA of $15.2M vs. $18.8M in 2Q25 and the Street's $15.0M estimate, and management lowered full-year revenue guidance from $530M-$550M to $500M-$525M and said some wholesale deals are taking longer than expected to realize.
- Mgmt also lowered full-year earnings guidance, even with $13M of tariff refunds.
Bath & Body Works CEO Daniel Heaf said on the 2Q26 (July) call yesterday the company's sales on Amazon tripled in the quarter when compared to 1Q26 and noted the "channel is attracting a higher mix of new-to-brand consumers who skew younger and more affluent while delivering a higher AUR than our own channels" and is not cannibalizing sales to Bath & Body Works stores.
Abercrombie CEO Fran Horowitz said during the 2Q26 (July) call yesterday Hollister's collaboration with Target, which is the brand's "first meaningful wholesale and category expansion in the U.S.," is performing very well vs. internal expectations and "added nicely to top-line growth."
 ABG has acquired a majority stake in the IP of OVO, a Toronto-based premium lifestyle brand co-founded by Drake, who has retained a significant ownership stake, while Vince Holding has acquired OVO's operating business and will oversee design, product development, merchandising, 12 flagship stores and e-commerce. Transaction terms were not disclosed by ABG or Vince.
COMMERCIAL REAL ESTATE
Article, a Vancouver-based DTC furniture brand, recently opened its first US store, ~8K sf, in San Francisco's Design District, and plans to open a second US store in Bellevue, WA in September.
N.Cat, a South Korean fashion accessories brand with a franchise model, has opened its first US store, at the Del Amo Fashion Center mall in Torrance, CA, and is planning to open a second US store at Brea Mall in Brea, CA in September, both part of a planned US store growth push.
Kroger has broken ground for two new stores in the Detroit market, a 120K+ store at the corner of Ford Rd and Mercury Dr in Dearborn, June 2027 open date, and a 100K+ store on the corner of Springvale Dr and Haggerty Rd in Commerce Township, expected to open in May 2027.
MANAGEMENT UPDATES
Build-A-Bear Chief Growth Officer since May 2026, Chief Revenue Officer for the prior ~1 year and former Melissa & Doug Chief Commercial Officer and longtime Hasbro exec David Henderson has been let go, without cause, as disclosed in an 8-K filed this morning.
MACRO/CONSUMER INSIGHT
Out at 8:30 am, Jobless Claims for the week ended 8/22/26 were lower than expected at 203K vs. the Street's 210K estimate and down 4K from a revised 207K the prior week, while Continuing Claims, which are reported with a week's lag, decreased by 18K, to 1.78M.
- DoRCR INSIGHT: Reassuring to see yet another low Jobless Claims number after the weak Nonfarm Payrolls for July report -- down 23K -- supports the "low-hire, low-fire" narrative around the labor mkt, and with Unemployment at 4.1%, is positive for consumer spending.
Out yesterday, Personal Income for July was stronger than expected and increased +0.4% m/m vs. the Street's +0.2% estimate, while Personal Spending was right in line at +0.2% and a slight deceleration from an upwardly revised +0.4% m/m increase in June.
- The core PCE price index, which is the Fed's preferred inflation metric, rose 3.3% y/y, while inflation-adjusted consumer spending was essentially flat in July.
- Also of note, disposable income rose 0.4% m/m, most since January, and the savings rate rose to a four-month high of 3% but remained low vs. historical averages.
- DoRCR INSIGHT: Wages and income are growing at a solid clip, supported by the "low-hire, low-fire" labor market, and consumers continue to spend, though with increasing caution/concern and some pockets of weakness, e.g. the mass athletic footwear and apparel space.
Out Tuesday, Consumer Confidence for August was slightly below expectations at 89.4 vs. the Street's 90.2 and a slight decline from a revised 90.2 in July as growing concerns about the price of gasoline more than offset an improvement in current views about the job market.
- DoRCR INSIGHT: Consumer anxiety has been elevated for some time now and doesn't seem to be having a big impact on spending decisions, but if we get another disappointing Nonfarm Payrolls report, fragile psychology could come more into play as it relates to Retail Sales.
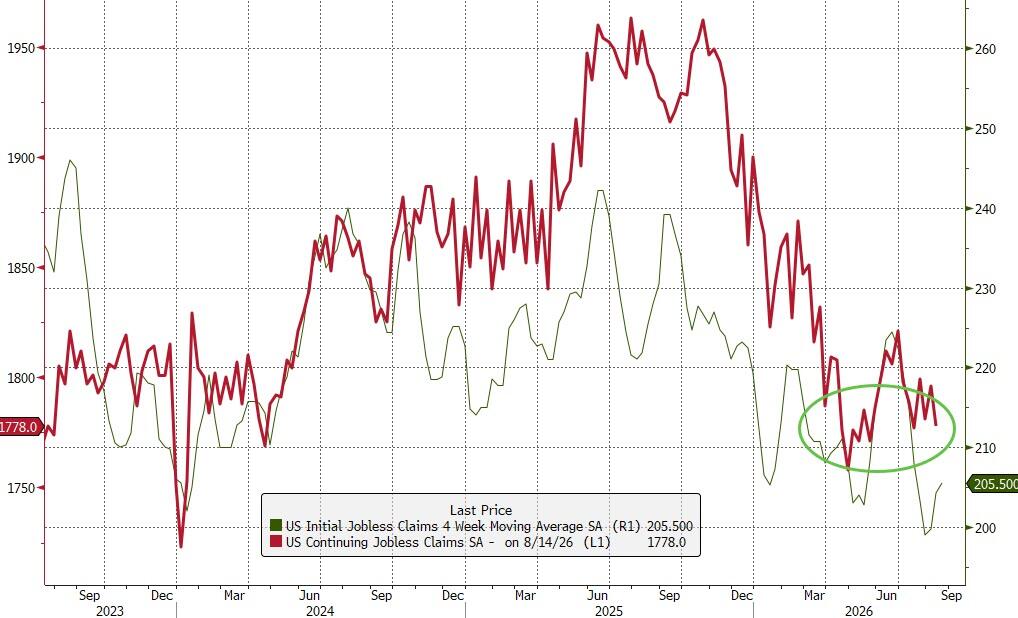
Source: Census Bureau, Bloomberg and ZeroHedge (for chart)
SELECT ANALYST ACTIONS
Abercrombie & Fitch (ANF, $147.75) Citi downgrades from Buy to Neutral but raises its target from $135 to $156 after yesterday's 2Q26 (July) results, makes positive comments about the quarter but thinks risk/reward in the stock is now balanced following the 30%+ spike.
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.