Companies and Subjects discussed in this morning's report include: WSJ is positive on US luxury, cautious on home improvement, store opening announcements still running a bit ahead of closings, retail stock underperformance, US footwear industry shows slight dollar growth, SHEIN targeting $25B valuation in IPO...

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Monday, August 17, 2026 | Published Daily by ~11:30 AM ET
WSJ Is Positive on US Luxury, Cautious on Home Improvement, Latest Store Openings/Closings...
THIS WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/17)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
Tuesday (8/18)
- Amer Sports reports 2Q26, call 8:00 am, Street at sales/EPS of $1.54B/$0.11
- Housing Starts for July at 8:30 am, Street at (6.6%) m/m vs. prior +19.0%
- Home Depot reports 2Q26, call 9:00 am, Street at comps up 0.9%, EPS of $4.73
- Pending Home Sales for July at 10:00 am, Street at +0.2% m/m vs. prior (5.4%)
- La-Z-Boy reports 1Q27 after the close, Street at sales/EPS of $501.4M/$0.49
Wednesday (8/19)
- Revolve meeting with investors in San Francisco, hosted by BTIG
- Target reports 2Q26, call 8:00 am, Street at comps up 2.4%, EPS of $2.35
- La-Z-Boy 1Q27 call at 8:30 am
- Lowe's reports 2Q26, call 9:00 am, Street at comps up 0.5%, EPS of $4.22
- TJX reports 2Q27, call 11:00 am, Street at comps up 3.4%, EPS of $1.19
Thursday (8/20)
- Walmart reports 2Q27, call 8:00 am, Street at comps up 3.8%, EPS of $0.74
- Advance Auto Parts reports 2Q26, call 8:00 am, Street at comps up 1.4%, EPS of $0.81
- Jobless Claims for the week ended 8/15/26 at 8:30 am, Street at 211K vs. prior 209K
- Ross Stores reports 2Q26, call 4:15 pm, Street at comps up 7.5%, EPS of $1.94
Friday (8/21)
- DoRCR publishes its proprietary Next Week's Calendar
- BJ's Wholesale reports 2Q26, call 8:00 am, Street at comps up 2.6%, EPS of $1.17
- The Buckle reports 2Q26, call 10:00 am, actual comps up 2.1%, EPS expected at $0.81
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
DoRCR's RETAIL & CONSUMER WEBINAR
If you weren't able to tune into our inaugural monthly Retail & Consumer Zoom webinar last Wednesday and would like to watch the recording, just click here to view it online, no username or password required. It's ~35 minutes and covers our thoughts on the current macro/consumer backdrop and the 2026 back-to-school season. Our next webinar will be Wednesday, 9/9/26, the second Wednesday of the month, at 2:00 pm. Feedback and suggestions are welcome!
TODAY'S EARLY TRADING
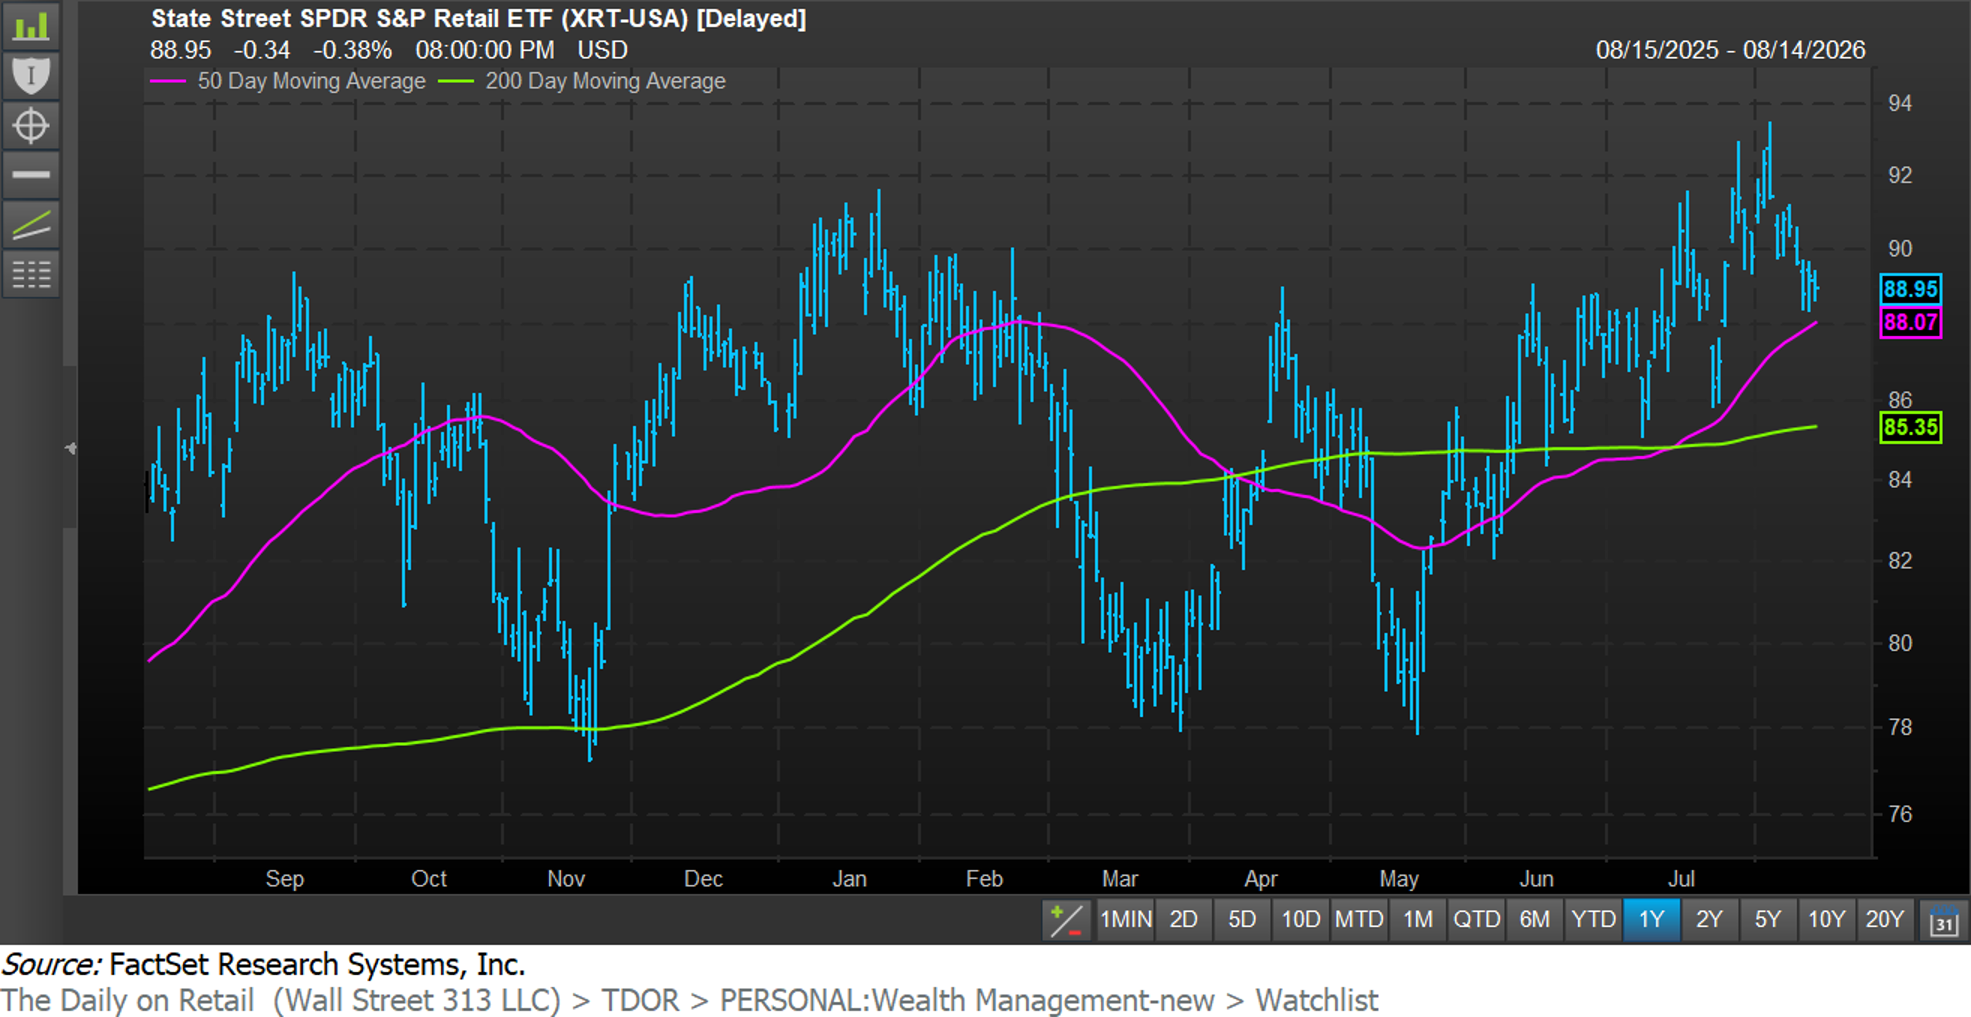
The S&P Retail ETF (XRT) is down 0.7% as of ~10:20 am vs. a slight decline in the S&P 500. Retail stocks are underperforming after a tough week and in front of second quarter results for bellwethers Home Depot and Lowe's, Walmart and Target, and TJX and Ross amid concerns about Friday's Retail Sales for July report and the recent Nonfarm Payrolls for July report.
- Weaker retail stocks include PLCE, MNSO, ODD, WWW and PRPL, all down 5%-10%.
- Stronger retail stocks include DDS, REF, ELF and AZO, all up 2%-4%, also WRBY, which is up 2% after Co-Founder and Co-CEO Neil Blumenthal discloses a 200K stock purchase.
Last Week: The XRT fell 2.1% vs. a 0.4% gain in the S&P 500, which hit new all-time highs Thursday after key inflation reports showed meaningful y/y easing in July and pushed expectations for the next Fed rate hike beyond the September FOMC meeting. Retail stocks underperformed as a mixed second quarter earnings season continued and as Retail Sales slowed in July and consumer confidence deteriorated in the early part of August. Other retail developments included a Bloomberg report saying GameStop may retract its $55B+ buyout offer for eBay and focus instead on a potential partnership or JV, QVC's emergence from Ch 11 after less than four months, and Whatnot's $545M funding round at a $20B valuation. Also, there were reports SHEIN's IPO bankers are pitching a sub-$30B valuation, and Samsonite said it will buy 85% of BEIS (luggage) for $178.5M in cash.
- Weaker retail stocks: PRPL, which reported a weak 2Q26 and cut guidance and fell 29% on the week, TPR (down 21%, good Q, but Coach is slowing), CURV (down 16%), YETI (down 15%, beat/raise 2Q26 but flagged drinkware softness) and SFIX (down 15%).
- Stronger retail stocks included YSWY, which reported an upside 2Q26 and raised earnings guidance and rose 16% on the week, also GO (up 12%, turnaround progress), WWW (up 11%, beat/raise 2Q26), KTB (up 10%, good results) and NEGG (up 9%).
2026 Year-to-Date: The XRT is up 4.3% vs. a 13.7% gain in the S&P 500.
- Stronger retail stocks include LVLU, which is up 212%, also CURV (up 125%), TLYS (up 101%), DLTH (up 94%) and CTRN (up 78%).
- Weaker retail stocks include DBGI, which is down 97%, also ODD (down 67%), NEGG (down 63%), PRPL (down 60%) and RENT (down 55%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
We're not seeing anything market moving (retail-wise) this morning...
INDUSTRY INSIGHT
The WSJ's Heard on the Street column is positive on American luxury brands, Ralph Lauren and Coach (Tapestry) in particular and notes shares of RL are trading at a slight valuation premium (of ~3%) to LVMH (MC-PAR) for the first time in more than 10 years, back when Louis Vuitton was going through a tough stretch after consumers moved away from logoed designs.
- The Journal thinks US luxury brands are doing a better job "reading the (current) market correctly" and have a better feel for what today's luxury consumer can afford, while the big European luxury houses need to "cut prices if they want to win back shoppers."
- Ralph Lauren's constant-currency sales grew 13% y/y in its June quarter and have grown by 10% or more for the last seven quarters despite a "stagnant luxury market."
- Coach grew constant-currency sales by 14% in TPR's June quarter, and mgmt said most of the growth is being driven by younger customers buying their first luxury handbag.
- Middle-income consumers still want to buy luxury goods, but the European brands have priced them out, and they can no longer shop Louis Vuitton, Gucci, etc.
- Some of those who still aspire to European luxury are buying secondhand via resale platforms like The RealReal, which grew sales by 17% y/y in its most recent quarter.
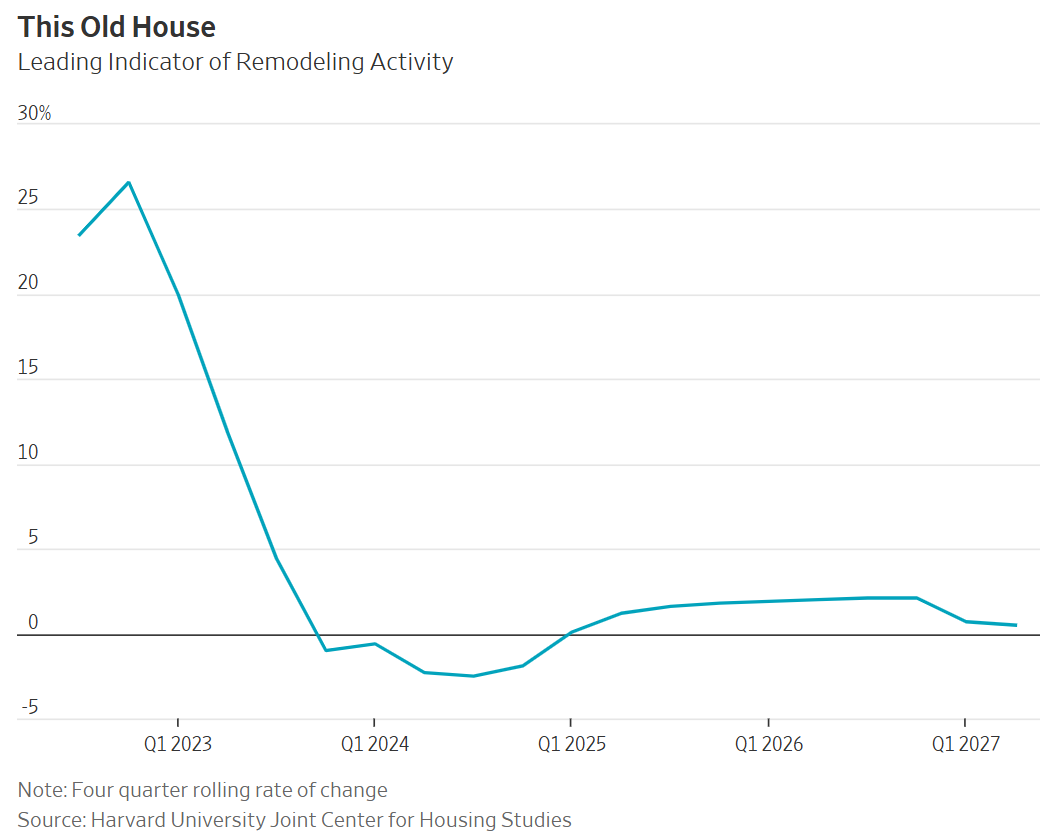
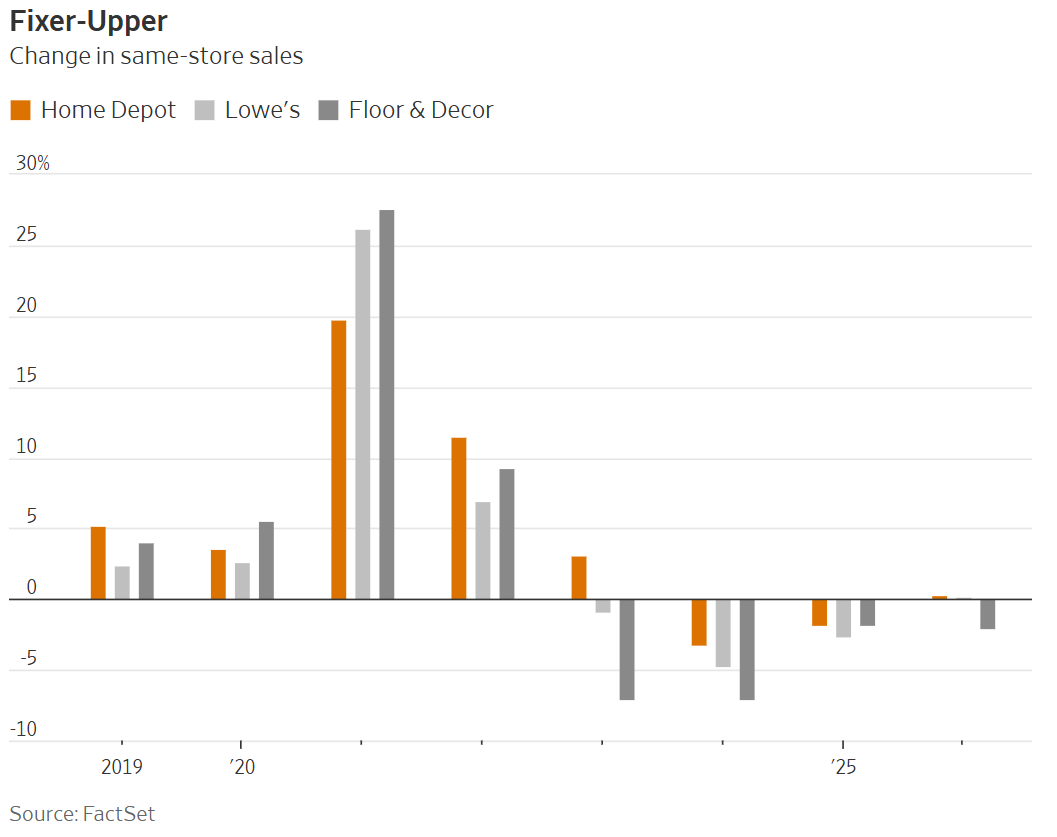
The Journal is cautious on the home improvement space going into second quarter results for Home Depot, which reports tomorrow morning, and Lowe's, which reports Wednesday morning, notes 2026 was widely expected to be a year of recovery across the industry but says this thesis is "running into new problems that will keep same-store sales growth around zero."
- Existing home sales have stagnated amid mid-6% mortgage rates that have kept potential buyers out of the market and have led many of those with low rates to stay put.
- Mortgage rates are not expected to decline any time soon -- the average 30-year fixed rate has risen by about a half a ppt since the Fed started cutting its rate target in 2024.
- The Journal credits both Home Depot and Lowe's for being "impressively profitable" and notes recent acquisitions that should help them better serve home builders and other pros but says the timing of the acquisitions hasn't been great given the macro pressures.
Source for Both Charts: WSJ
OTHER DEVELOPMENTS
US Footwear Industry sales increased 1% y/y in the first half of 2026, the same % increase as the first quarter acc'd to the latest data from Circana, which said a small increase in average selling price was partially offset by a decline in units and noted relative strength in performance footwear, up 6% on higher prices and units and driven by 13% growth in running shoes.
- Other growth categories within performance included cross-training, golf and volleyball.
- Sales of sport lifestyle footwear declined, while sales of fashion footwear remained flat, despite "all the buzz about a dress shoe comeback," quote per Footwear News.
Bed Bath & Beyond has officially changed its corporate name to Neighborhood Intelligence, as previously announced, and is now trading on the Nasdaq under the ticker NXH.
 SHEIN is now targeting a valuation of only $25B in its Hong Kong IPO acc'd to Reuters, which notes this is only a quarter the size of its valuation in a share sale four years ago and reflects a significant moderation in growth amid the end of tariff exemptions for small parcels shipped to the US and Europe. The offering is expected to happen later this week, and SHEIN is expected to raise gross proceeds of up to $2B by selling up to 8% of its total shares.
COMMERCIAL REAL ESTATE
Primark, which is part of the UK's AB Foods, will open its 46th US store on Thursday, 9/3/26, 35K sf, at Mall of America, will be the first Primark store in Minnesota, take total states to 15, and will follow the opening of a new store at Orlando Vineland Premium Outlets this Thursday.
MANAGEMENT UPDATES
We're not seeing anything too significant/noteworthy this morning...
STORE OPENING/CLOSING ANALYSIS
Significant YTD Announcements
So far this year, US retailers have announced plans to open/close ~3,975/~3,485 stores by our analysis, which covers all sectors except auto retail and excludes opening/closing announcements that were made in 2025 and prior but will carry over into 2026 and beyond.
The numbers this time last week were ~3,930/~3,480, and this time last year we tracked ~3,500/~4,120 YTD announced openings/closings.
For all of 2025, we tracked ~5,525 announced store openings, down 20% from 2024, and ~4,820 announced store closings, down 45% from 2024.
Note that openings/closings are specific numbers that have been announced, not completed, and could extend over several years.
Also note we include select non-US retailers (e.g. ALDI, POP MART, Lululemon) in our totals and small numbers of openings/closings if it's a significant development (e.g. digitally-native brands opening their first stores, highlighted below with an asterisk*), that we don't count concessions, pop-ups, seasonal stores, pilots, JV/partner-operated stores, acquired stores, or conversions, and that our closing tally excludes closings that are part of an ongoing business plan.
Latest Store Opening Announcements: Fabletics (digital native, activewear) has opened 12 new US stores since the beginning of the year, now has 135+ stores globally, and is planning to open 25 more US stores and 20 new international stores in countries including India, Mexico, Peru, Colombia and the UAE over the next 12 months acc'd to CEO Adam Goldenberg, who told Bloomberg recently the brand is holding off on China for now.
We previously had Fabletics opening 40 stores on a base of 120 and are now showing 45 new store openings on a base of 135+ and note the company's store expansion program is part of a plan to double annual revs to $2B within five years.
Grocery Outlet reported 2Q26 results last week and reaffirmed plans for 30-33 net new stores excluding the recent closing of 36 underperforming stores as part of an Optimization Plan, and Bealls, which has 660+ stores in 22 states and has an off-price/value focus, announced plans to open 25 new stores across 12 states this fall and in spring 2027, and will open its first stores in Michigan, where five are planned, with an average new store size of 20,800 sf.
Meijer, which is privately owned and has 500+ stores across the Midwest under a few different formats, will open a new 75K sf Meijer Grocery Store in Fishers, IN at the end of September, location is 15700 Southeastern Parkway, will be the second Meijer Grocery in Indiana, and the company also said it will open a 159K sf supercenter in Plymouth, MI on 9/30/26.
We previously has Meijer opening ~5 new stores and are taking our total to ~10.
Indochino, a digitally native, made-to-measure menswear retailer with 90+ showrooms in the US and Canada, plans to open 10 new <1K sf showrooms across the US, including six in early-2027 in Cherry Hill, NJ, Columbia, MD, Ross Park, PA, Brea, CA, Roosevelt Field, NY, and Boca Raton.
Also last week, Purple reported a weak overall 2Q26 and said it opened one new showroom in the quarter and plans to open another five showrooms this year vs. an original plan of seven new stores for the year, so we are trimming our number by one.
Latest Store Closing Announcements: Fossil reported 2Q26 results last week and said it closed six stores in the quarter and expects to end the year with 178 stores globally.
We previously had Fossil closing 15 of 199 stores and are now showing 21 closings to get to the 178 total stores at year-end.
- Dollar Gen (~460 on ~20,900 note)
- Casey's (400+ on 2,900+ note)
- Dollar Tree (~400 on 9,282)
- O'Reilly (225-235 net on 6,585 note)
- 7-Eleven NA (200+ on 13K+)
- ALDI USA (180+ on 2,600+ note)
- Five Below (~150 net on 1,921)
- TJX (146 net on 5,200+ globally)
- Yesway (130 on ~450)
- Academy Sports (~125 on 322 note)
- Burlington (115 net on 1,212)
- Ross Stores (110 on 2,267)
- Kroger (105-120 on ~2,800)
- Goodwill (100+ on ~3,400)
- Whole Foods (100 on 550+)
- Sheetz (100 on 830+)
- Paymore (90+ on 100+)
- Tractor Supply (85-90 on 2,395 note)
- Ollie's Bargain Outlet (75 on 645)
- SKIMS* (73 on 27)
- Boot Barn (70 on 539)
- Citi Trends (~65 on 590+)
- Bath & Body Wks (60+ net on 2,500)
- CVS (~60 on ~9K note)
- Barnes & Noble (60 on 670)
- Tailored Brands (55+ on 1K+ note)
- Urban Outfitters (54 on 784 owned)
- Levi Strauss (50-60 net on 3,400+)
- Ulta Beauty (50-60 net on 1,591)
- Build-A-Bear (50+ net on 660+ note)
- Abercrombie (50 on 829 owned)
- Warby Parker* (50 net on 323)
- Fabletics* (45 on 135+)
- Perfumania (43 on 280+)
- Advance Auto (40-45 on 4,300+)
- Lululemon (40-45 net owned on 811)
- Crocs (40 on ~400 owned/operated)
- Aerie and OFFLINE (~40 on 330+)
- Dick's House of Sport (32 on 35 note)
- Grocery Outlet (30-33 net on 570)
- Target (30+ on ~2K note)
- Trader Joe's (30+ on 600+)
- Vuori* (30 on ~150)
- Birkenstock Amer (30 net on ~15)
- Ernesta* (26 on 4)
- Nordstrom Rack (25+ on ~300)
- Bealls (25 on 660+)
- Fleet Feet + Marathon (~25 on 310+)
- Genesco (23 on 1,236)
- Dick's Field House (22 on 42 note)
- POP MART US (20+ on 60+)
- Walmart U.S. (~20 on 4,600+ note)
- Love's Travel Stops (20 on ~670)
- Williams-Sonoma (~20 on 512)
- Floor & Decor (20 on 270)
- Bob's Discount Furn (~20 on 209)
- Kendra Scott (20 on ~170 note)
- Consumer Cellular (20 on 100)
- HEYDUDE (~20 mostly outlets on 75)
- Cotopaxi* (20 on 20)
- Bu-cee's (17 announced on ~55)
- Home Depot (~15 on 2,359)
- Windsor (15 on ~350)
- Golf Galaxy (~15 on 113)
- IKEA US (~15 on 54)
- UNIQLO USA (14 on 78)
- a.k.a.'s Princess Polly* (14 on 13 US)
- Aritzia (12-13 mostly US on 144 total)
- Caleres (12 on ~820)
- Shoe Carnival/Station (11-15 on 426)
- The Buckle (11-13 net on 440)
- Advance Mega Hub (10-15 on 33)
- Garage (10-12 net on 300)
- Signet Jewelers (up to 10 on 2,582)
- Publix (~10 on 1,400+)
- La-Z-Boy (10 on 380 total N America)
- Cato (up to 10 on 1,070)
- Meijer (~10 on 500+)
- Indochino* (10 on 90+)
- Vivaia* (10 on 1)
- Lovesac (8 net on 278)
- Sukoshi (8 on 9 US)
- Salomon (7-10 on 2 US)
- BYLT* (7 on 15)
- Wayfair* (7 on 2 note)
- Haverty Furniture (6 net on 129)
- Big Y (6 on 77)
- RH (6 on 75)
- Purple (6 on 55)
- Zumiez (5 US on 716 total worldwide)
- Boll & Branch* (5 on 15)
- Kurt Geiger London (5 on 5 US)
- Arhaus (4-6 on 107)
- U.S. Polo Assn. (4 on 1,200+)
- Food Lion (4 on 1,100+)
- Best Buy (4 net US on 1K+ in NA)
- Tilly's (4 on 224)
- Ocean State Job Lot (4 on 175)
- Vera Bradley Outlet (4 on 87)
- True Religion (4 on 57)
- Chair King (4 on 52)
- FIGS* (4 on 5)
- Ana Luisa* (4 on 2)
- Joybird* (3-4 on 16)
- Madewell (3 on ~150)
- Albertsons' Tom Thumb (3 on ~70)
- Brilliant Earth* (3 on 42)
- Suitsupply (3 US on ~40 US)
- Johnnie-O (3 on 23)
- COS US (3 on 12)
- Whole Foods Mkt Daily Shop (3 on 8)
- Brochu Walker (3 on 5)
- BRUNT Workwear (3 on 0)
- Bass Pro Shops (2 on 180+)
- Bassett Furniture (2 on 86)
- YETI (2 on 25+)
- FRAME (2 on 20+)
- The RealReal* (2 on 18)
- CardVault by Tom Brady (2 on 10)
- Yellow Rose Kendra Scott* (2 on 3)
- Amazon* Big Box (2 on 0)
- Cider* (2 on 0)
- J.Jill (1-5 net on 256)
- 7th Avenue* (1 on 20+)
- Thursday Boot Company* (1 on 4)
- Revolve* (1 on 2)
- Povision* (1 on 0)
- Addison Bay* (1 on 3)
- GameStop (700+ US of 2,300+ note)
- 7-Eleven NA (645 of 13K+)
- Francesca's (450+ of 450+)
- Family Dollar (350+ of 7,450+)
- Hibbett (~175 of ~980)
- Eddie Bauer US + Can (~175 of ~175)
- Signet Jewelers (~100 of 2,582)
- Value City Furniture (79 of 79)
- Dollar Tree (~75 of 9,282)
- Genesco (75 of 1,236)
- Tractor Supply's Petsense (75 of 207)
- West Marine (59 of 200+)
- Saks OFF 5TH (57 of 69)
- Amazon Fresh (57 of 57)
- Cato (up to 40 of 1,070)
- Grocery Outlet (36 of 570)
- CVS (~35 of ~9K note)
- Zumiez (26 of 716 total worldwide)
- Fossil (21 of 199)
- American Eagle (20-25 AE of 805 AE)
- Abercrombie (20 of 829 owned)
- Williams-Sonoma (~20 of 512)
- Allbirds* US full-price (~20 of ~20)
- Urban Outfitters (19 of 784 owned)
- Shoe Carnival/Station (18-24 of 426)
- Saks Fifth Avenue full-line (18 of 33)
- Petco (15-20 net of 1,382)
- Caleres (15 of ~820)
- Amazon Go (15 of 15)
- Albertsons (14 net of 2,200+)
- Ross Stores (10-15 of 1,900+)
- Amer. Signature Furniture (10 of 10)
- Tilly's (6 of 224)
- Sportsman's Warehouse (5 of ~150)
- Johnny Was (5 of 78)
- Neiman Marcus Last Call (5 of 5)
- Neiman Marcus full-line (4 of 36)
- Apple US retail (3 of ~270)
- Vince (3 net of 60)
- Nordstrom (2 of ~90 full-line)
MACRO/CONSUMER INSIGHT
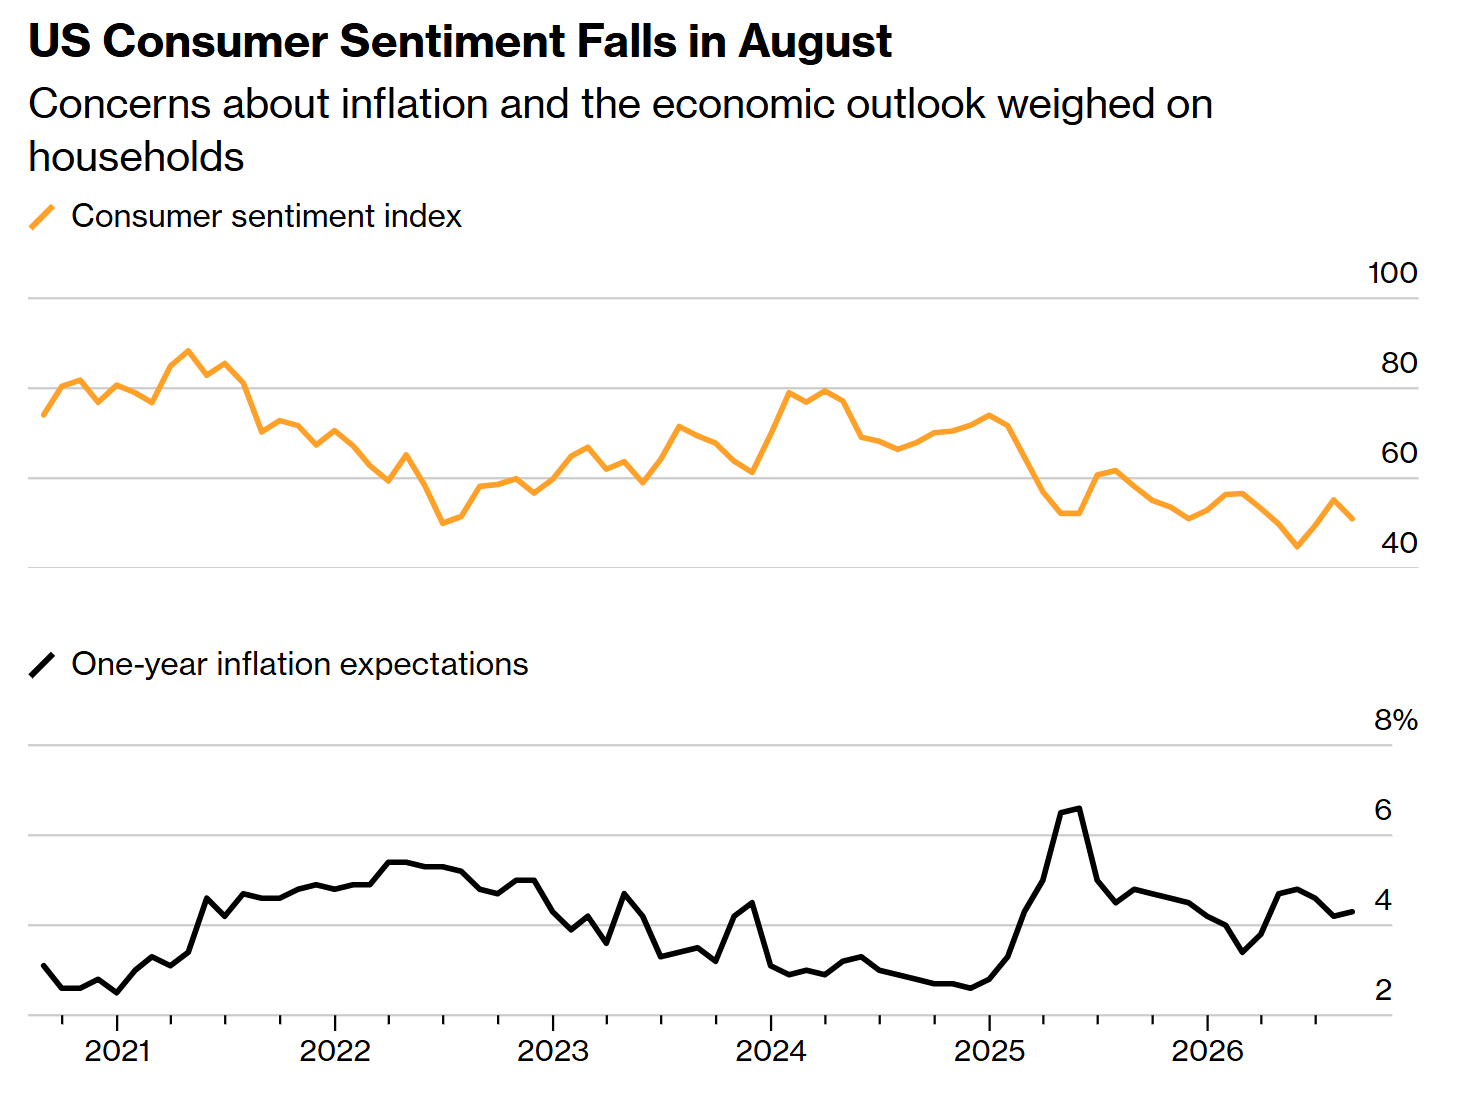
Out Friday, U. Mich. Sentiment for August (preliminary) was significantly weaker than expected at 51.0 vs. the Street's 54.5 estimate and a meaningful decline from a final read of 55.2 in July as sentiment deteriorated across demographic groups, but in particular with older consumers, lower-income consumers and consumers without a college degree.
- Expectations for inflation over the next 12 months rose slightly, to +4.3%.
- DoRCR INSIGHT: Sentiment and spending have not correlated at all in recent quarters, but fragile consumer psychology, along with a low savings rate, could make for a much tougher retail dynamic if we get another month or two of negative Nonfarm Payrolls.
Also out Friday, headline Retail Sales for July were weaker than expected and fell 0.6% m/m vs. the Street's +0.1% estimate and after a 0.2% m/m increase in June, while headline Retail Sales rose 5.0% on year-over-year basis vs. July 2025 after a revised +6.8% increase in June.
- DoRCR INSIGHT: The +5.0% y/y increase in Retail Sales July is consistent with the latest CNBC/NRF Retail Monitor, powered by Affinity Solutions, and reflects the shift of Amazon's Prime Day and related retailer promotions from July 2025 to June 2026 and a pull-forward of BTS sales; retail sales have been strong YTD, but we are keeping a close eye on the labor market.
Out Thursday, the headline Producer Price Index for July was lower than expected at +4.7% y/y vs. the Street's +4.9% and down significantly from +5.5% in June, while core PPI excluding food and energy increased 4.2% y/y, also a significant moderation from June, when it was +4.7%.
- DoRCR INSIGHT: These are bigger m/m declines than what we saw with Wednesday's CPI report, and this is encouraging as it relates to the impact of inflation on consumer spending.
Source: University of Michigan and Bloomberg (for chart)
SELECT ANALYST ACTIONS
Walmart (WMT, $115.27) Guggenheim maintains a Buy rating and lowers its target from $137 to $135 in front of 2Q27 (July) results Thursday morning, thinks the setup for the stock has improved with progressively lower Street expectations and incremental financial resources from tariff refunds, but also cautions around moderating food volumes and weaker demand for general merch.
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.