Companies and Subjects discussed in this morning's report include: Tapestry's Strong 4Q26, though with slowing Coach revs, Dillard's is first dept store to report, and comps slowed, Grocery Outlet making progress in turnaround after systems issues, more signs of easing inflation with the latest Producer Price Index...

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Thursday, August 13, 2026 | Published Daily by ~11:30 AM ET
Results from Tapestry, Dillard's, Grocery Outlet + More Signs of Easing Inflation with Latest PPI...
THIS WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/10)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
- Citi Trends at the virtual D.A. Davidson 2026 Small Cap Conference, time not specified
- Purple Innovation reports 2Q26, call 4:30 pm, Street at sales/EPS of $104.4M/($2.18)
Tuesday (8/11)
- On Holding reports 2Q26, call 8:00 am, Street at sales/EPS of CHF878.40M/CHF0.34
- Existing Home Sales for July at 10:00 am, Street at 4.05M SAAR vs. prior 4.09M
- Sally Beauty at the Canaccord Genuity Growth Conference at 10:00 am
Wednesday (8/12)
- Warby Parker doing meetings in Minneapolis/Chicago today/tomorrow, hosted by BTIG
- Etsy at the Canaccord Genuity Growth Conference at 8:00 am
- Consumer Price Index for July at 8:30 am, Street at +3.4% y/y vs. prior +3.5%
- Kontoor Brands reports 2Q26, call 8:30 am, Street at sales/EPS of $587.0M/$1.05
- DoRCR hosts its monthly Retail & Consumer webinar at 2:00 pm, link to join here, will cover macro/consumer + topical issues, including thoughts on the 2026 back-to-school season
- Grocery Outlet reports 2Q26, call 4:30 pm, Street at comps down 1.5%, EPS of $0.13
- Fossil reports 2Q26, call 5:00 pm, Street at sales/EPS of $199.3M/($0.36)
- Lulu's Fashion Lounge reports 2Q26, call 5:00 pm, no Street estimates
Thursday (8/13)
- Tapestry reports 4Q26, call 8:00 am, Street at sales/EPS of $1.87B/$1.28
- Birkenstock reports 3Q26, call 8:00 am, Street at sales/EPS of EUR715.6M/EUR0.76
- YETI reports 2Q26, call 8:00 am, Street at sales/EPS of $483.8M/$0.54
- Producer Price Index for July at 8:30 am, Street at +4.9% y/y vs. prior +5.5%
- Jobless Claims for the week ended 8/8/26 at 8:30 am, Street at 205K vs. prior 199K
- Wolverine Worldwide reports 2Q26, call 8:30 am, Street at sales/EPS of $500.7M/$0.38
- Yesway reports 2Q26, call 8:30 am, Street at comps up 2.0%, EPS of $0.47
Friday (8/14)
- DoRCR publishes its proprietary Next Week's Calendar
- Retail Sales for July at 8:30 am, Street at +0.1% m/m vs. prior +0.2%
- U. Mich. Sentiment for August (preliminary) at 10:00 am, Street at 54.5 vs. prior 55.2
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is up 0.2% as of ~11:15 am vs. a 0.5% gain in the S&P 500, which is hitting all-time highs after another encouraging read on inflation gives the Fed add'l breathing room.
- Stronger retail stocks include BIRK, up 16% after a beat-and-raise quarter, also WWW (up 10%, same dynamic), WOOF (up 5%), DXLG (up 5%) and YSWY (up 5%, reported here).
- Weaker retail stocks: TPR, down 15% on slowing Coach growth, YETI (down 13%, results), JD (down 8%, results), DDS (down 5%, sequential slowing) and REF (down 4%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
Tapestry (TPR, $153.74) had a good 4Q26 (June) with in-line constant-currency revs up 11% y/y excluding the divested Stuart Weitzman business, though growth did slow from the third quarter's +23%, while non-GAAP EPS grew nearly 30% and were better than expected on strong gross margin performance, and mgmt guided FY27 in line and announced a 16% hike in the dividend.
- Total sales were $1.88B and included $1.64B from Coach, up 14% y/y constant currency after +29% in the third quarter, and $235.1M from Kate Spade, down 7% after (11%) in 3Q26, also $1.15B from North America, up 7%, and $352.2M in sales from China, up 28%.
- Revs fell 4% in Japan and increased 22% in Other Asia and 19% in Europe.
- Other callouts: Tapestry added ~11M new customers in FY26, ~35% of them Gen Z, Coach handbag AUR grew by a mid-teens rate for the quarter and FY, leathergoods outperformed on AUR and unit growth, DTC revs increased 11% in the quarter and 16% for the year.
- Non-GAAP EPS were $1.32 vs. $1.04 last year and the Street's $1.28 estimate and were driven in part by 180 bps of gross margin expansion on operational improvements (170 bps) and the Stuart Weitzman divestiture (60 bps), partially offset by tariffs and duties (60 bps).
- Inventories look good and were down 4% y/y at the end of the quarter.
- FY27 guidance includes mid-single-digit growth in revs, to $8.4B-$8.5B, ~50 bps of op margin expansion, and low-double-digit growth in EPS, to $7.80-$7.90 vs. the Street's $7.87.
- Full-year guidance assumes $1.35B in stock repurchase after $1.35B in FY26.
- DoRCR INSIGHT: The stock is taking a big hit this morning, even though there were no big surprises with the quarter or guidance, likely reflects the slower growth at Coach, which is still doing quite well but is coming off a period of even more impressive gains.
Dillard's (DDS, $636.02) reported an in-line/upside 2Q26 (June), though with some sequential deceleration from the first quarter as consumers remained "somewhat resilient," while earnings were essentially flat y/y when excluding $28.4M in IEEPA refunds.
- Comps increased 1% after +3% in the first quarter, while total retail sales increased 1% to $1.46B and reflected significant increases in ladies' accessories and lingerie, moderate increases in home and furniture, and slight increases in shoes and men's apparel.
- Weaker areas in the quarter included juniors' and children's and ladies' apparel.
- Ex-items EPS were $4.43 vs. $4.42 last year and the Street's $4.29 estimate and incorporated 20 bps of gross margin improvement when excluding tariff refund impacts.
- Dillard's does not give guidance and does not hold quarterly conference calls.
- DoRCR INSIGHT: Dillard's is the first of the department store retailers to report July quarter results, and while the +1% comp is in line with Street expectations, the sequential slowing is noteworthy and could be a negative read-through for the group overall; that said, we also note the first quarter for retail in general benefited from much higher tax refunds.
Grocery Outlet (GO, $10.17) had a soft but better-than-expected 2Q26 (June) with sequential improvement in comps against a somewhat tougher comparison and credited an improved opportunistic offering and increased value perception, and management bumped up the lower-ends of guided ranges for comps, sales and EBITDA and reaffirmed plans for 30-33 net new stores excluding the recent closing of 36 underperforming stores as part of an Optimization Plan.
- Comps decreased 0.3% on top of +1.1% last year and after (1.0%) on top of +0.3% in the first quarter, were a bit better than the Street's (1.5%), and incorporated a 1.8% increase in the number of transactions and a 2.1% decrease in average transaction size.
- Total sales increased 1% y/y in the quarter, to $1.19B vs. the Street's $1.17B estimate.
- Adjusted EPS were $0.20 vs. $0.23 last year and the Street's $0.13 estimate and incorporated a 40 bps decrease in gross margin, mostly on product promos aimed at driving sales and inventory markdowns + write-offs related to the Optimization Plan store closings.
- Grocery Outlet opened 10 stores and closed 12 in the quarter, including nine that were part of the Optimization Plan, and finished the quarter with 547 stores in 16 states.
- 2026 guidance now includes comps of flat to down 0.5%, total sales of $4.70B-$4.72B vs. $4.69B in 2025, which had 53 weeks, and adjusted EPS of $0.51-$0.55 vs. $0.76 in 2025 and assuming 30-33 net new stores, not including the 36 Optimization Plan closings.
- DoRCR INSIGHT: More signs of progress after a protracted period of systems and execution issues and good to see the renewed focus on opportunistic buys driving some sequential comp improvement, but GO has a long way to go to establish more consistency of trend.
Analyst Actions that could move retail stocks today:
- Five Below (FIVE, $238.15) Jefferies upgrades from Hold to Buy
INDUSTRY INSIGHT
US grocery unit volumes continued to decline in July acc'd to new data from Circana, which put overall food and beverage unit sales down 0.9% y/y for the four weeks ended 7/26/26 and showed the biggest declines in fresh produce (down 4.7%) and bakery units (down 2.7%).
- Better-performing departments included refrigerated foods, up 1.2%, and frozen foods, up 0.2%, while meat and deli volumes were both essentially flat with July 2025.
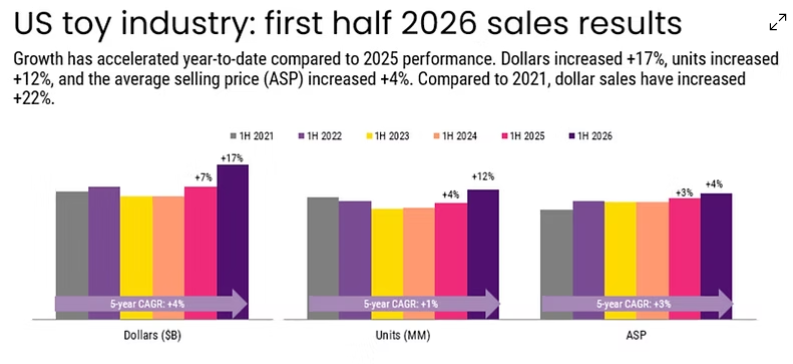
US toy industry sales have been strong this year and increased 17% in the six months ending June, also acc'd to Circana, which says unit sales increased 12%, while the average selling price grew 4%, and noted particular strength in trading cards, collectibles and sports-related products.
- Sales of licensed toys continued to outperform, grew 24% y/y, and comprised nearly 40% of all toy sales in the first half of the year, up two percentage points from 1H25.
- Adult-only households accounted for more than half of all toy sales in the period.
- Per Circana, "the toy industry heads into the holiday season with strong momentum."
OTHER DEVELOPMENTS
Target shared some details about its 2026 Halloween assortment and said nearly 70% of the collection is new this year, while ~60% is exclusive to Target, and 60% of decor products are priced <$10, while half of all Halloween costumes + accessories are priced <$25.
Birkenstock (BIRK, $36.74) had a strong and better-than-expected 3Q26 (June) with slight sequential acceleration in constant-currency revenue growth, to +15%, or EUR720M, driven by broad-based strength across geographies -- Americas up 14%, EMEA up 15%, APAC up 23% -- and by mid-teens growth in both DTC and B2B, while adjusted EBITDA grew 11% y/y to EUR242M.
- Other callouts: Closed-toe footwear did well on newness in clogs and shoes, BIRK opened four new stores in the Americas in the quarter, to end with 21, and mgmt raised guidance.
YETI (YETI, $50.84) reported strong and in-line 2Q26 (June) sales up 9% y/y to $483.9M, with the US up 6% to $391.0M and International up 19% to $92.9M, while adjusted operating income fell 7% y/y to $68.2M but was better than expected and incorporated 170 bps of gross margin improvement, including 110 bps from operational drivers, and 60 bps of net tariff benefit.
- Management maintained full-year guidance for 7%-8% growth in sales from 2025's $1.87B and raised adjusted operating income by 200 bps, to 10%-12% y/y growth.
- YETI also announced an Investor Day, will take place 9/17/26 in Austin, TX.
Wolverine Worldwide (WWW, $18.06) had a good and modestly better-than-expected 2Q26 (June) with revs of $506.4M, up 6% y/y in constant-currency and incorporating 10% growth at Merrell, 9% growth at Saucony, 7% growth at Wolverine, and a 3% decline at Sweaty Betty, also 10% growth in International, to $277.2M, or 55% of the total, and 9% growth in adjusted EPS, to $0.40.
- Management also raised full-year revenue, gross and op margin, and EPS guidance.
- Full-year revs are expected to grow by a mid-single-digit %, to $1.98B-$2.00B.
Fossil (FOSL, $5.27) had a soft but better-than-expected 2Q26 (June) with sales of $209.7M, down 4% y/y in constant currency, with half the decline driven by store rationalization and also incorporating an 18% decline in Europe, a 4% increase in Asia, and a slight increase in the Americas, as well as a 1% decline in traditional watch sales, a 31% drop in leathers, and an 11% drop in jewelry sales.
- Comparable retail sales fell 8% after a 15% drop in the first quarter.
- Wholesale sales increased 1% y/y constant currency, while DTC sales fell 15%.
- Adjusted EBITDA was $8.6M vs. $7.0M last year and incorporated 490 bps of gross margin improvement on full-price sales, sourcing initiatives and lower tariffs.
- Management raised full-year sales guidance slightly and now expects a 3%-5% decline in sales, with a return to growth in the fourth quarter, same assumption as before.
- Operating margin is now expected at 4%-6% vs. a prior 3%-5% range.
Lulu's Fashion Lounge (LVLU, $16.94) had a weak 2Q26 (June) against no Street estimates with sequential deterioration in revs, which fell 17% y/y to $67.8M as mgmt continues to reorient the assortment back toward its more traditional categories and customer tastes, while adjusted EBITDA doubled year-over-year on 330 bps of gross margin expansion but was still only $1.0M.
- Total Orders Placed fell 17% y/y, while average order value rose slightly, to $147.
- Active customers decreased 13% y/y to 2.2M and decreased 5% from the first quarter.
- Ending inventory was down 23% as management works to align receipts with demand.
- Mgmt reaffirmed full-year guidance for an improvement in the net revenue growth trend from 2025's (11%) and for positive adjusted EBITDA vs. ($1.2M) in 2025.
Brooks Running (Berkshire Hathaway) said yesterday its revs grew 14% y/y in the first half of 2026 and incorporated 9% growth in the Americas, nearly 40% growth in EMEA, and a 10% increase in Asia-Pacific as demand for its footwear, apparel and accessories "remained strong across regions and channels" and as consumers globally continue to focus on health and wellness.
- The company also noted the global running market grew 10% last year, to $43B.
Casey's (CASY, $839.03) is making a small acquisition and has agreed to buy family-owned Pak-A-Sak, which has 24 gas/c-stores across the Texas panhandle.
- Casey's has 2,900+ stores across 19 states, so this is not a needle-moving deal, though it is consistent with the company's ongoing plan to grow organically and via acquisitions.
J.Jill is making a new push in denim and has expanded its assortment with new fits, leg shapes, fabric styles and washes, available in stores, online and through the catalog, and with prices ranging from $89 to $119, and associates across the chain are being trained as denim fit specialists.
Frasers Group (UK) has acquired Harvey Nichols department store business out of insolvency from billionaire Dickson Poon and edged out Next Plc in the bidding acc'd to Bloomberg, which says the deal includes the Harvey Nichols 200K sf flagship in London's Knightsbridge district, smaller stores across the UK, and the online ops.
COMMERCIAL REAL ESTATE
Bealls, which has 660+ stores in 22 states and has an off-price/value focus, is planning to open 13 new stores across six states this fall and has also expanded its NYC buying office acc'd to Director of Communications Susan Santangelo and as discussed by Retail Dive.
MANAGEMENT UPDATES
Bed Bath & Beyond has hired DHI Group financial exec since the spring and former longtime Maxar Technologies and KPMG financial exec Jill Windrum as Chief Accounting Officer and Deputy CFO.
MACRO/CONSUMER INSIGHT
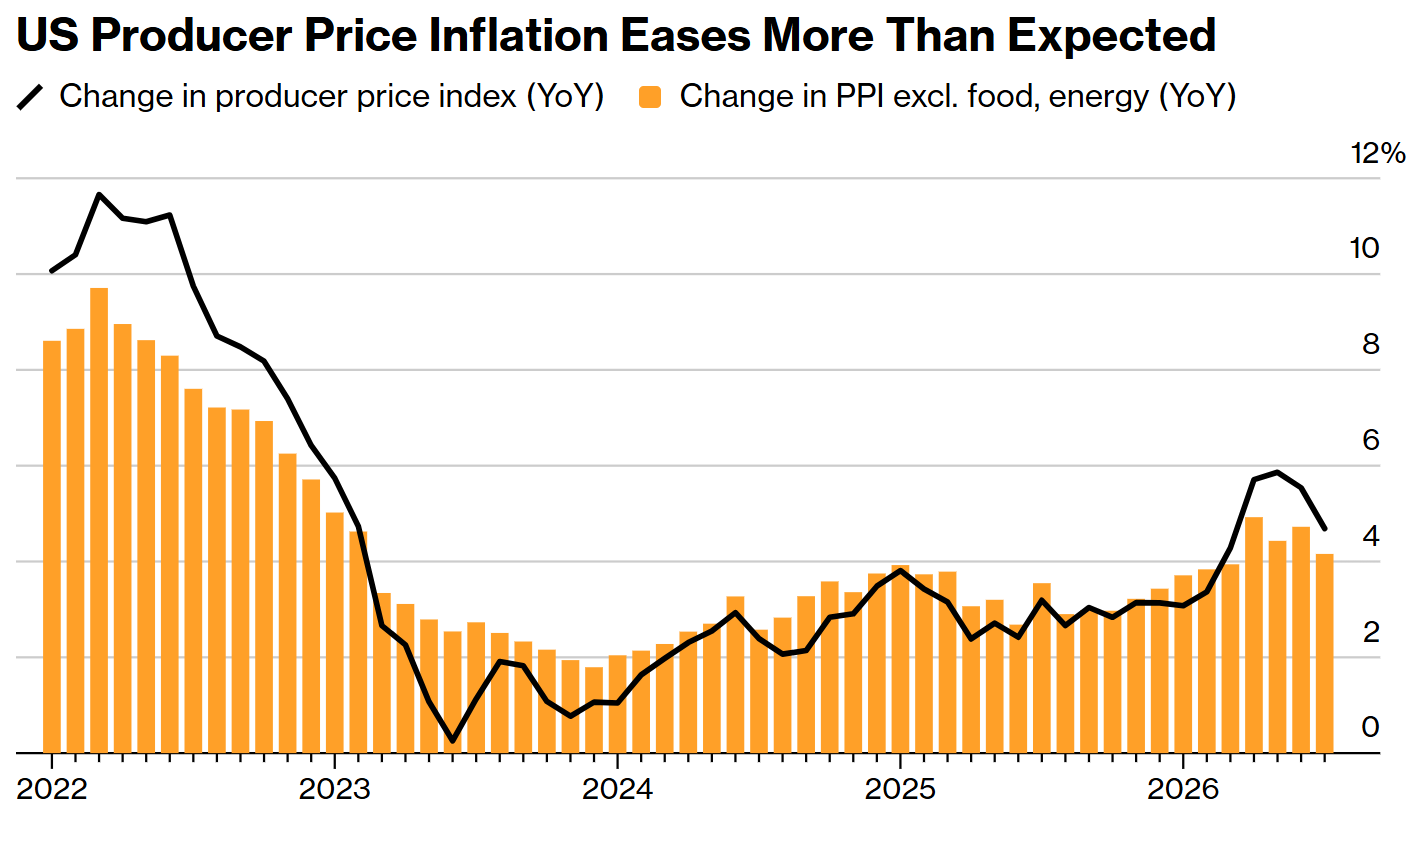
Out at 8:30 am, the headline Producer Price Index for July was lower than expected at +4.7% y/y vs. the Street's +4.9% and down significantly from +5.5% in June, while core PPI excluding food and energy increased 4.2% y/y, also a significant moderation from June, when it was +4.7%.
- DoRCR INSIGHT: These are bigger m/m declines than what we saw with yesterday's CPI report, and this is very encouraging as it relates to the impact of inflation on consumer spending.
Also out at 8:30 am, Jobless Claims for the week ended 8/8/26 were a little higher than expected at 209K vs. the Street's 205K and up 9K from a revised 200K the prior week, though they remain low historically, while Continuing Claims, reported with a week's lag, decreased 22K to 1.78M.
- DoRCR INSIGHT: Reassuring to see another low Claims number after last week's weak Nonfarm Payrolls for July report -- down 23K -- supports the "low-hire, low-fire" narrative around the labor market, and with Unemployment at only 4.1%, is positive for consumer spending.
Out yesterday, the headline Consumer Price Index for July was right in line with expectations at +3.4% y/y, a slight easing from +3.5% in June, while core CPI excluding food and energy was also in line at +2.5% y/y and also eased by 10 bps from June, when it was +2.6%.
- DoRCR INSIGHT: This is good news for consumers, and along with the unexpected decline in Nonfarm Payrolls in July, gives the Fed some breathing room with interest rates, but it is worth noting the headline +3.4% inflation reading is higher than the last reading on wage growth, at +3.2% y/y, and implies a slight reduction in household purchasing power.
Out Tuesday and acc'd to the U.S. Energy Information Administration, a gallon of regular Unleaded Gasoline cost $4.01 on average across the US for the week ended 8/10/26, down $0.07 from the prior week but up $0.89 per gallon from the same week last year.
- A gallon of diesel cost $5.26, down $0.09 on the week but up $1.50 from last year.
- DoRCR INSIGHT: Gas prices could come down quickly with a US/Iran peace deal and reopening of the Strait of Hormuz, but for now, the significant y/y increase is a meaningful headwind to discretionary spending, esp by lower-income consumers (e.g. core dollar store customer).
Source: BLS and Bloomberg (for chart)
SELECT ANALYST ACTIONS
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.