Special Note: DoRCR is launching a monthly Zoom webinar for our subscribers, second Wednesday of each month at 2:00 pm ET, will cover macro/consumer + topical issues and include a chat-based Q&A. The first one is today, 8/12/26, link to join here. You do not need to register in advance, and your participation will not be shown to other participants.

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Wednesday, August 12, 2026 | Published Daily by ~11:30 AM ET
Results from Kontoor Brands, Fabletics Opening Many Stores, Encouraging Inflation Data...
THIS WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (8/10)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
- Citi Trends at the virtual D.A. Davidson 2026 Small Cap Conference, time not specified
- Purple Innovation reports 2Q26, call 4:30 pm, Street at sales/EPS of $104.4M/($2.18)
Tuesday (8/11)
- On Holding reports 2Q26, call 8:00 am, Street at sales/EPS of CHF878.40M/CHF0.34
- Existing Home Sales for July at 10:00 am, Street at 4.05M SAAR vs. prior 4.09M
- Sally Beauty at the Canaccord Genuity Growth Conference at 10:00 am
Wednesday (8/12)
- Warby Parker doing meetings in Minneapolis/Chicago today/tomorrow, hosted by BTIG
- Etsy at the Canaccord Genuity Growth Conference at 8:00 am
- Consumer Price Index for July at 8:30 am, Street at +3.4% y/y vs. prior +3.5%
- Kontoor Brands reports 2Q26, call 8:30 am, Street at sales/EPS of $587.0M/$1.05
- DoRCR hosts its monthly Retail & Consumer webinar at 2:00 pm, link to join here, will cover macro/consumer + topical issues, including thoughts on the 2026 back-to-school season
- Grocery Outlet reports 2Q26, call 4:30 pm, Street at comps down 1.5%, EPS of $0.13
- Fossil reports 2Q26, call 5:00 pm, Street at sales/EPS of $199.3M/($0.36)
- Lulu's Fashion Lounge reports 2Q26, call 5:00 pm, no Street estimates
Thursday (8/13)
- Tapestry reports 4Q26, call 8:00 am, Street at sales/EPS of $1.87B/$1.28
- Birkenstock reports 3Q26, call 8:00 am, Street at sales/EPS of EUR715.3M/EUR0.76
- YETI reports 2Q26, call 8:00 am, Street at sales/EPS of $483.8M/$0.54
- Producer Price Index for July at 8:30 am, Street at +4.9% y/y vs. prior +5.5%
- Jobless Claims for the week ended 8/8/26 at 8:30 am, Street at 205K vs. prior 199K
- Wolverine Worldwide reports 2Q26, call 8:30 am, Street at sales/EPS of $500.7M/$0.38
- Yesway reports 2Q26, call 8:30 am, Street at comps up 2.0%, EPS of $0.47
Friday (8/14)
- DoRCR publishes its proprietary Next Week's Calendar
- Retail Sales for July at 8:30 am, Street at +0.1% m/m vs. prior +0.2%
- U. Mich. Sentiment for August (preliminary) at 10:00 am, Street at 54.5 vs. prior 55.2
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is down 0.9% as of ~10:00 am vs. a 0.2% gain in the S&P 500, which is higher as the latest CPI shows a slight easing and gives the Fed some more breathing room.
- Weaker retail stocks include LVLU, RH, CAL, SIG and AEO, all down 3%-4%.
- Stronger retail stocks include LANV, which is up 10%, also KTB (up 9% after results showing Helly Hansen strength), volatile DBGI (up 8%), VNCE (up 4%) and KSS (up 3%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
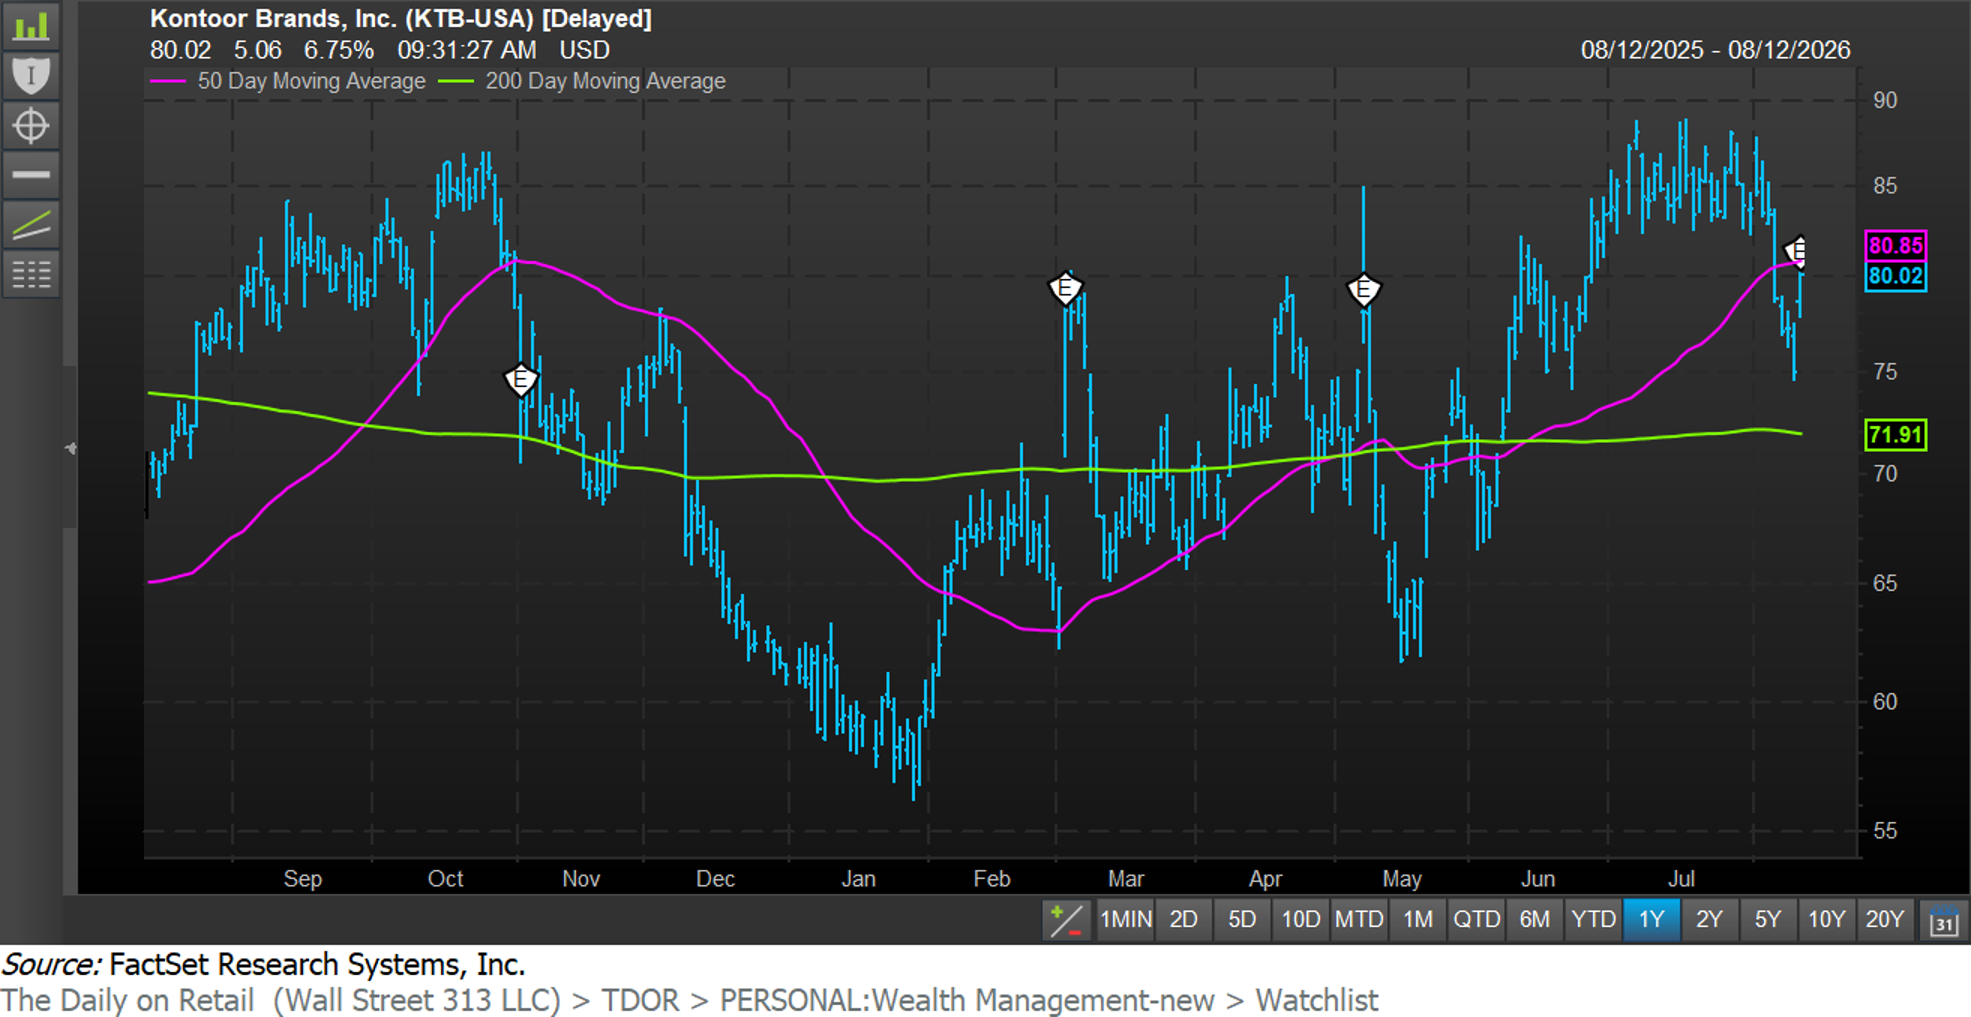
Kontoor Brands (KTB, $74.96) reported essentially in-line 2Q26 (June) revs up 19% y/y, driven primarily by last year's acquisition of Helly Hansen, and by slight y/y growth at Wrangler, while earnings were also close to expectations and incorporated gross margin benefits from Project Jeanius, Helly Hansen, mix and pricing; mgmt maintained full-year revenue guidance, raised the EPS range, and said it plans to put some proceeds from the pending Lee sale into a $400M ASR.
- Revs from continuing ops excluding Lee were $584M and included a $114M contribution from Lee and 2% growth at Wrangler, to $469M, after +4% at Wrangler in the first quarter.
- Mgmt called out strong performance in female, DTC and international, and also said Helly Hansen's revs grew by a double-digit rate on a pro forma basis in the quarter.
- Wrangler US revs increased 1% on a 9% increase in DTC and flat wholesale revs, while Wrangler international revs grew 10% on a 31%/7% increase in DTC/wholesale.
- Adjusted EPS increased 13% y/y to $1.06 vs. the Street's $1.05 and incorporated 710 bps of gross margin improvement and 10 bps of operating margin improvement -- Helly Hansen has a higher gross margin rate but also has a higher SG&A ratio.
- Inventories look good and were down 3% y/y, mostly on lower Helly Hansen inventories.
- Full-year guidance still includes revs of $2.66B-$2.71B, while management raised the adjusted EPS range by $0.10, now expects $5.25-$5.35 and still assuming an immaterial impact to EPS -- over the next 12-18 months -- from the pending sale of Lee to ABG.
- EPS guidance now assumes an incremental $0.36 per share of investment spending.
- The sale of Lee to ABG for an initial $750M is still expected to close in 4Q26, and $400M of the $750M will go to accelerated share repurchase, while the rest will go to debt reduction.
- DoRCR INSIGHT: The Helly Hansen acquisition is proving to be a nice win for KTB -- it's a strong global outdoor/work brand with plenty of whitespace, revs are growing double-digits, profitability is improving via integration onto Kontoor's platform -- but the slowing growth at the core/legacy Wrangler brand -- and underperformance vs. Levi Strauss -- is of some concern.
Analyst Actions that could move retail stocks today:
- On Holding (ONON, $30.91) Raymond James downgrades from Strong Buy to Outperform
- Gap (GAP, $20.96) Jefferies downgrades from Buy to Hold
OTHER DEVELOPMENTS
Home Depot (HD, $354.78) CEO Ted Decker is taking a medical leave expected to last a few months, and his responsibilities are being assumed on an interim basis by Senior EVP Ann-Marie Campbell, who will oversee day-to-day ops, and CFO Richard McPhail, who will oversee financial management and Pro subsidiaries, while director Greg Brenneman will temporarily chair the board.
Pajar Canada has acquired Grendene Global Brands USA from Brazilian footwear manufacturer Grendene S/A for $3.6M and now controls distribution and commercial management of the Melissa and Mini Melissa brands in the US. Pajar Canada is based in Montreal and owned and led by the founding Golbert family.
COMMERCIAL REAL ESTATE
Fabletics (digital native, activewear) has opened 12 new US stores since the beginning of the year, now has 135+ stores globally, and is planning to open 25 more US stores and 20 new international stores in countries including India, Mexico, Peru, Colombia and the UAE over the next 12 months acc'd to CEO Adam Goldenberg, who told Bloomberg the brand is holding off on China for now.
- The store expansion is part of a plan to double annual revs to $2B within five years.
Meijer, which is privately owned and has 500+ stores across the Midwest under a few different formats, will open a new 75K sf Meijer Grocery Store in Fishers, IN at the end of September, location is 15700 Southeastern Parkway, will be the second Meijer Grocery in Indiana.
- Meijer is also planning to open a 159K sf supercenter in Plymouth, MI on 9/30/26.
Bershka (Inditex, Spain) has opened its first permanent US store, at Aventura Mall in Miami, and plans to open add'l US stores, starting with Florida and the South acc'd to WWD, which says store size tends to range from 10K-20K sf and notes Bershka has 850+ stores in 60+ markets globally.
MANAGEMENT UPDATES
Exemplar Luxury Group (formerly Saks Global) Chief Buying Officer since January 2025 and former Neiman Marcus exec, also former Diane von Furstenberg and former Tory Burch, Valentino and Ferragamo exec Paolo Riva is leaving the company in mid-September for personal reasons.
Kontoor Brands CFO since mid-2023 and former BruMate COO and CFO and former longtime VF Corporation financial exec Joe Alkire has been appointed to the expanded position of President and Chief Financial Officer and will continue to report directly to CEO Scott Baxter.
Kroger has hired Olive (online shopping) Founder and CEO from 2020-2023 and former Walmart SVP, Head of US eCommerce Supply Chain and Logistics and Jet Co-Founder and COO Nathan Faust as EVP and Chief eCommerce Officer, starts at the beginning of September.
Lululemon Chief Strategy Officer since April 2025 and Lululemon exec for the past 14+ years, also former longtime Gap and Old Navy exec Rachel Acheson has left the company acc'd to Bloomberg, which notes the departure comes about a month before Heidi O'Neill takes over as CEO.
Shoe Station (formerly Shoe Carnival) has hired Colossal Management Chief Marketing Officer for the past year or so and former Shoe Carnival marketing exec from November 2024 through April 2025 and former 6+ year Leslie's marketing exec Tracy Dick as Chief Marketing Officer.
Target has hired Lowe's SVP, Stores, Data, AI and Innovation since December 2022, Lowe's technology exec since 2020, also Merkatus Partners and Cognitive Retail Co-Founder and longtime Staples e-commerce/tech exec Chandhu Nair as Chief AI Officer, a new position.
MACRO/CONSUMER INSIGHT
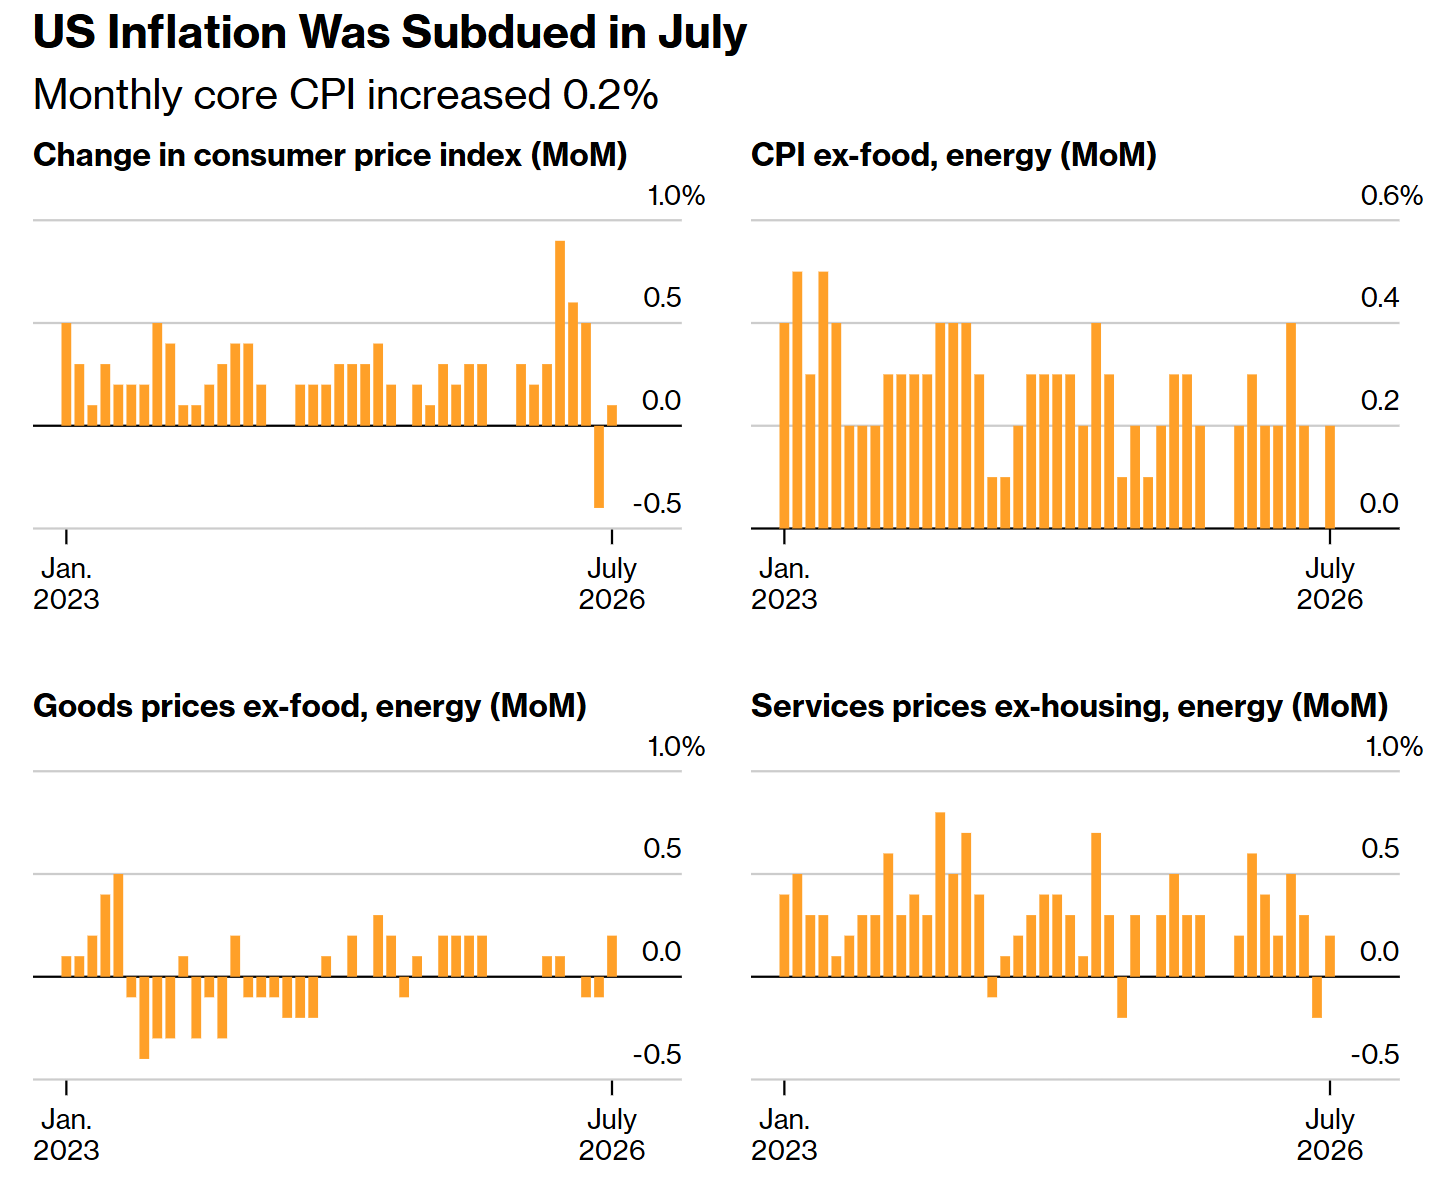
Out at 10:30 am, the headline Consumer Price Index for July was right in line with expectations at +3.4% y/y, a slight easing from +3.5% in June, while core CPI excluding food and energy was also in line at +2.5% y/y and also eased by 10 bps from June, when it was +2.6%.
- DoRCR INSIGHT: This is good news for consumers, and along with the unexpected decline in Nonfarm Payrolls in July, gives the Fed some breathing room with interest rates, but it is worth noting the headline +3.4% inflation reading is higher than the last reading on wage growth, at +3.2% y/y, and implies a slight reduction in household purchasing power.
Out yesterday and acc'd to the U.S. Energy Information Administration, a gallon of regular Unleaded Gasoline cost $4.01 on average across the US for the week ended 8/10/26, down $0.07 from the prior week but up $0.89 per gallon from the same week last year.
- A gallon of diesel cost $5.26, down $0.09 on the week but up $1.50 from last year.
- DoRCR INSIGHT: Gas prices could come down quickly with a US/Iran peace deal and reopening of the Strait of Hormuz, but for now, the significant y/y increase is a meaningful headwind to discretionary spending, esp by lower-income consumers (e.g. core dollar store customer).
Also out yesterday, Existing Home Sales for July were essentially in line with expectations and declined 2% m/m to an annualized rate of 4.06M, while Existing Home Sales increased 1% on a year-over-year basis, and the median sales price of an existing home grew 2% y/y, to $434,100.
- DoRCR INSIGHT: High mortgage rates -- the average 30-year fixed rate mortgage was 6.5% in July -- continue to suppress housing turnover, but there are signs of life in some areas of retail more dependent on home sales, including furniture, based on recent reports from Wayfair, which grew US revs by 9% in the second quarter, and Arhaus, which grew comp written sales by 12.5%.
Source: BLS and Bloomberg (for chart)
SELECT ANALYST ACTIONS
Gap (GAP, $20.96) Jefferies downgrades from Buy to Hold and lowers its target from $29 to $23 in front of 2Q26 (July) results on 8/27/26 after the close, has growing concerns about softer trends at Old Navy and cites its proprietary data suggesting an increase in promotions, also notes comparisons get more difficult in the back half of the year.
On Holding (ONON, $30.91) Raymond James downgrades from Strong Buy to Outperform and lowers its target from $52 to $38 after the 2Q26 (June) results, says it remains constructive overall on the stock but has less confidence in near-term upside given pressure on North America wholesale sales following the revenue miss in the quarter.
On Holding (ONON, $30.91) William Blair downgraded from Outperform to Market Perform with no price target intraday yesterday after the 2Q26 (June) results, gives management credit for maintaining price to support brand health amid competitor promotions but says it now has less confidence in its wholesale revenue and its earnings estimates for the next 12 months.
Search Select Analyst Actions for the past 12 months here
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.