Companies and Subjects discussed in this morning's report include: Strong online sales during Amazon's Prime Big Deal Days and competitor events, Aritzia is on a tear and focused on the US, U. Mich. Sentiment falls to five-month low in early-October, Spirit Christmas opening more seasonal stores this year...

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Friday, October 9, 2026 | Published Daily by ~11:30 AM ET
Strong Online Sales from Amazon, Others This Week + Aritzia's Robust US Growth and Weak U. Mich...
NEXT WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (10/12)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
Tuesday (10/13)
- Albertsons reports 2Q26, call 8:30 am, Street at comps down 0.9%, EPS of $0.33
- Existing Home Sales for September at 10:00 am, Street at 3.96M SAAR vs. prior 3.98M
Wednesday (10/14)
- Chewy doing investor meetings in NYC, hosted by Oppenheimer
- Consumer Price Index for September at 8:30 am, Street at +3.6% y/y vs. prior +3.4%
- Retail Marketing Society monthly webinar at noon, topic is Retail & Consumer Private Equity, DoRCR will open with a brief macro/consumer update, info here
- DoRCR hosts its monthly Retail & Consumer Zoom webinar at 2:00 pm, link to join here, will cover macro/consumer issues + a review of YTD store opening/closing announcements
Thursday (10/15)
- Retail Sales for September at 8:30 am, Street at +0.4% m/m vs. prior +1.2%
- Producer Price Index for September at 8:30 am, no y/y estimate yet, prior +5.4%
- Jobless Claims for the week ended 10/10/26 at 8:30 am, Street at 197K vs. prior 197K
Friday (10/16)
- DoRCR publishes its proprietary Next Week's Calendar
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is down 0.3% as of ~10:25 am vs. a 0.3% gain in the S&P 500. Retail stocks are underperforming as U. Mich. Sentiment falls to a five-month low in early-October.
- Weaker retail stocks include PLCE, DDS, DLTH, LEVI and FND, all down 3%-5%.
- Stronger retail stocks include MNSO, BRLT, BABA, LVLU and PRPL, all up 3%-5%, while Aritzia's stock, which trades in Toronto, ticker ATZ, is up 15% on very strong results.
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
- As we've discussed, other retailers once again piggybacked off Prime Big Deal Days and ran their own promotions this week, including Target, Walmart and Kohl's.
- Adobe said discounts reached a peak of 20% off the listed price during Prime Big Deal Days and noted the biggest discounts were in computers, TVs, electronics, toys and apparel.
- Purchases made on mobile devices grew 13% y/y, to $5.1B, or 52% of all online sales, while purchases made using buy now, pay later increased 4%, to $692.3M, or 7% of the total.
- Numerator had a similar to take to Adobe and said average household spend for Amazon Prime Big Deal Days was $114.01, up from $104.69 last year, or an increase of 8.9%.
- As previously announced, Adobe is looking for US online spending for the official holiday period of November-December to grow 6.7% y/y, to $275.1B.
- DoRCR INSIGHT: While it's still very early, this is probably a good read on underlying consumer health and willingness to spend around events and therefore a positive indicator for holiday, which would be consistent with some of the forecasts for mid-single-digit growth in sales for the November-December period and continued outperformance of online vs. stores.
Analyst Actions that could move retail stocks today:
- VF Corporation (VFC, $14.53) JPM upgrades from Underweight to Neutral
OTHER DEVELOPMENTS
Aritzia (C$129.89) had another very strong and better-than-expected quarter -- 2Q27, ended August -- and comped up 34.5%, while total sales grew 40%+ to C$1.17B on the comp and new store growth, and adjusted EBITDA doubled to C$246.2M, with 590 bps of y/y margin improvement excluding benefits from tariff refunds, to 21.0% on IMU improvements, occupancy leverage and improved markdowns, and management raised full-year guidance again.
- Growth was broad-based across geographies, channels and merchandise categories, and the US remained the #1 market, with sales up 60% to C$779.4M, or 67% of the total.
- Digital revs grew 68% y/y to C$402.9M, or 34% of the total vs. 30% last year, suggests the company's growing store fleet + brand awareness are having a halo effect online.
- Aritzia finished the quarter with 146 boutiques vs. 134 last year and continues to focus on the US for growth, with 2Q27 expansion into Birmingham, AL, New Orleans and St. Louis.
- Plans call for six new US boutiques in the current quarter, two in Texas and one each in Florida, Georgia, Massachusetts and Nevada.
US Video Game hardware sales fell 3% year-over-year to $302M in August acc'd to the latest data from Circana, which puts hardware sales down 11% YTD, while sales of accessories increased 3% in August, to $176M, but are down 4% y/y through the first eight months of 2026.
MINISO (China) said GMV for its US business grew by ~20% y/y in the third quarter and incorporated 30%+ growth and positive store comps in September, driven in part by new merchandise.
Movado is selling a 95% of its Swiss watch brand Ebel to Geneva-based F.P.Journe with participation from Chanel and veteran watch executive Pierre Jacques, who will become CEO of Ebel following the transaction, which is expected to close within a few months.
COMMERCIAL REAL ESTATE
Spirit Christmas, which is part of Spencer Spirit Holdings, plans to open 44 temporary stores across 15 states for its third season, including the first stores in Florida after opening 30 temporary stores last year and 10 stores on the East Coast in 2024, its first year in operation.
- The first five stores will open in mid-October, while the remaining 39 stores will make the transition from Spirit Halloween to Spirit Christmas in the first week of November.
- Store locator here, shows locations by state and also shows the timing.
Publix, which has 1,400+ stores, including ~900 in Florida, recently opened its 10th store in Kentucky, in Florence (Cincinnati area), and said it plans to open 16 more stores in the state.
Diff Eyewear, a digital native eyewear retailer based in Los Angeles, will open its first store Sunday, an 1,800 square foot flagship on King Street in Charleston, South Carolina, plans to open three more stores in the coming months, and sees potential for 40 stores over the next four years.
Wayfair (digital native) said earlier this week it will open a new large-format 86K square foot store on a single level at Market Place at Garden State Park in Cherry Hill, NJ in late-2028, will be store #11.
MANAGEMENT UPDATES
We're not seeing anything too significant/noteworthy this morning...
MACRO/CONSUMER INSIGHT
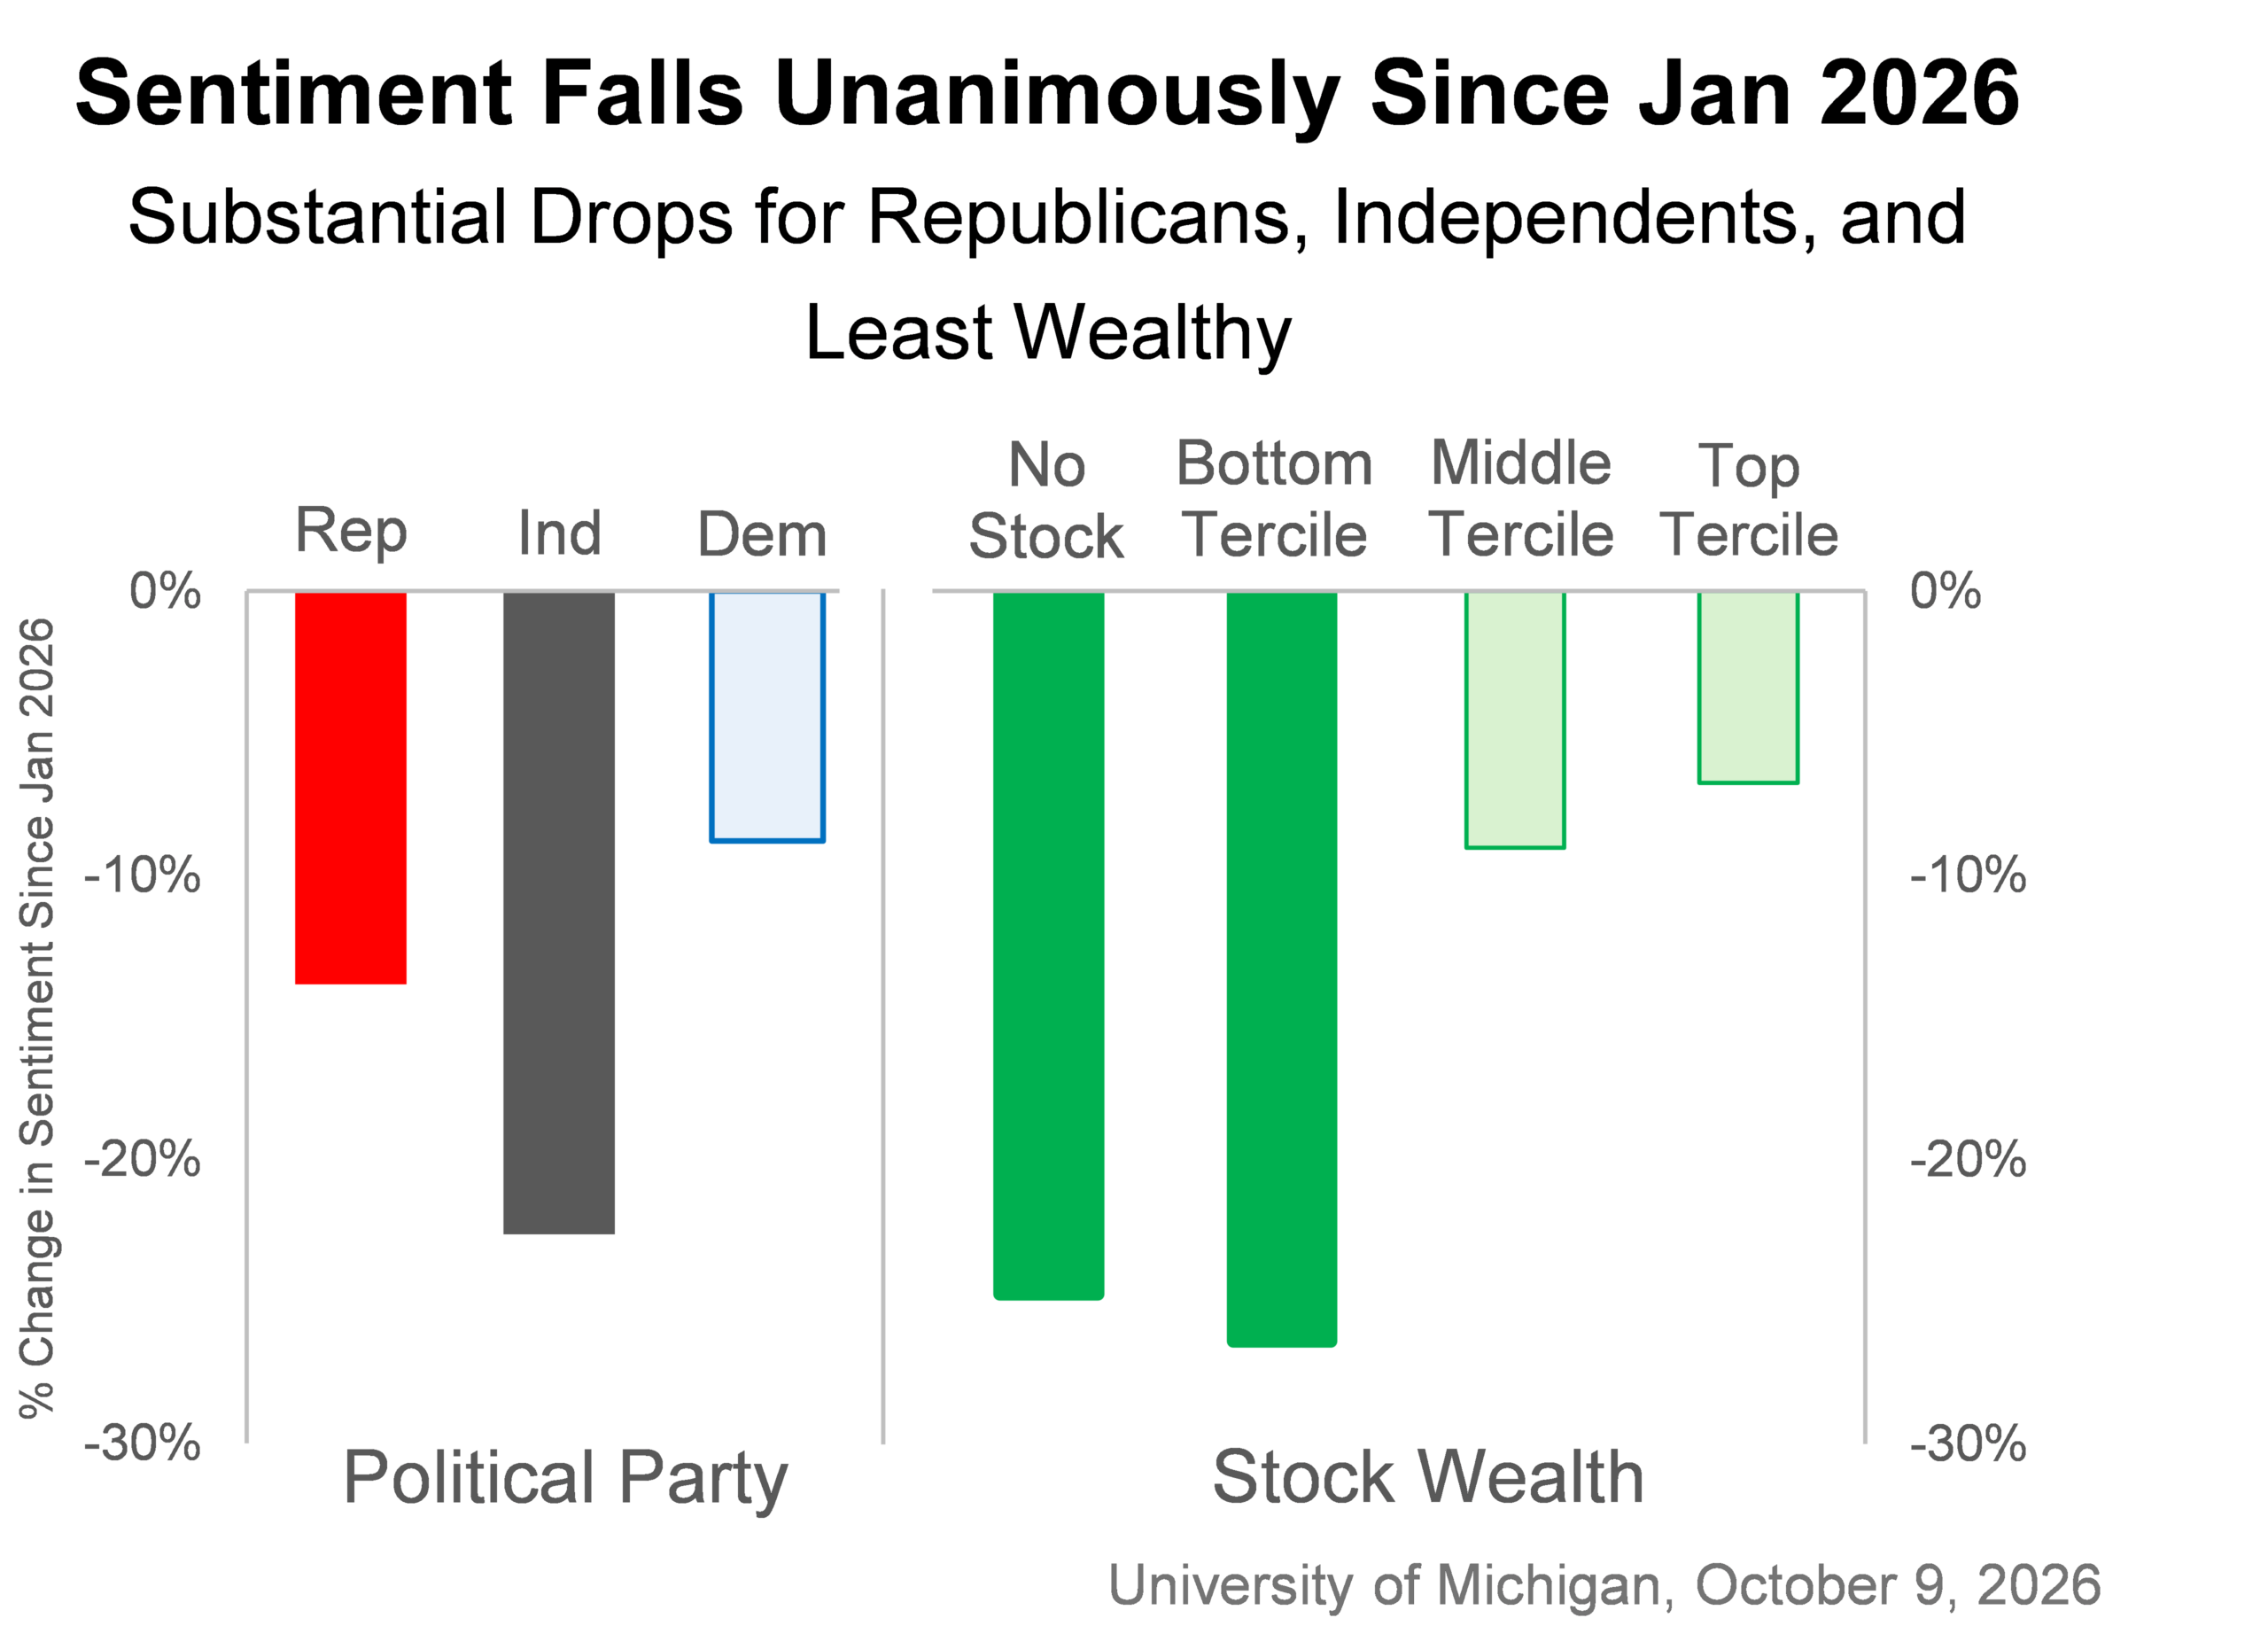
Out at 10:00 am, U. Mich. Sentiment for October (preliminary) was even weaker than expected at 46.3 vs. the Street's 47.8 and down from a final read of 48.1 in September on worries about high prices and the impact of rising interest rates on borrowing costs, including for mortgages.
- The decline in sentiment was sharpest among lower-income consumers and those with small/no stock portfolios who have participated less, or not at all, in the market's record run.
- DoRCR INSIGHT: While confidence/sentiment surveys have been poor predictors of consumer discretionary spending, this update is notable and concerning, especially the increase in year-ahead inflation expectations, from +4.6% September to +4.7% in early-October.
Out yesterday, Jobless Claims for the week ended 10/3/26 were lower than expected at only 197K vs. the Street's 201K estimate and down 2K from a revised 199K the prior week, while Continuing Claims, which are reported with a week's lag, increased by 17K to 1.72M.
- DoRCR INSIGHT: The labor market is looking better after a soft July, as Nonfarm Payrolls accelerated in August-September, while weekly Jobless Claims hovering in the 200K area suggest employers are holding onto their workers despite macro uncertainty.
Out Tuesday and acc'd to the U.S. Energy Information Administration, a gallon of regular Unleaded Gasoline cost $4.35 on average across the US for the week ended 10/5/26, down $0.12 from the prior week but up $1.23 per gallon from the same week last year.
- A gallon of diesel cost $6.20, down $0.18 on the week but up $2.49 from last year.
- DoRCR INSIGHT: Consumers have shown good discretionary spending resilience recently, but we are in worrisome territory with gas prices now in the mid-$4 area, while diesel at $6+ a gallon is a major headwind to retailers' distribution and transportation costs.
SELECT ANALYST ACTIONS
Search Select Analyst Actions for the past 12 months here
(opens in new tab)opens in new tab) in new tab)(opens in new tabSearch Select Analyst Actions for the past 12 months hereopens in new tab)
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.