Companies and Subjects discussed in this morning's report include: O'Reilly reports a strong third quarter, with sequential comp acceleration, Crocs beats and raises on an inflection to positive growth at HEYDUDE, Sprouts has a tough third quarter and lowers guidance, macro data remain supportive of spending...

DoRCR Reports are for Individual Paid Subscribers | Pls Do Not Share Internally or Externally
DoR Consumer Research
Investor Oriented | Retail & Consumer
Thursday, October 29, 2026 | Published Daily by ~11:30 AM ET
Strong Results from O'Reilly and Crocs, a Soft 3Q26 from Sprouts, Supportive Macro Data...
THIS WEEK'S CALENDAR
UPDATED EACH MORNING
All Times Are Eastern
Monday (10/26)
- DoRCR publishes its proprietary weekly Store Opening/Closing Analysis
Tuesday (10/27)
- Consumer Confidence for October at 10:00 am, Street at 80.5 vs. prior 81.9
- New Home Sales for September at 10:00 am, Street at 650K SAAR vs. prior 684K
- Aritzia hosts an Investor Day in NYC, starts at 10:15 am and will be webcast
Wednesday (10/28)
- VF Corporation reports 2Q27, call 8:00 am, Street at sales/EPS of $2.67B/$0.54
- Etsy reports 3Q26, call 8:30 am, Street at sales/EPS of $668.1M/$0.76
- FOMC rate decision at 2:00 pm, investors expect no change in the 3.75%-4.00% target
- O'Reilly reports 3Q26 after the close, Street at comps up 4.5%, EPS of $0.93
- Boot Barn reports 2Q27, call 4:30 pm, Street at comps up 1.5%, EPS of $1.64
- Sprouts reports 3Q26, call 5:00 pm, Street at comps up 0.2%, EPS of $1.23
- eBay reports 3Q26, call 5:30 pm, Street at sales/EPS of $3.12B/$1.41
Thursday (10/29)
- Jobless Claims for the week ended 10/24/26 at 8:30 am, Street at 200K vs. prior 194K
- Personal Income/Spend for Sept at 8:30 am, Street +0.3%/+0.5% m/m, prior +0.2%/+0.9%
- Crocs reports 3Q26, call 8:30 am, Street at sales/EPS of $1.00B/$3.31
- Adidas reports 3Q26 results, call 10:00 prelim sales/profit were EUR7.25B/EUR1.01B
- O'Reilly 3Q26 call at 11:00 am
- Amazon reports 3Q26, call 5:00 pm, Street at sales/EPS of $202.22B/$1.97
- Floor & Decor reports 3Q26, call 5:00 pm, Street at comps down 1.4%, EPS of $0.57
- Columbia Sportswear reports 3Q26, call 5:00 pm, Street at sales/EPS of $944.9M/$1.28
- The RealReal reports 3Q26, call 5:00 pm, Street at sales/EPS of $196.9M/$0.00
Friday (10/30)
- DoRCR publishes its proprietary Next Week's Calendar
- Carter's reports 3Q26, call 8:30 am, Street at comps down 0.3%, EPS of $0.85
- Puma reports 3Q26, call 10:00 am, Street at sales of EUR1.77B/(EUR0.33)
- Capri reports 2Q27, call 10:00 am, Street at sales/EPS of $786.5M/$0.21
**Colors Indicate Directional Change from First Time Shown in Our Calendar**
TODAY'S EARLY TRADING
The S&P Retail ETF (XRT) is up 2.1% as of ~10:55 am vs. a 0.3% decline in the S&P 500. Retail stocks are outperforming after upside results from O'Reilly and Crocs and as more indicators suggest resilient consumer spending despite inflation pressures.
- Stronger retail stocks include CROX, which is up 25% after a beat-and-raise 3Q26, also BOOT (up 12%, okay quarter, $400M stock buyback boost), BBW (up 8%), FIGS (up 7%, positive analyst commentary from Oppenheimer) and LVLU (up 6%).
- Weaker retail stocks include SFM, which is down 21% on soft results and analyst downgrades, also PLCE (down 12%, we're not seeing anything), RENT (down 4%), AMZN (down 3% as investors continue to question massive AI spending) and NEGG (down 3%).
MARKET-MOVING DEVELOPMENTS
All Stock Prices as of Last Close
- Comps increased 7.2% on top of 5.6% last year, which put the two-year stack at +12.8% after +10.1% in the second quarter, while total sales grew 9% to $5.12B.
- EPS increased 14% y/y to $0.97 vs. the Street's $0.93 estimate and incorporated 50 bps of gross margin improvement and an operating margin of 21.4% vs. 20.7% last year.
- Inventories look good and were up 10%, in line with sales growth in the quarter.
- 2026 guidance: Comps of +5.5%-6.5% vs. a prior +4%-6%, revs of $19.0B-$19.3B vs. a prior $18.9B-$19.2B and $17.78B last year, an op margin of 19.5%-20.0% vs. 17.9% in 2025 and up 20 bps from before, and EPS of $3.25-$3.35 vs. $2.97 in 2025 and a prior $3.20-$3.30.
- DoRCR INSIGHT: O'Reilly executes very well, has very good service and leading parts availability, and is gaining nice share in a resilient and tariff-resistant industry, and management is focused on reducing expenses but will also sacrifice some profit in order to maintain high levels of customer service at the stores and to preserve ORLY's leading parts availability.
- The (0.9%) comp was slightly below the Street's +0.2%, while total sales grew 5% y/y to $2.30B on new store openings, including 15 in the quarter, which took the total to 504 stores in 25 states, and plans still call for 42 net new stores for the year on a base of 477.
- Mgmt noted strong performance from recent store vintages and said it is taking action to improve execution and drive traffic, including via price investments to increase value.
- EPS were essentially flat y/y at $1.21 vs. the Street's $1.23 estimate and incorporated a 50 bps decrease in gross margin and an EBIT margin of 6.6% vs. 7.2% last year.
- 2026 guidance: Comps of (1.7%) vs. a prior (0.5%)-0.5%, total sales growth of ~4.3% on top of $8.81B last year, and EPS of ~$4.80 vs. $5.31 in 2025 and a prior $5.32-$5.40 and including an estimated $0.16 from a 53rd week, prior guidance was for $0.21 from the extra week.
- Guidance now assumes an add'l $190M of sales from the extra week, prior was $200M, and it also assumes a 2%-4% decline in comps in the fourth quarter vs. the Street's +1.4%.
- DoRCR INSIGHT: Sprouts is still a good story overall, well positioned in the growing market for healthy and organic foods and with plenty of store growth potential given its relatively small size, but there has been some underlying slowing that is raising concerns about heightened competition with Whole Foods (and Amazon) as Amazon ups its investments in fresh food.
- Consolidated revs were $1.04B, up 5% y/y constant currency and above the Street's $1.00B estimate, with DTC revs up 7% y/y and Wholesale revs up 2%.
- Crocs Brand revs were $873M, up 4% y/y, and included DTC revs up 8%, Wholesale revs down slightly, North America revs down 2%, and International revs up 12%.
- HEYDUDE revs were $170M, up 6% y/y, with DTC up slightly and Wholesale up 14%.
- Adjusted EPS increased 26% to $3.69 vs. the Street's $3.31 and incorporated 180 bps of gross margin improvement and 40 bps of SG&A expense de-leverage.
- Ending inventories were up 4% y/y after being down 4% in the second quarter.
- Full-year guidance includes revenues up 3% from last year's $4.04B vs. a prior up 1%-2%, modest expansion in operating margin, and adjusted EPS of $14.45-$14.65 vs. $12.51 last year, a prior $13.70-$14.00 range, and the Street's $13.96 estimate.
- Full-year guidance assumes Crocs Brand revenues up 4% after a slight increase in 2025 and HEYDUDE revs roughly flat on top of a 14% drop in 2025, all constant currency.
- On the Call, management highlighted category expansion for the Crocs brand as a key sales driver in the quarter, especially in sandals, also the new ballet flats.
- DoRCR INSIGHT: The inflection to positive revenue growth at HEYDUDE is very significant given broad concerns about the brand's position in the footwear world and about the wisdom of the acquisition -- Crocs acquired HEYDUDE in early-2022 for ~$2.5B -- and it should be sustainable given new partnerships and collaborations, new styles, and better marketing/engagement.
Boot Barn (BOOT, $113.30) had an okay 2Q27 (Sept) with in-line comps up 1.4%, though this was much slower than the first quarter's +4.7%, while earnings were better than expected and driven in part by $2.2M of tariff refunds and 190 bps of merchandise margin expansion; management also noted a modest slowdown in October and lowered full-year guidance by a fair bit.
- BOOT also announced an add'l $400M for stock buybacks, or 12% of the market cap.
- Comps increased 1.4% on top of +8.4% last year and were in line with the Street's +1.5% estimate, while total sales grew 15% to $581.8M on the comp and a 19% y/y increase in the store count, to 584, including 19 store openings in the second quarter.
- Retail same-store sales increased 1.0%, and e-comm comps increased 5.2%, and by month, consolidated comps were (0.3%)/+2.1%/+2.0% in July/August/September.
- EPS were $1.73 vs. $1.37 last year and the Street's $1.64 and would have been $1.68 absent a $0.05 per share benefit from tariff refunds, added 40 bps to merchandise margin.
- Inventories look a little high and were up 3% y/y on a same-store basis at quarter's end.
- FY27 guidance now includes comps of +0.8%-2.0% vs. a prior +2%-4% and sales up 14%-15%, to $2.57B-$2.59B, vs. a prior up 14%-16%, while EPS are expected at $8.72-$9.00 vs. $7.35 in FY26 and a prior $8.80-$9.23 and including $0.45 from tariff refunds vs. a prior $0.46.
- Third quarter guidance includes comps of (1%)-1.0% against a +6.1% comparison and reflects +0.4% for October through the first four weeks of the month.
- Full-year guidance now assumes 75-80 new stores, implies 14% growth, prior was 70.
- DoRCR INSIGHT: Boot Barn is still a very attractive retail growth story with plenty of room to continue expanding footage by a double-digit %, but recent trends have been choppy and could reflect macro factors, including high gas/diesel prices, as well as issues with the assortment, which mgmt is working to refresh while expanding the national marketing campaign.
Analyst Actions that could move retail stocks today:
- eBay (EBAY, $118.02) Wells Fargo upgrades from Underweight to Equal Weight
- VF Corporation (VFC, $17.23) BNP Paribas upgrades from Underperform to Neutral
- Sprouts (SFM, $62.00) BofA downgrades from Buy to Underperform
- Sprouts (SFM, $62.00) RBC downgrades from Outperform to Sector Perform
INDUSTRY INSIGHT
Adidas (ADS-DE, EUR158.05) had a better than expected 3Q26 (Sept), consistent with last week's preliminary numbers, and grew currency-neutral revs by 7% y/y after +14% in 2Q26, which got a big boost from the lead-up to the FIFA World Cup and from the start of the tournament, while EUR200M of tariff refunds, along with strong full-price sales, drove 250 bps of gross margin improvement.
- Reported revs were EUR7.25B, up 9% y/y and above the Street's EUR7.11B, while operating profit hit a quarterly record of EUR1.01B, up 35%+ from last year's third quarter and reflecting the rev growth, tariff refunds, and higher full-price sales, partially offset by forex.
- For the year, op profit is now expected at EUR2.5B vs. EUR2.06B in 2025 and a prior EUR2.3B and assuming EUR100M of the tariff refunds are reinvested in op leverage initiatives.
- Currency-neutral revs are still expected to grow 9%-10% from EUR24.81B in 2025.
- DoRCR INSIGHT: Adidas is significantly outperforming key competitors, including Nike and Under Armour, and seems to be getting a lift from new lifestyle apparel collections, while its footwear lifestyle biz is still difficult amid high inventory + aggressive discount across the industry.
Kroger and Albertsons continue to lose CPG share to Walmart, Amazon and Costco acc'd to the latest data from Numerator, which puts Walmart at the top of the list with a 20.8% share, up 10 bps from this time a year ago, then Costco at #2 with 8.2%, up 50 bps, and Amazon and Whole Foods at #3, with 8.1%, up 70 bps, while Kroger is #4 with 6.7% share, and Sam's Club is #5 with 3.6%.
- Walmart is also at the top of the list for grocery market share, with 20.3%, then Costco at 8.4%, Kroger at 8.2%, Albertsons at 4.5% and Publix at 4.1%.
- In grocery market share, Costco overtook Kroger in this latest Numerator update.
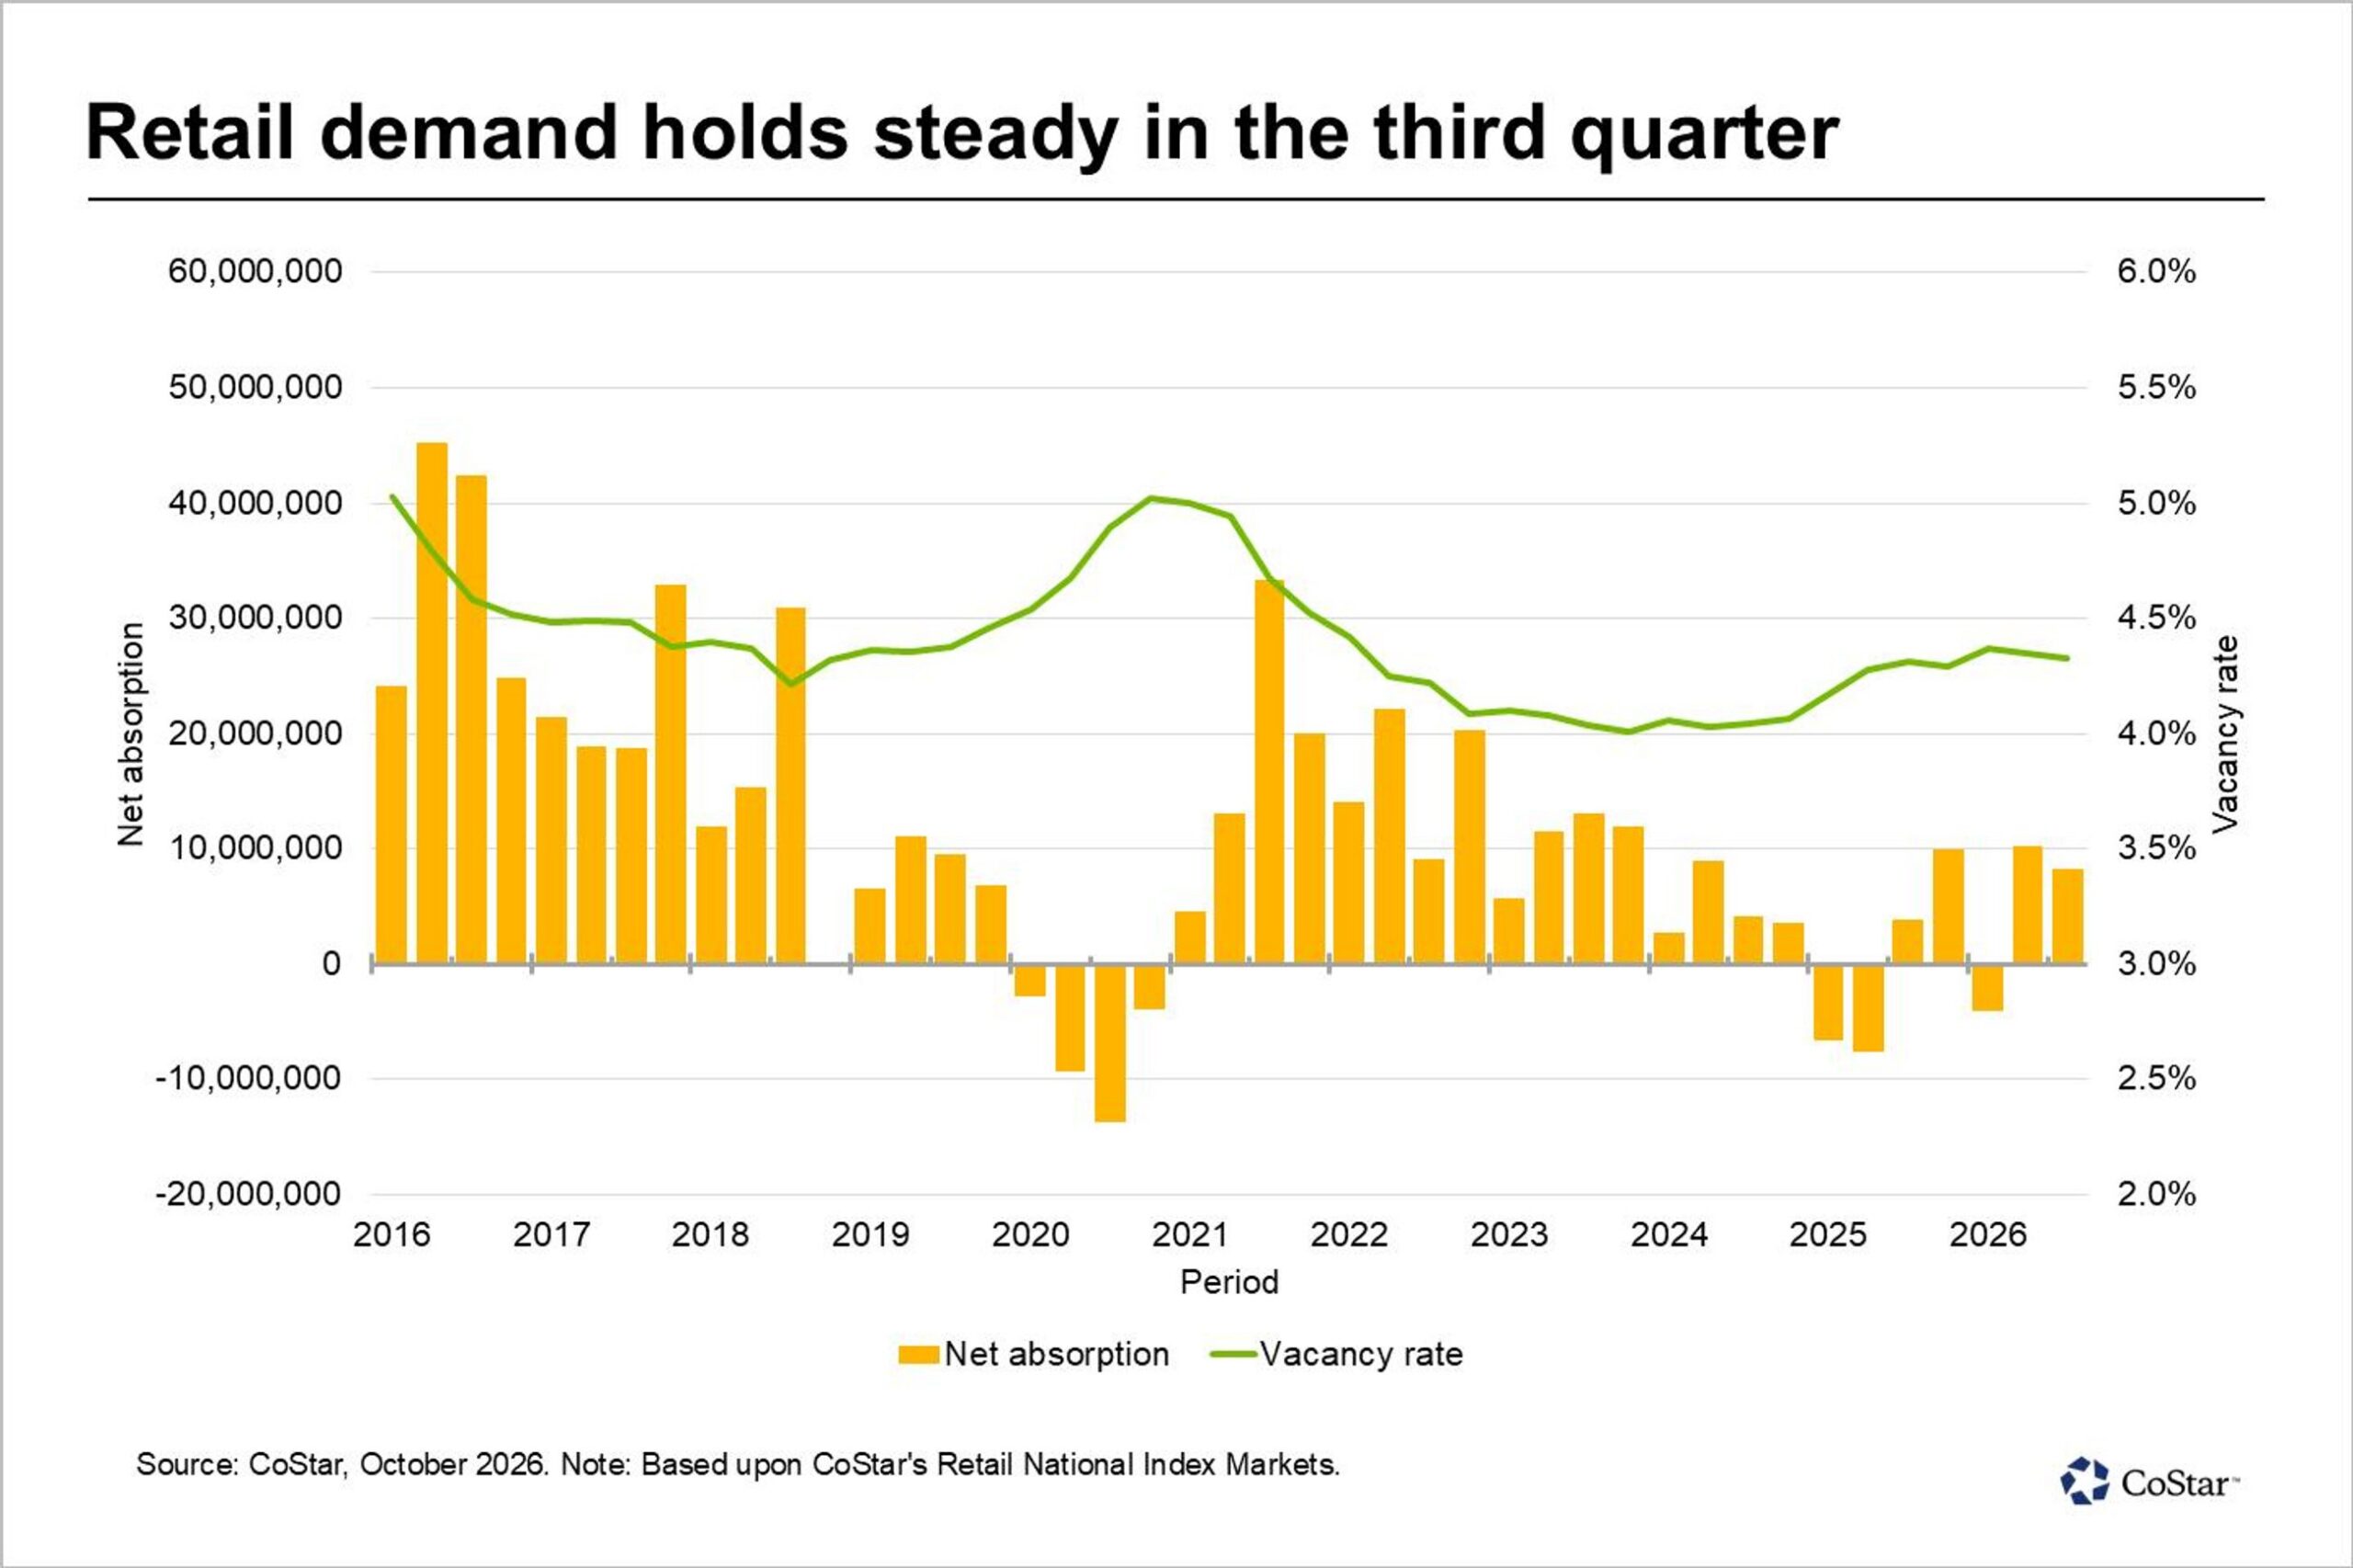
The national retail vacancy rate declined slightly in the third quarter, to 4.4%, as retail tenants moved into ~97M square feet of existing space, the highest amount of existing space filling since the middle of 2022 and the second straight quarter above 96M square feet acc'd to CoStar, which said expanding retailers are taking space that has been vacated by some of the larger chains.
- The firm also said low availability is causing tenants to commit quickly when they find the right space and noted move-outs declined 7% y/y, to 92M square feet of space.
OTHER DEVELOPMENTS
eBay (EBAY, $118.02) had a strong and better-than-expected third quarter and grew currency-neutral GMV by 16% after +14% in the second quarter, while revs were $3.21B, up 13%, and EPS grew 12% y/y to $1.51 vs. the Street's $1.41 estimate; management also raised full-year guidance.
- eBay is getting a lift from strong growth in collectibles and growth in livestream shopping.
UK-based Poundland is planning to go into administration a little over a year after Gordon Brothers acquired the business for a token GBP1 acc'd to Bloomberg, which says 12K jobs are at risk across Poundland's ~600 stores and notes Gordon Brothers has struggled to find a buyer for the chain. Previous reports had TGJones owner Modella Capital showing some interest in acquiring Poundland.
COMMERCIAL REAL ESTATE
Publix, which has 1,450 stores, including ~900 in its home state of Florida, opened a new store in Calabash, North Carolina this week, 46,800 square feet, at the Commons at Carolina Shores.
Raymour & Flanigan, which is based in Syracuse, NY and sells furniture and mattresses through 150+ stores in eight states and online, announced plans for two stores that will open late next year, a 75K square foot store in Danvers, MA, and a 105K square foot store in Nashua, NH.
MANAGEMENT UPDATES
Ralph Lauren SVP, Global Public Relations and Brand Communications since 2005 Ryan Lally has been promoted to Chief Brand Communications Officer, a new position.
MACRO/CONSUMER INSIGHT
Out at 8:30 am, Jobless Claims for the week ended 10/24/26 were lower than expected at only 194K vs. the Street's 200K and down slightly from a revised 195K the prior week, while Continuing Claims, which are reported with a week's lag, declined by 21K, to 1.70M, lowest since March 2023.
- DoRCR INSIGHT: The labor market is looking better after a soft July, as Nonfarm Payrolls accelerated in August-September, while weekly Jobless Claims hovering in the 200K area suggest employers are holding onto their workers despite macro uncertainty.
Also out at 8:30 am, Personal Income for September was a touch light of expectations at +0.2% m/m vs. the Street's +0.3% estimate after a revised +0.3% in August, while Personal Spending was right in line at +0.5% after +0.9% in August, and the savings rate was 3.8%, lowest since late-2022.
- DoRCR INSIGHT: Incomes continue to grow at solid rate, and, along with other factors including the strong stock market and record home equity levels, are providing good spending support -- household spending grew by an annualized 3.8% in the third quarter, same as 2Q26.
Out Tuesday, Consumer Confidence for October was better than expected at 91.7 vs. the Street's 80.5 estimate and increased from an upwardly revised 84.2 in September, driven in part by an easing of inflation expectations and improved sentiment around the labor market.
- DoRCR INSIGHT: The m/m improvement is directionally similar to what we saw last week with U. Mich. Sentiment and is in part a reflection of the direction of gasoline prices, which eased just a bit each week of the month in October and helped bring concerns about inflation down just a bit -- 12-month inflation expectations are now +5.8% vs. +6.1% in September.
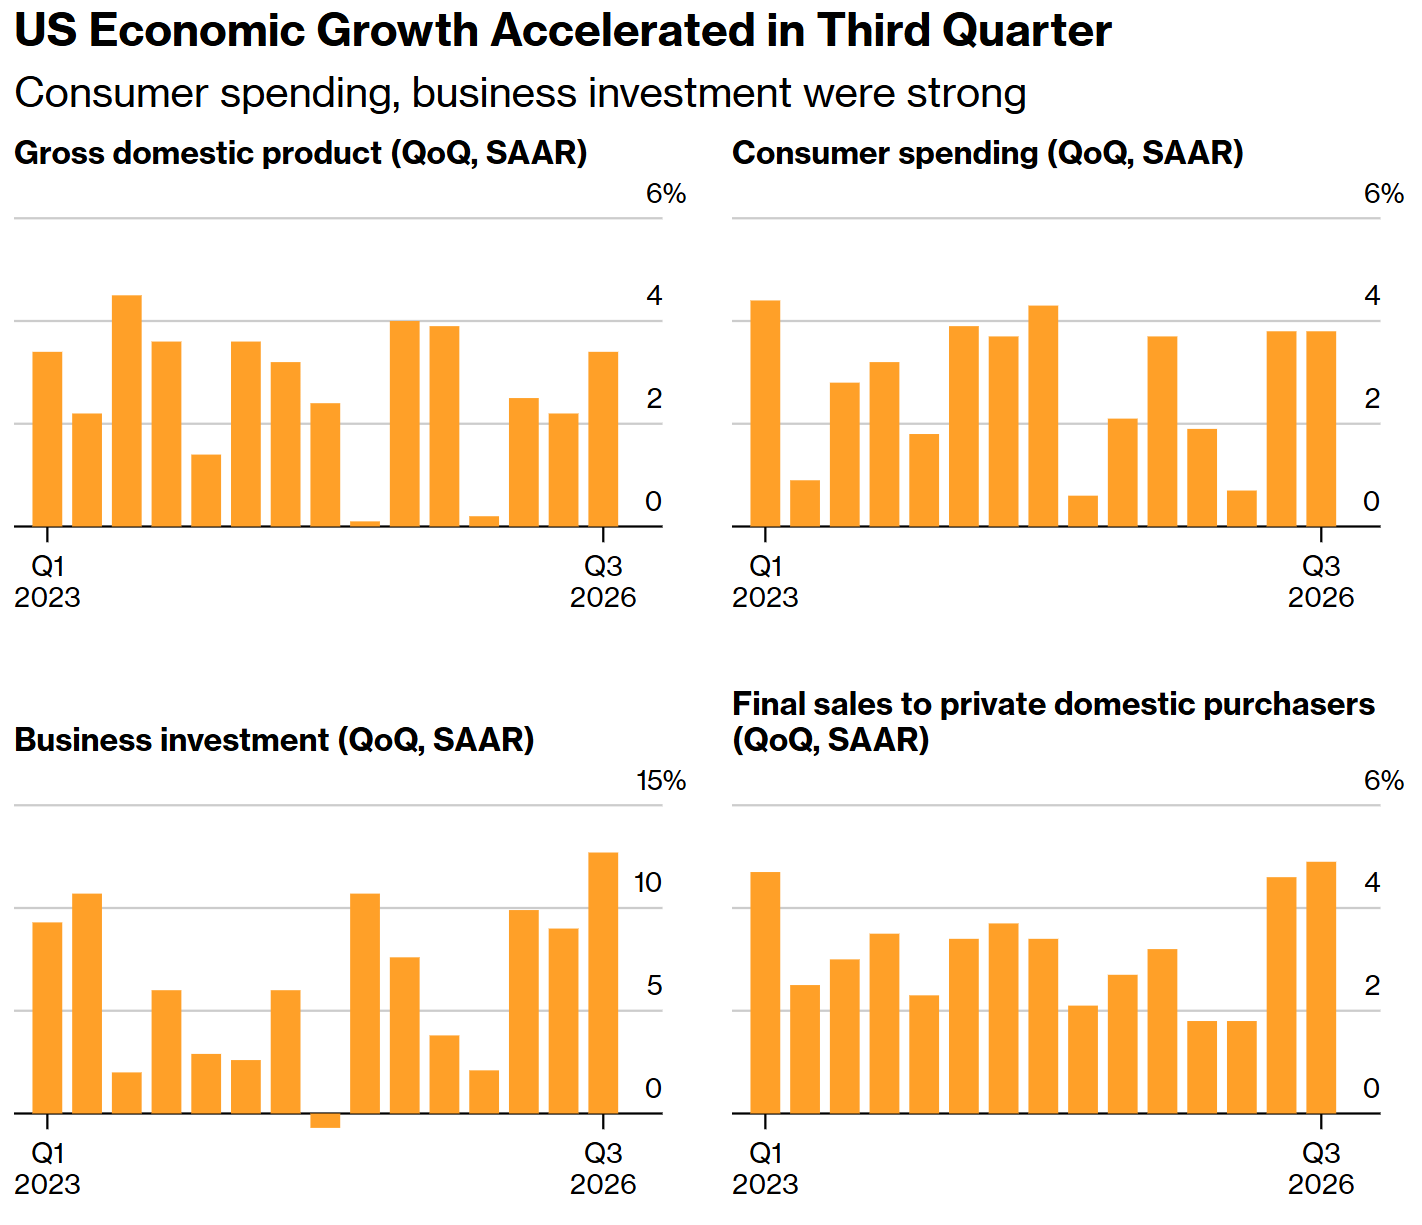
Source: BEA and Bloomberg (for chart)
SELECT ANALYST ACTIONS
Sprouts Farmers Market (SFM, $62.00) BofA downgrades from Buy to Underperform and lowers its target from $100 to $47 after the third quarter results, says comps were pressured by the macro and by cyclospora disruption and sees a declining profitability outlook amid challenges to sales and customer traffic trends, also thinks price investment will pressure basket.
Sprouts Farmers Market (SFM, $62.00) RBC downgrades from Outperform to Sector Perform and lowers its target from $111 to $49 after the third quarter results, says recent comp weakness is more company specific than cyclical and believes Sprouts is lagging vs. growing competition, also says it doesn't have much confidence customers will respond positively to price investments.
VF Corporation (VFC, $17.23) BNP Paribas upgrades from Underperform to Neutral and raises its target from $13 to $16 after the 2Q27 (Sept) results, says it is more confident in VF's turnaround, especially with Vans, and believes growth at other brands, including The North Face, is sustainable, also raises its forecast to reflect what it believes is greater sales and margin visibility.
Search Select Analyst Actions for the past 12 months here
(opens in new tab)opens in new tab) in new tab)(opens in new tabSearch Select Analyst Actions for the past 12 months hereopens in new tab)
This material is for paid subscribers only
Full Terms of Use are available here
UNAUTHORIZED USE OR DISTRIBUTION IS UNLAWFUL
Disclaimer: DoR Consumer Research publishes a financial report of general and regular circulation which does not offer individualized investment advice attuned to any specific portfolio or any person’s particular needs. No mention of a particular security in our reports constitutes a recommendation to buy, sell, or hold any security, or that any particular security, portfolio of securities, transaction or investment strategy is suitable for any specific person.
Any reliance you place on such information is strictly at your own risk.
BEFORE SELLING OR BUYING ANY STOCK OR OTHER INVESTMENT YOU SHOULD CONSULT WITH A QUALIFIED BROKER OR OTHER FINANCIAL PROFESSIONAL TO VERIFY PRICING INFORMATION AND TO SOLICIT ADVICE AS TO THE APPROPRIATENESS OF A GIVEN TRANSACTION OR INVESTMENT.